


EN
Recursion Pharmaceuticals (RXRX) Shares Just Moved, So What Is Going On?
Recursion Pharmaceuticals (RXRX) just packed several catalysts into one week, reporting third quarter results that showed higher revenue and a narrower loss, while also releasing promising Phase 2 data for its FAP candidate REC-4881.
Despite the stronger third quarter and REC-4881 update, Recursion Pharmaceuticals’ 1-day share price return declined 4.35%, and the 7-day share price return fell 9.52%, while the year-to-date share price return is down 24.17% and the 3-year total shareholder return has declined 54.82%. This points to long-term pressure even as near-term momentum has softened.
Scan beyond Recursion Pharmaceuticals and compare it with hand-picked biotechs working on high-impact therapies using the 36 healthcare AI stocks as your next research step.
Recursion Pharmaceuticals now trades at a steep discount to both analyst targets and one intrinsic value estimate after this pullback. Is that a genuine mispricing, or is it a fair reflection of the risks around its drug pipeline and losses?
Most Popular Narrative: 56% Undervalued
On the analyst consensus Narrative on Simply Wall St, Recursion Pharmaceuticals screens as materially undervalued, with a fair value of $7.32 against a last close of $3.19. This puts the focus squarely on how its AI driven platform and drug programs might eventually translate into commercial assets.
Progression of first in class internal assets such as REC 4881 for familial adenomatous polyposis and REC 1245 for genomically unstable tumors toward later stage trials and potential regulatory milestones creates opportunities for future product and licensing revenue that are not yet reflected in current earnings.
See why 142 investors see Recursion Pharmaceuticals as 56% undervalued.
Result: Fair Value of $7.32 (UNDERVALUED)
Still, the Recursion Pharmaceuticals story can fray if milestone revenue remains uneven or if ongoing losses and dilution keep dragging on per share outcomes.
Find out about the key risks to this Recursion Pharmaceuticals narrative.
Another Angle On Recursion Pharmaceuticals’ Valuation
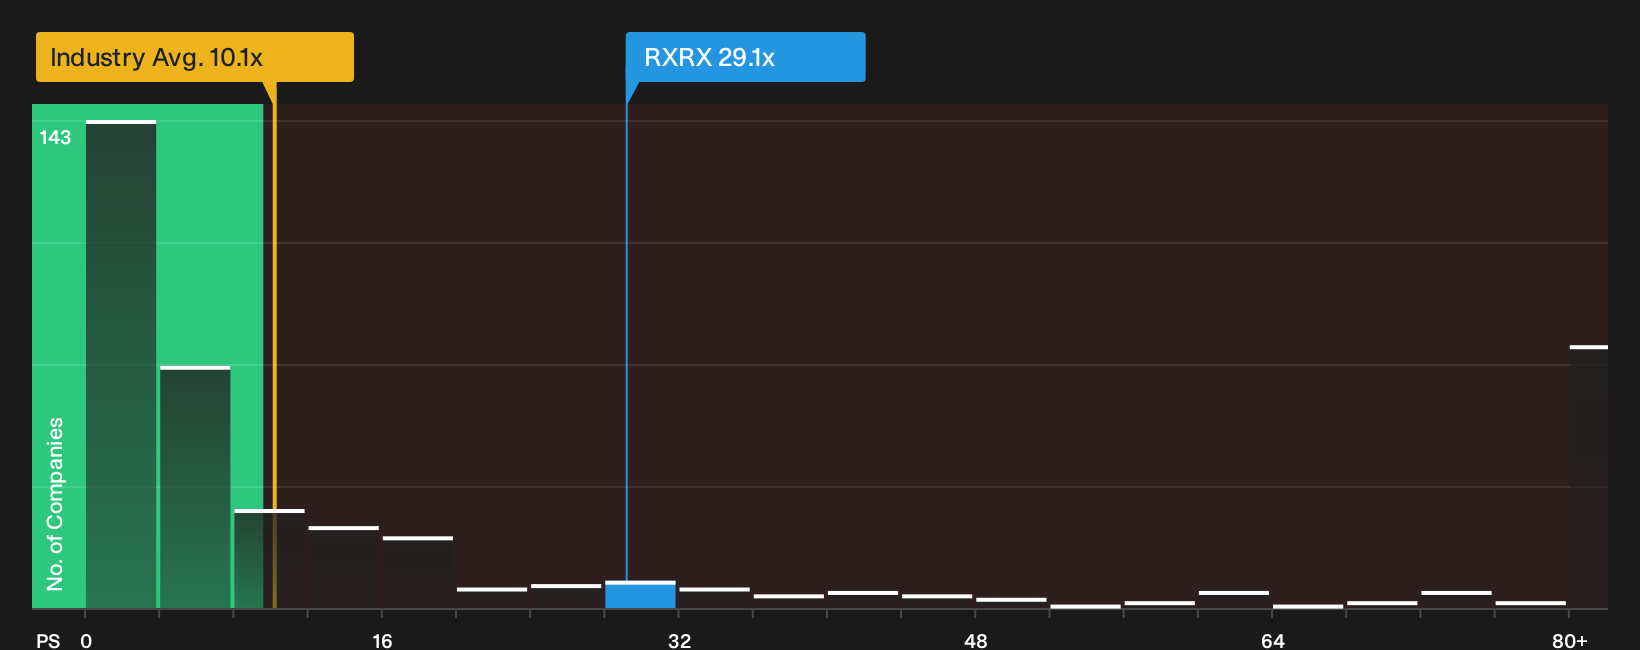
On price targets and fair value models, Recursion Pharmaceuticals looks cheap. The picture changes when you look at its P/S ratio of 29.1x versus a fair ratio of 0x, and 10.1x for the wider US Biotechs group and 9.1x for peers. That kind of premium raises the question of how much pipeline risk is already priced in, and how much is still on you as an investor.
To see how that P/S gap fits into the rest of the story, including peers and profitability risks, take a closer look at our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Recursion Pharmaceuticals is clearly split, with meaningful risks on one side and real upside potential on the other. Act quickly, review the numbers, and weigh both the 1 key reward and 3 important warning signs in the 1 key reward and 3 important warning signs.
Looking for more Recursion Pharmaceuticals sized ideas?
If Recursion Pharmaceuticals is on your radar, do not stop here. Use the Simply Wall St screener to uncover more targeted opportunities that match your style.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that filters for companies with stronger financial foundations and fewer surprises.
- Hunt for mispriced quality by using a 34 high quality undervalued stocks that highlights businesses the market may be overlooking right now.
- Stack potential income and stability by reviewing a 6 dividend fortresses focused on higher yielding companies that still clear key fundamental checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com