


EN
Xcel Energy (XEL) Tightens Guidance As Data Center Growth Tests Its Undervalued Case
Xcel Energy (XEL) just tightened its earnings guidance and highlighted a US$70b five year investment plan, with management pointing to growing data center power demand as a key driver of future capital deployment.
Recent trading has been quietly constructive, with a 7 day share price return of 2.44% and a 30 day share price gain of 6.95% lifting Xcel Energy to US$81.61. The 4.42% 1 year total shareholder return and 49.09% three year total shareholder return suggest longer term momentum has been stronger than the latest move implies.
Scan how Xcel Energy’s data center and grid build out theme compares with other regulated utilities by reviewing the hand picked 44 power grid technology and infrastructure stocks in the same space.
Bulls see Xcel Energy’s US$70b grid and data center build as a springboard, while bears focus on execution risk and fresh debt. Which reading does current valuation support next?
Most Popular Narrative: 9% Undervalued
Against Xcel Energy’s last close at $81.61, the analyst consensus Narrative on Simply Wall St anchors fair value at $89.44 using a 7.24% discount rate. This frames the stock as trading at a clear discount and puts the focus on whether execution can close that gap.
Xcel Energy is entering a larger infrastructure investment cycle, with a five year capital plan now above US$70b and additional opportunities identified, which can add to the regulated asset base and support future revenue and earnings.
AI and data center driven large load growth, including 1 GW of data centers in operation or under construction, 1 GW under signed agreements and a targeted additional 4 GW of load by year end 2027, is expected to require significant new generation and transmission investment that can expand rate base and long term earnings power.
See why 20 investors see Xcel Energy as 9% undervalued.
Result: Fair Value of $89.44 (UNDERVALUED)
Still, wildfire liabilities and any reset in analyst growth assumptions for Xcel Energy, especially around data center driven load, could quickly test that undervaluation thesis.
Find out about the key risks to this Xcel Energy narrative.
Another View: Cash Flows Tell A Different Story
Fair value from the Simply Wall St DCF model lands at $71.94, which is below Xcel Energy’s $81.61 share price. That points to the stock screening as overvalued on future cash flows even though the analyst narrative frames it as 9% undervalued. Which lens do you trust more right now?
For readers who want to see how a full cash flow build feeds into that outcome, the detailed SWS model lays out each step, from forecasts to discount rate inputs, in a single place Look into how the SWS DCF model arrives at its fair value..
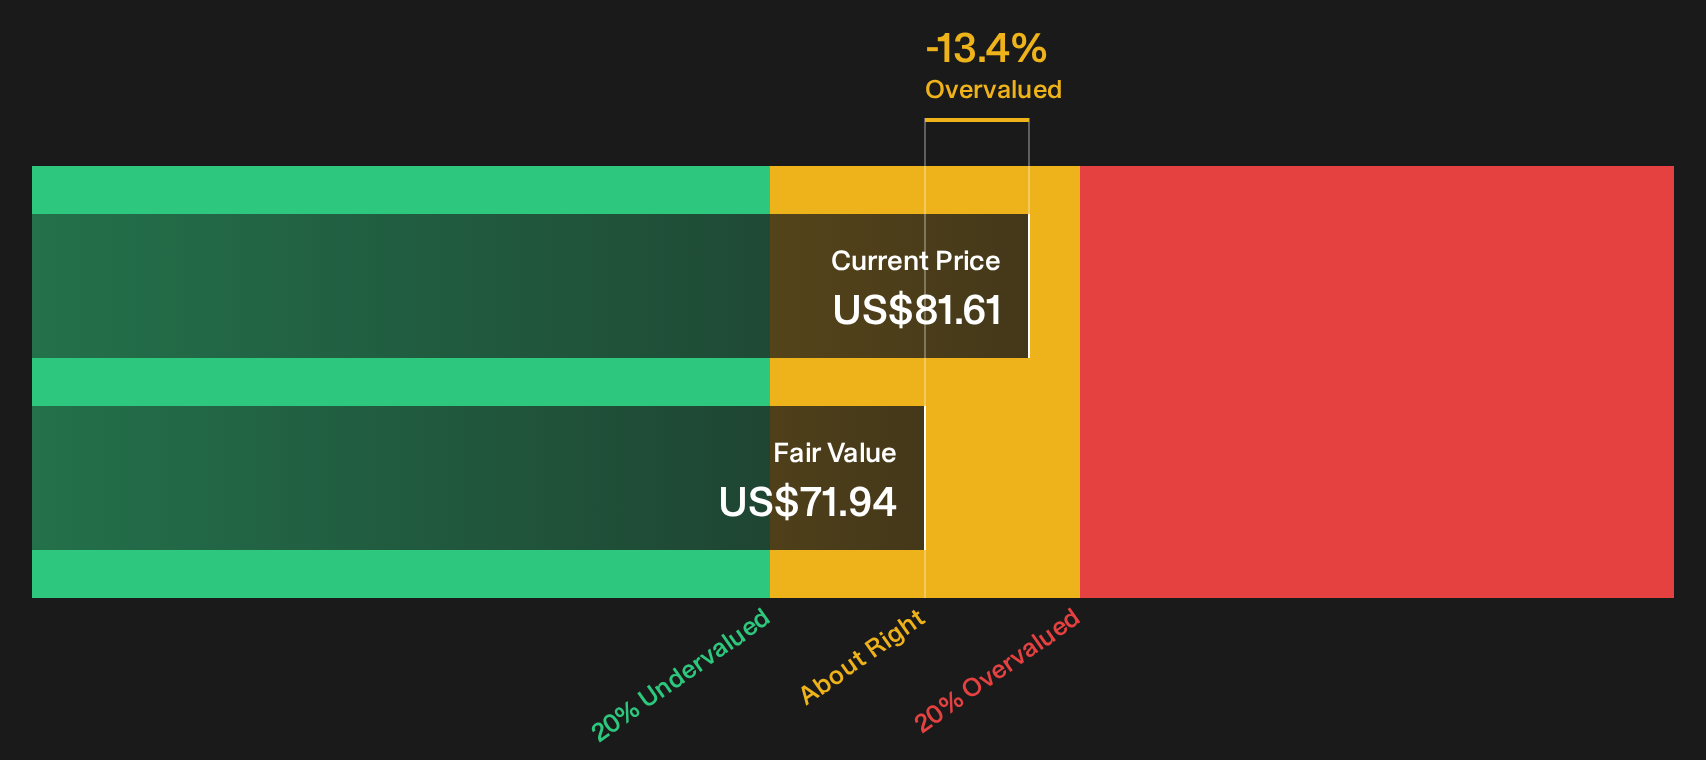
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Xcel Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The split between analyst optimism and cash flow caution sets the tone here. Move quickly, test the assumptions yourself, and weigh both the potential and the pitfalls with the help of 2 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond Xcel Energy?
Do not stop at a single ticker. Put a wider watchlist to work by scanning focused stock ideas that match the kind of risk and return mix you actually want.
- Target dependable cash generators by reviewing the 6 dividend fortresses that may suit investors who prize income and consistency from established businesses.
- Pursue value opportunities by running your eye over the 34 high quality undervalued stocks that combine quality fundamentals with prices that sit below their estimated worth.
- Dial back portfolio stress by scanning the 29 resilient stocks with low risk scores that prioritize balance sheet strength and steadier return profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com