


EN
Did Lindt's Fall Catch You Out? What Investors Missed
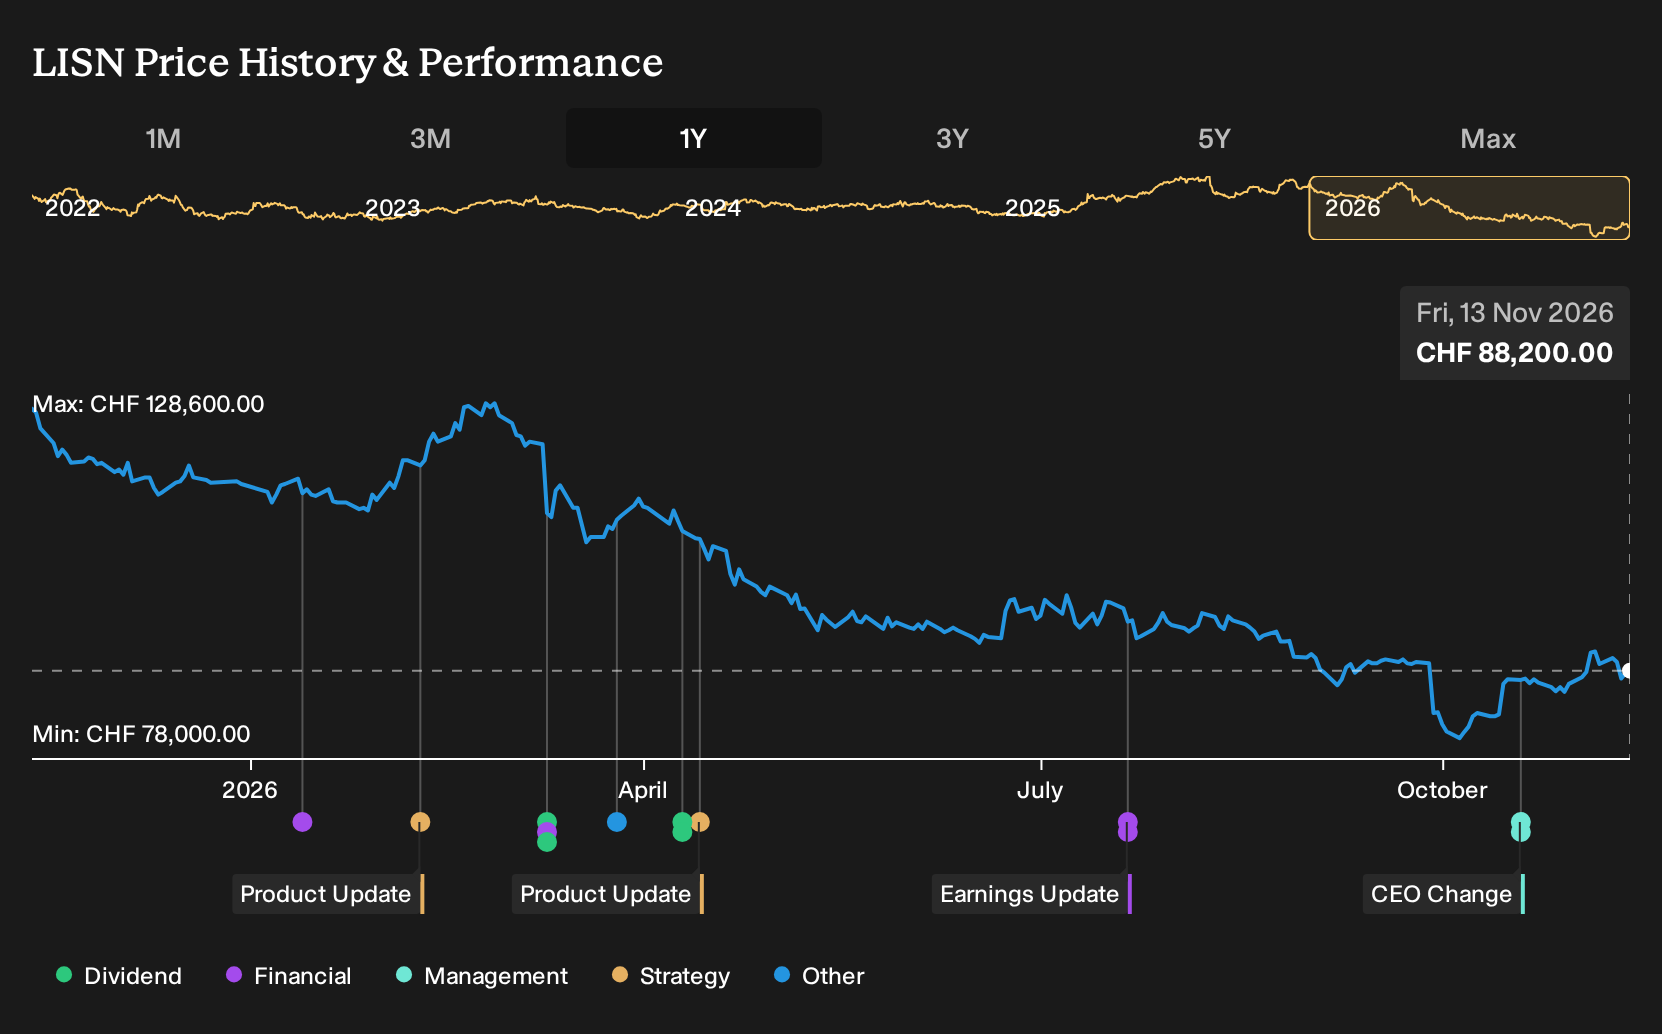
Chocoladefabriken Lindt & Sprüngli managed to squeeze slightly higher profit from almost flat revenue, yet shareholders saw a very different story in their portfolios. For Chocoladefabriken Lindt & Sprüngli shareholders, the loss over the past year was 28.1%, including dividends. If you had been weighing an investment on 13 November 2025, with bullish and cautious analyst views laid out, what clues were already on record that this kind of gap between business and share performance could open up?
If the move has made Chocoladefabriken Lindt & Sprüngli harder to judge, start where the gap is still open and scan 195 high quality undervalued stocks.
The Two Chocoladefabriken Lindt & Sprüngli Stories Investors Were Pricing
The shares cost CHF127,200 at the start of the period, and you had to choose which story about Chocoladefabriken Lindt & Sprüngli felt more realistic.
On the optimistic side, one camp saw a Fair Value of CHF147,000. This was a price implied by expectations of 8.7% yearly revenue growth supported by faster direct to consumer rollout in markets like Brazil, China, Saudi Arabia, and India.
A more cautious view put Fair Value at CHF120,706. This was tied to assumptions of 6.6% annual revenue growth and the risk that persistently high cocoa costs and changing health preferences could squeeze long term margins.
What The Evidence Did To The Chocoladefabriken Lindt & Sprüngli Argument
Lindt & Sprüngli reported revenue of CHF2,365.7m and net income of CHF192.2m in H1 2026, with a net margin of 8.1%. That combination of softer sales and slightly stronger profitability challenged the more optimistic growth story and aligned more closely with the cautious case that had already highlighted cost pressure and demand risk.
The useful takeaway for another stock is straightforward. When a thesis relies on premium pricing and expansion, monitor reported volume, top line and margin together to see which assumption is actually supported by the results over time.
What Chocoladefabriken Lindt & Sprüngli’s Lower Price Now Assumes
Chocoladefabriken Lindt & Sprüngli now trades at CHF88,200 after a 28.1% loss over the past year, and the bullish analyst Narrative on Simply Wall St places its Fair Value above that level.
The key question is whether retail expansion, premium positioning and cash generation can support the stronger earnings path this Narrative sketches. That is the assumption any buyer at today’s price would need to test.
"Bullish analysts expect Chocoladefabriken Lindt & Sprüngli to continue building on global retail and premium chocolate demand by using its wide geographic footprint and strong brand to turn current investments into higher earnings and cash generation over time."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Lindt
Chocoladefabriken Lindt & Sprüngli focuses on small treats and gifting moments. Your portfolio does not have to follow that pattern.
Consumers who buy premium chocolate also tend to choose familiar drinks and snacks. That spending can continue through ordinary weeks, not only holidays.
One global food and beverage group leans into that everyday habit. It gathers cash from sodas, chips and simple pantry staples.
Management there prioritises funding the business first, then maintaining a dividend, then repurchasing shares. That sequence of attention can feel very different from Lindt.
One Narrative has already put a figure on it. → Uncover the company trading 27% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com