


EN
Man Group Heads 3 British Dividend Stocks To Watch
High inflation in the US is keeping interest rates in focus, and that ripples across funding costs for British businesses and households. Reliable cash payouts start to feel more attractive when borrowing stays expensive and volatility lingers. Well covered UK dividend stocks yielding above 3% can offer a steadier stream of income. This article highlights three ideas from that universe that merit a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividend payers where the cash distributions look well covered, growing and stable. However, if you want the pick of this theme, these 4 dividend aristocrats stocks are the best of the best.
Man Group (LSE:EMG)
Man Group is a global investment manager whose fee income from long only and alternative strategies helps fund the >3% dividend focus of this screener. The business generates about $1.7b from its Investment Management segment and carries a market value of roughly £3.5b.
The analyst consensus Narrative on Simply Wall St argues that Man Group’s dividend appeal rests on a wider profit engine than headline yields suggest, with the core fee pool increasingly shaped by its credit platform and deeper institutional relationships.
"Continued build out of the credit and private credit platform, including over $60b of credit AUM and $17.6b in private credit by mid 2026 plus $4.9b of uncalled committed capital, gives scope for further deployment that can support fee revenue and diversify profit drivers."
The real tension for dividend reliability sits in how one hard to forecast shift in the fee mix ultimately plays through to margins.
That margin question is exactly what the full narrative for Man Group unpacks, showing how the fee mix, credit build out and capital deployment could be quietly rewiring Man Group’s earnings engine.

Kingfisher (LSE:KGF)
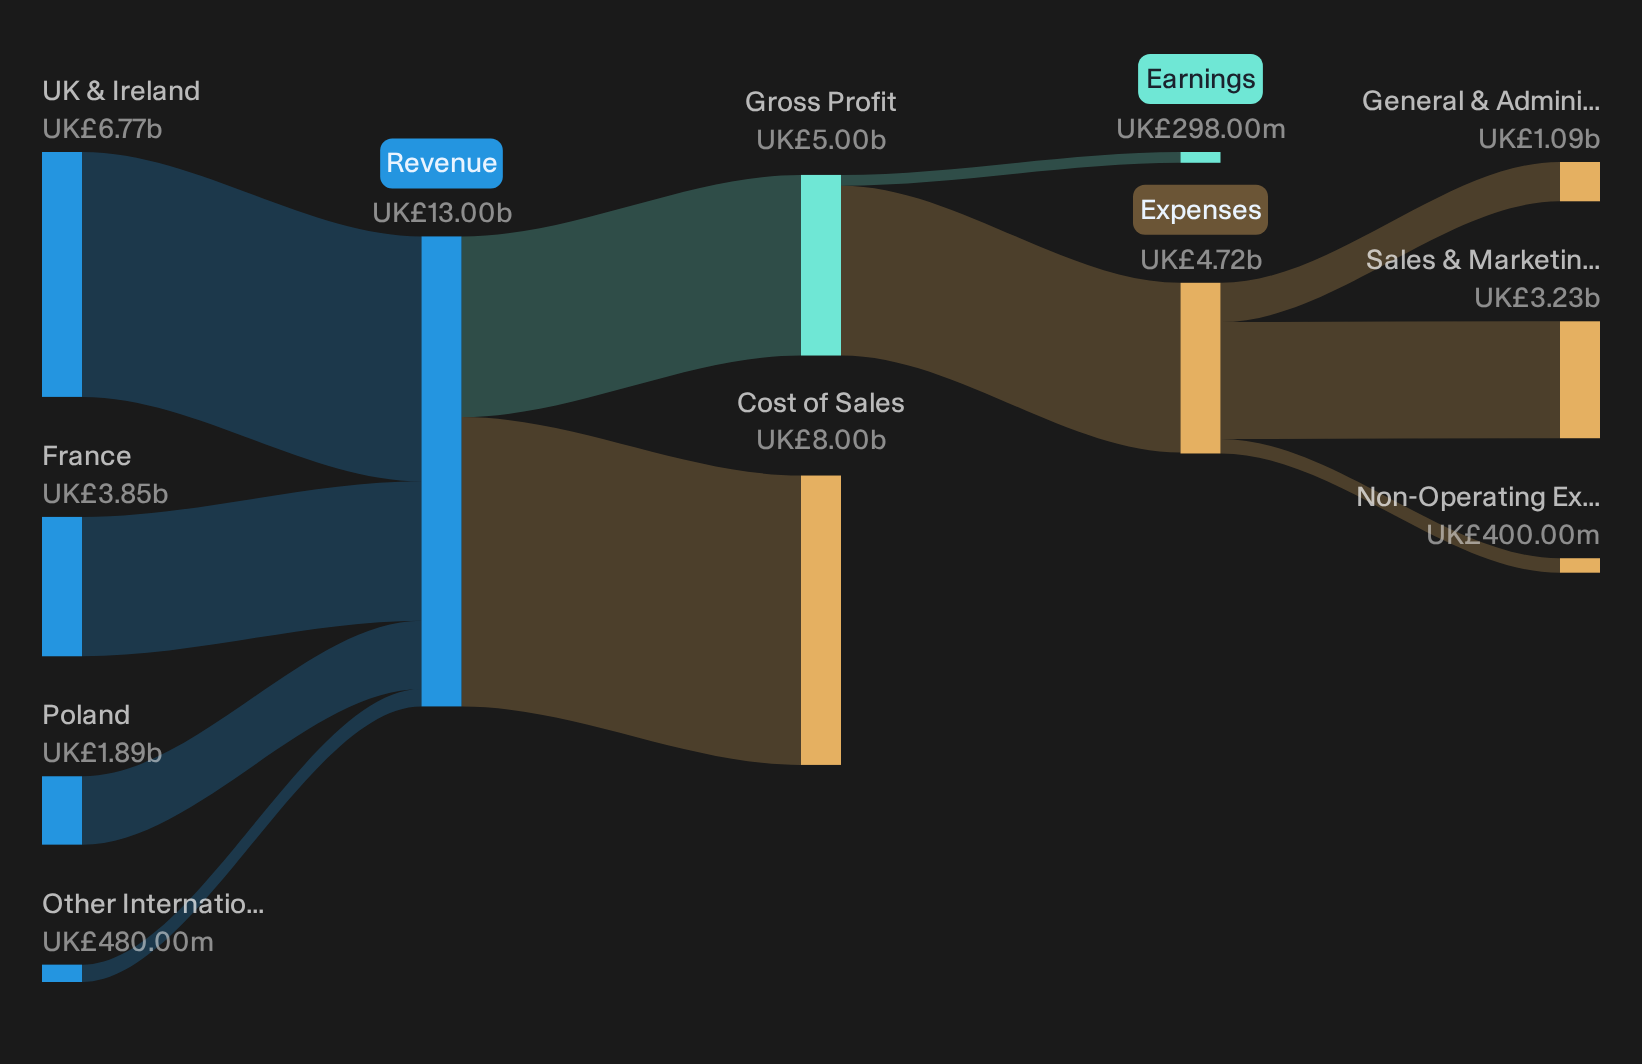
Kingfisher runs the B&Q, Screwfix, Castorama and Brico Dépôt chains, selling home improvement products and services that fit the Dividend Powerhouses theme through steady DIY and trade demand. It generated about £13.0b from this line and carries a market value near £6.2b.
Reliable DIY and trade spending is what ties Kingfisher to this dividend screen. The analyst consensus Narrative on Simply Wall St points to one area of the business that could quietly reshape how secure those cash distributions feel over time.
"Kingfisher's focus on growing higher value trade customers, with trade sales of £2.1b and trade penetration at 31% of group sales, supports the view that further mix shift towards trade can lift revenue density and margin per transaction."
What happens if that shift runs into one unseen pressure on profitability will be crucial for how dependable the payout really looks.
If that pressure is what worries you, the full narrative for Kingfisher explores how trade growth, pricing power and capital choices could reshape Kingfisher’s payout profile.
OSB Group (LSE:OSB)
OSB Group is a specialist mortgage lender whose retail deposit taking and mortgage franchise provides the cash flow link to the Dividend Powerhouses theme, with revenue of about £421.8 million from OneSavings Bank, £233.9 million from CCFS and a market value near £1.7b.
The income engine behind OSB Group’s 3%+ yield story is its specialist mortgage lending funded by sticky retail deposits. The analyst consensus Narrative on Simply Wall St highlights one upgrade program that could decide how dependable those cash payouts feel over time.
"OSB Group's ongoing cloud, data and AI transformation program is on time and on budget with about £85m still to be invested through 2027, while core operating costs already edged down 0.4% year on year in H1 2026 even as transformation expenses rose, which points to further potential improvement in cost to income ratios and net margins as more of the benefits flow through earnings."
What happens if one pressure on funding costs outpaces those efficiency gains will be central to how resilient OSB Group’s dividend story really is.
If that trade off between funding pressure and tech driven efficiency is what you are weighing up, the full narrative for OSB Group shows where OSB Group's earnings mix could be quietly accelerating.

Curious About What You Might Be Missing Next
Fresh opportunities can move from quiet to flying under the radar in a heartbeat. Scan these ideas before the crowd catches on and the best entry points drop. Act now.
- Target resilient cash generators by running the 4 dividend fortresses and see which payouts currently look built on sturdy balance sheets instead of fragile promises.
- Explore potential technology breakouts using the curated 53 AI infrastructure stocks and track businesses supplying the picks and shovels for AI’s growing hardware backbone.
- Look for early momentum in hard assets through the focused 33 elite gold producer stocks and compare producers where output, reserves and costs all line up more cleanly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com