


EN
How Strong Earnings At EOG Resources (EOG) Has Changed Its Investment Story
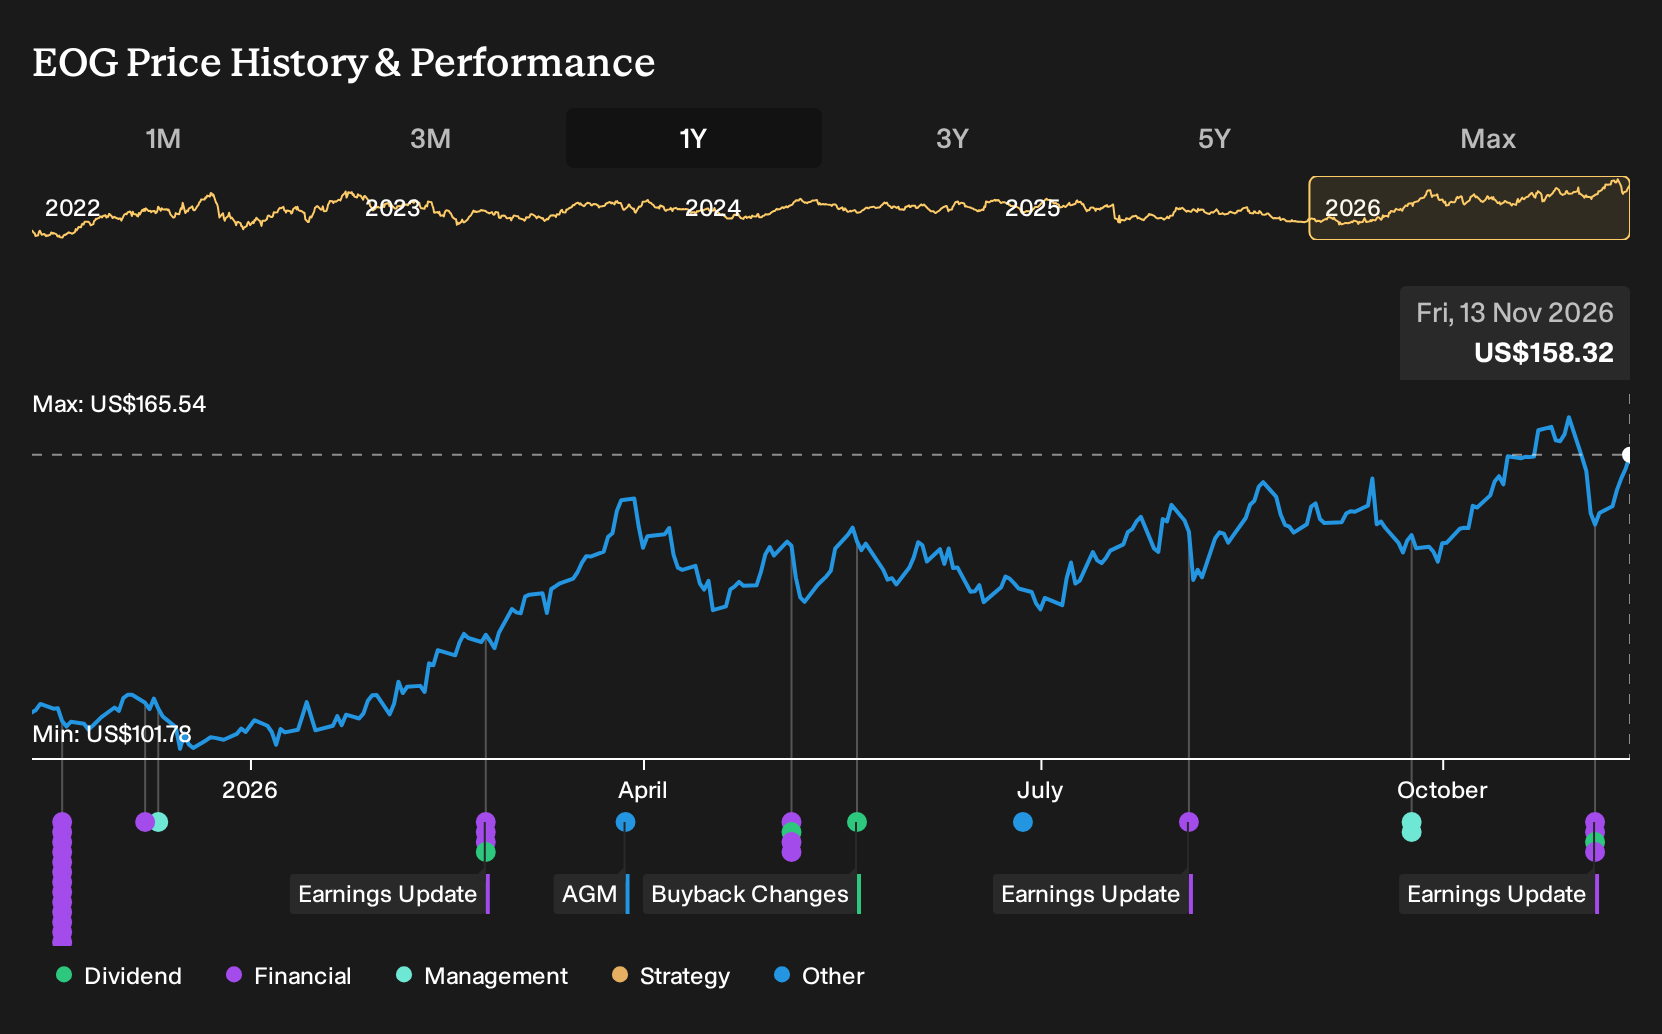
- EOG Resources reported third quarter 2026 results with revenue of US$8.549b and net income of US$2.781b, supported by higher production volumes and EPS above US$5 on both a basic and diluted basis.
- Operational tweaks such as longer laterals in the Eagle Ford, lower well costs, and an 8% uplift to the regular dividend highlight EOG Resources focusing on capital efficiency and cash returns at the same time.
- We will now see how EOG Resources' investment narrative could be influenced by its reported earnings and focus on production efficiency.
Scan a curated set of oil and gas producers that pair capital discipline with production growth stories similar to EOG Resources through the list of solid balance sheet and fundamentals (24 results).
EOG Resources Investment Narrative Recap
EOG Resources appeals to shareholders who think efficient drilling, disciplined spending and high quality acreage can keep supporting strong cash generation even when commodity prices move around. The analyst consensus Narrative on Simply Wall St focuses on converting low cost inventory into profitable volumes. The latest quarter, with higher revenue, earnings and production, indicates that execution is tight today.
The key short term consideration is whether EOG Resources can keep translating production efficiency into resilient margins as activity ramps across plays such as the Eagle Ford and Utica. The main operational risk is that heavy exposure to oil and gas leaves results sensitive to any faster shift toward renewables or weaker long term hydrocarbon demand.
The 8% increase in the regular dividend to US$1.10 per share, or US$4.40 on an indicated annual basis, is the announcement most closely tied to this earnings update. It comes alongside a period where earnings grew 48% over the past year and net profit margins improved, which indicates that management is comfortable sharing more of current cash generation with investors.
For you as a shareholder, that higher payout makes dividend sustainability a more important point to monitor, especially given the previously unstable track record flagged in the risk checks. It also raises the bar on future execution, since any prolonged pressure on prices, higher cost emerging projects or weaker free cash flow could make maintaining that level of cash returns more difficult.
EOG Resources' narrative references analysts expecting revenue to remain fairly flat and projects US$26.8b in revenue and US$7.2b in earnings by 2029. That consensus implies roughly stable top line over the forecast window and an earnings increase of about US$0.3b from US$6.9b today.
Uncover why EOG Resources' fair value indicates a 5% potential upside to its current price. This discount could close sooner than many expect.
Exploring Other Perspectives
For a very different angle, some of the most optimistic analysts focus on EOG Resources using its higher leverage after the Encino deal as a springboard rather than a constraint. Before this earnings release, that group was penciling in revenue of about US$29.9b and earnings of roughly US$8.5b by 2029. Those forecasts sit well above the consensus view of US$26.8b of sales and US$7.2b of profit. You can treat this quarter’s production and dividend news as fresh evidence to consider which camp you lean toward and to explore how both narratives might shift as new data becomes available.
Explore 3 other EOG Resources fair value estimates, including one that suggests potential upside of as much as 97% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your EOG Resources research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for EOG Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EOG Resources' overall financial health at a glance.
Looking for more investment ideas beyond EOG Resources?
If this earnings story has sharpened your view on EOG Resources, use that same lens to scan other opportunities that match your risk tolerance and return goals through the Simply Wall St Screener.
- For investors hunting for potential mispricing, start with companies that combine solid fundamentals with room for a re rating by reviewing the 34 high quality undervalued stocks.
- If dependable income is a priority, filter for businesses with robust payouts and balance sheets that support them over time using the 6 dividend fortresses.
- When capital preservation matters most, focus on businesses with stronger financial resilience and steadier risk profiles through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com