


EN
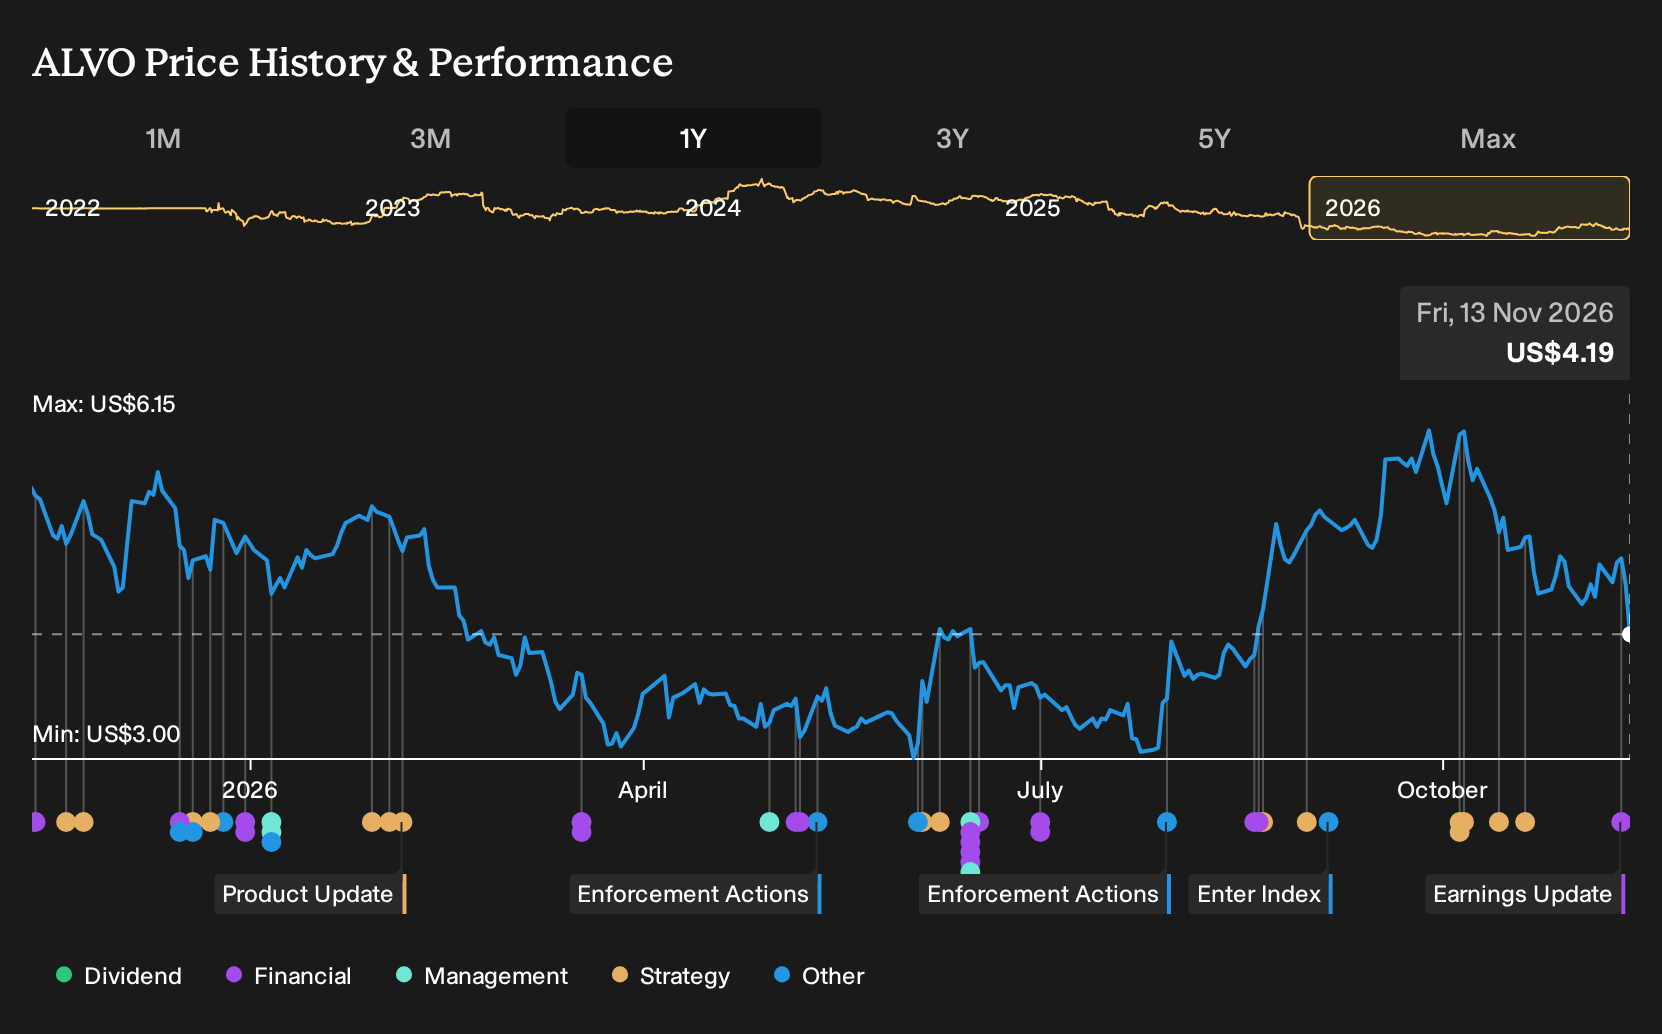
Why Alvotech (ALVO) Is Down 10.3% And What's Next
- Alvotech reported results for the nine months ended September 30, 2026, moving from net income of US$136.47 million a year earlier to a net loss of US$140.66 million, with basic and diluted loss per share from continuing operations of US$0.45.
- The swing from profit to loss highlights pressure on Alvotech's cost structure and execution, which may affect how investors view the reliability of its biosimilar-driven earnings profile.
- Investors may now reassess how Alvotech's shift from net income to net loss could influence the broader investment narrative around its pipeline.
Compare Alvotech's earnings swing with peers facing similar pressures by scanning our curated list of 29 resilient stocks with low risk scores that may offer steadier cash flows and cleaner balance sheets.
Alvotech Investment Narrative Recap
For an investor to stay with Alvotech, the belief is that a focused biosimilar platform can eventually turn scale into consistent cash generation. The move from net income of US$136.47 million to a loss of US$140.66 million puts execution under the microscope. The near term story now hinges on whether manufacturing upgrades and supply reliability translate into steadier revenue and less volatile earnings.
The analyst consensus Narrative on Simply Wall St leans heavily on upcoming biosimilar launches and an expanded production footprint as key near term drivers. That view meets a clear risk. The recent loss, combined with less than one year of cash runway and higher interest costs, increases pressure on Alvotech to hit its back half weighted 2026 revenue and EBITDA guidance without further disruption.
The most relevant prior context comes from Alvotech reaffirming 2026 guidance for revenue in the range of US$650 million to US$700 million and adjusted EBITDA in the range of US$180 million to US$220 million after reporting a 31% year on year decline in first half 2026 revenue to US$212 million. The latest nine month loss now sits against that ambitious framework and makes execution on product launches and supply recovery more important.
Those earlier comments on targets, together with expectations for future earnings growth, framed a thesis that operational hiccups would be temporary. The new figures challenge that assumption and make every upcoming catalyst, from scaling the upgraded Reykjavik facility to delivering limited competition biosimilars such as Simponi or Entyvio, carry more weight. For you as a shareholder, the question is how comfortable you are with that tighter margin for error around funding, leverage and delivery against guidance.
Alvotech's narrative projects forecast revenue of US$984.0 million and forecast earnings of US$202.4 million by 2029. That profile rests on analysts modeling 25.8% yearly revenue growth and an earnings move of about US$382 million from current earnings of a US$179.6 million loss.
Uncover why Alvotech's fair value indicates a 72% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One optimistic twist in the alternate Alvotech story is the weight placed on direct U.S. commercialization as a catalyst. The most bullish analysts had been projecting revenue of about US$1.2b and earnings of roughly US$334.9 million by 2029. That is a far brighter path than consensus, and these new losses may push you to compare both narratives more closely.
Explore 4 other Alvotech fair value estimates, including one that suggests as much as 703% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Alvotech research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alvotech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alvotech's overall financial health at a glance.
Looking for more Alvotech sized investment ideas?
If Alvotech has you rethinking risk, return and balance sheet strength, it can help to widen the lens and compare it with other businesses that match your preferred profile.
- For investors who want potential upside without ignoring quality, scan a curated pool of under-the-radar opportunities through the 19 high quality undiscovered gems.
- If capital protection and financial resilience sit at the top of your checklist, narrow your focus to companies screened for sturdier funding and conservative leverage using the 29 resilient stocks with low risk scores.
- Income seekers who care about both yield and staying power can zero in on businesses with stronger payout profiles through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com