


EN
BlackRock (BLK), Why Is It Back In The Spotlight?
BlackRock (BLK) is back in focus after reporting quarterly earnings and revenue above estimates, supported by record assets under management, strong net inflows across products, higher operating income, and an ongoing share repurchase program.
At a share price of $1,222.91, BlackRock has seen momentum build, with a 7.8% 1 month share price return and a 12.7% year to date move that lines up with recent earnings beats. The 1 year total shareholder return of 18.06% sits alongside an 82.38% 3 year and 50.89% 5 year total shareholder return profile that long term holders will likely focus on more than the latest quarterly headlines.
Scan for other asset managers showing similar momentum and fund flow strength with our curated list of 34 high quality undervalued stocks, which combines solid fundamentals with market interest.
BlackRock’s sharp run after earnings can look like pure enthusiasm or a cleaner read on a business pulling in record assets and inflows. Which story does the current valuation tell?
Most Popular Narrative: 18% Overvalued
On the narrative view, BlackRock’s fair value sits at $1,035.85, which is below the recent $1,222.91 close and points to a stretched price, according to LunaRodas, a Simply Wall St Community investor who wrote the narrative and tracks how management actions line up with prior promises.
The AI buildout used to be one growth driver among several, discussed mostly in the context of GIP and HPS integration. Now it is the organizing frame for the entire call. Fink opens with a claim rendered almost cinematically: “For the first time in my career, and that’s 50 years of a career, I’m seeing genuine shortages of capital.” He draws a direct historical analogy to the 1980s mortgage-backed securities market, invoking Fannie Mae and Freddie Mac pooling illiquid loans before data and performance history made them tradable. The pitch is that compute capacity is “now following a similar path,” and BlackRock intends to be “the center of it.”
See why 1 investors see BlackRock as 18% overvalued.
Result: Fair Value of $1,035.85 (OVERVALUED)
Still, the BlackRock narrative could be knocked off course if AI infrastructure enthusiasm cools, or if previously spotlighted areas like tokenization and insurance flows keep fading from management’s script.
Find out about the key risks to this BlackRock narrative.
Another View On BlackRock’s Valuation
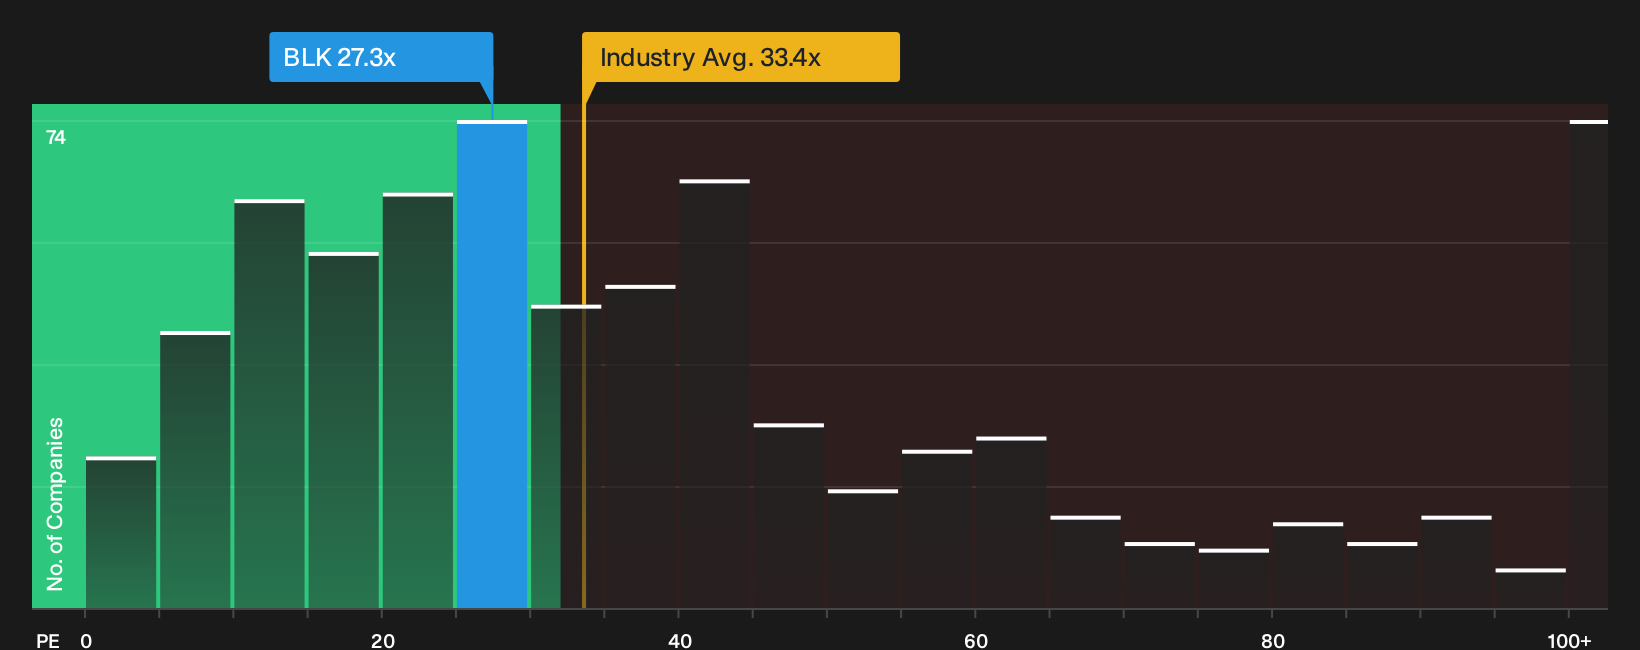
The narrative-based fair value pegs BlackRock at $1,035.85, which screens as 18% above that level at $1,222.91. On earnings multiples, the picture shifts. The stock trades on a 27.3x P/E, which is lower than the US Capital Markets industry at 33.4x, yet higher than both peers at 21x and its own fair ratio of 19.7x. That gap implies investors are paying a premium multiple that could compress if sentiment cools, or persist if BlackRock keeps justifying a richer tag.
For a closer look at what these earnings multiples signal about risk and room for error, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all feels finely balanced, use that uncertainty as a prompt to move fast, review the full picture, and pressure test BlackRock against your own thesis. The easiest way to weigh both the upside and the concerns is to size up the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BlackRock?
If BlackRock has sharpened your focus, do not stop here. Broaden your watchlist with fresh ideas that match how you like to balance risk and quality.
- Target resilient compounding potential by scanning a 6 dividend fortresses that could help anchor your portfolio with recurring income.
- Hunt for mispriced quality by running through a 19 high quality undiscovered gems that many investors may not yet be watching closely.
- Prioritise peace of mind by filtering for a 29 resilient stocks with low risk scores that could help you avoid fragile balance sheets and fragile business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com