


EN
3 Australian Growth Stocks To Watch In November 2026
The US Federal Reserve has signalled that inflation still runs too hot and that it has more work to do. That keeps borrowing costs elevated and creates a tough backdrop for weaker Australian businesses. It also pushes attention toward local companies that already generate strong growth while carrying sturdy balance sheets. This article highlights three high growth Australian stocks from our screener that fit that description.
The three stocks in this article are just a sample, and the full high growth screen surfaced 32 more Australian companies with similarly compelling stories that are not covered here. To identify and analyze the ideas that best fit your own approach, head straight into the Best high growth potential screener
Minerals 260 (ASX:MI6)
Overview: Minerals 260 is an Australian explorer focused on the Bullabulling Gold Project and other early stage gold and base metal targets.
Market Cap: A$1.98b
Minerals 260 plugs into the Best high growth potential theme through Bullabulling. Analysts expect revenue and earnings to ramp quickly from a newly profitable base, supported by a 22.9% return on equity and strong growth forecasts. The optimism in a 23.7x P/E and ongoing capital raisings leaves a lot riding on how one future funding pressure plays out.
With so much hinging on that funding path, review the 3 key rewards and 3 important warning signs (2 are major!) to see where Minerals 260’s upside and pressure points may be building.

Ramelius Resources (ASX:RMS)
Overview: Ramelius Resources is an Australian gold producer built around the Mt Magnet mining hub, with exploration projects feeding future production growth.
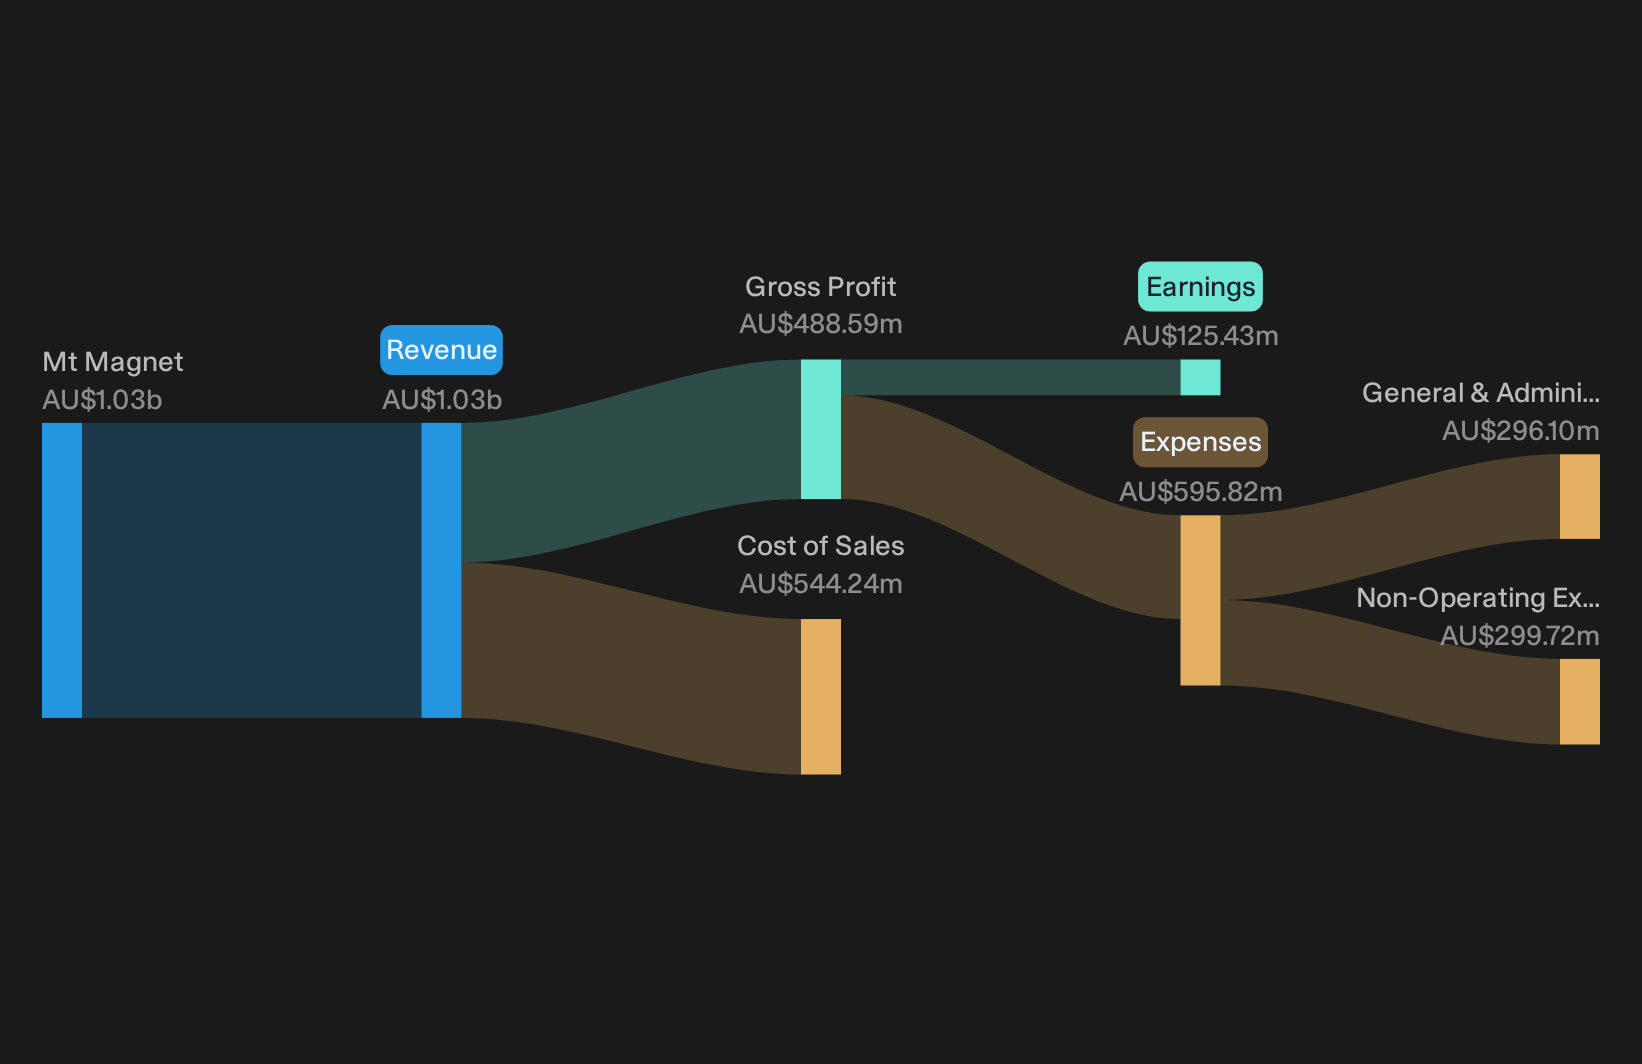
Operations: The group generates A$1.03b in revenue from its Mt Magnet segment, tying future earnings closely to this Western Australian gold hub.
Market Cap: A$7.0b
Ramelius Resources matters for a high growth screen because Mt Magnet gives analysts a concrete production pathway, and Robbo, a Simply Wall St Community investor who wrote the Narrative, argues that the balance sheet and project pipeline give that growth real staying power.
"Ramelius maintains very low debt levels and a substantial pipeline of projects."
The real swing factor for Ramelius Resources is what happens to profitability if one key cost and pricing assumption shifts over the next few years.
If that single swing factor has your attention, read the full narrative for Ramelius Resources to understand how Ramelius Resources’ growth story could either accelerate or stall in different scenarios.
Lynas Rare Earths (ASX:LYC)
Overview: Lynas Rare Earths mines and processes rare earth materials from its Mt Weld hub to supply magnets for electric vehicles and wind turbines.
Operations: Lynas Rare Earths currently generates about A$977.9 million in revenue from its Rare Earth Operations segment.
Market Cap: A$13.3b
Lynas Rare Earths fits this high growth theme because its Mt Weld mine and downstream plants feed directly into the rare earth materials that power electric motors and turbines. The analyst consensus Narrative on Simply Wall St argues that the enlarged resource base and downstream push could reshape its growth profile.
"Advancing the acquisition of the Caldeira ionic clay project in Brazil, which roughly doubles the mineral resource base and adds significant NdPr and DyTb feedstock, positions Lynas Rare Earths to increase future ex China supply of both light and heavy rare earths."
What happens to Lynas Rare Earths' rare earth pricing power if one key assumption on long term demand growth starts to fray?
If that pricing risk matters to you, read the full narrative for Lynas Rare Earths to see how Lynas Rare Earths could still accelerate if sentiment or demand assumptions shift.

Seeking Alternatives Before The Crowd Moves
Fresh ideas rarely stay quiet for long. Once momentum hits, prices move and the easy entry points start dropping away. Scan these under the radar picks now and review them early.
- Track cash rich compounders before they get fully priced by screening a curated list of solid balance sheet and fundamentals (12 results) that can handle pressure when conditions shift.
- Assess potential income opportunities from companies that investors watch for reliability by scanning a curated 4 dividend fortresses while yields and coverage still line up.
- Prepare for possible metal price swings by reviewing a focused 33 elite gold producer stocks that filters for producers with scale and operating leverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com