


EN
What Rengo (TSE:3941)'s Raised Interim Guidance Means For Shareholders
- Rengo Co., Ltd. reported half year sales of JPY 554,141 million and net income of JPY 20,850 million, raised interim guidance, confirmed new full year targets to March 2027, announced a higher second quarter dividend, and held a board meeting on a planned absorption type merger of a wholly owned subsidiary.
- The business linked stronger packaging related performance and advance demand for materials tied to Middle East supply chain risks with higher interim forecasts. It kept full year guidance unchanged due to expected raw material cost pressure and softness in the European automotive sector.
- The focus now turns to how Rengo's upgraded interim guidance, supported by packaging demand, may influence the broader investment narrative for the stock.
Scan how Rengo's upgraded guidance and higher dividend compare with packaging peers by reviewing our curated list of 18 high quality undervalued stocks that may be priced for a breakout.
What Is Rengo's Investment Narrative?
To own Rengo, you need to be comfortable with a packaging group that depends on steady box demand, disciplined pricing and heavy investment in paperboard and machinery. The raised half year guidance and the confirmed full year targets to March 2027 indicate that management is leaning on flexible packaging pricing power and short term material stocking, while still treating raw material costs and weak European auto demand as real constraints on the near term story.
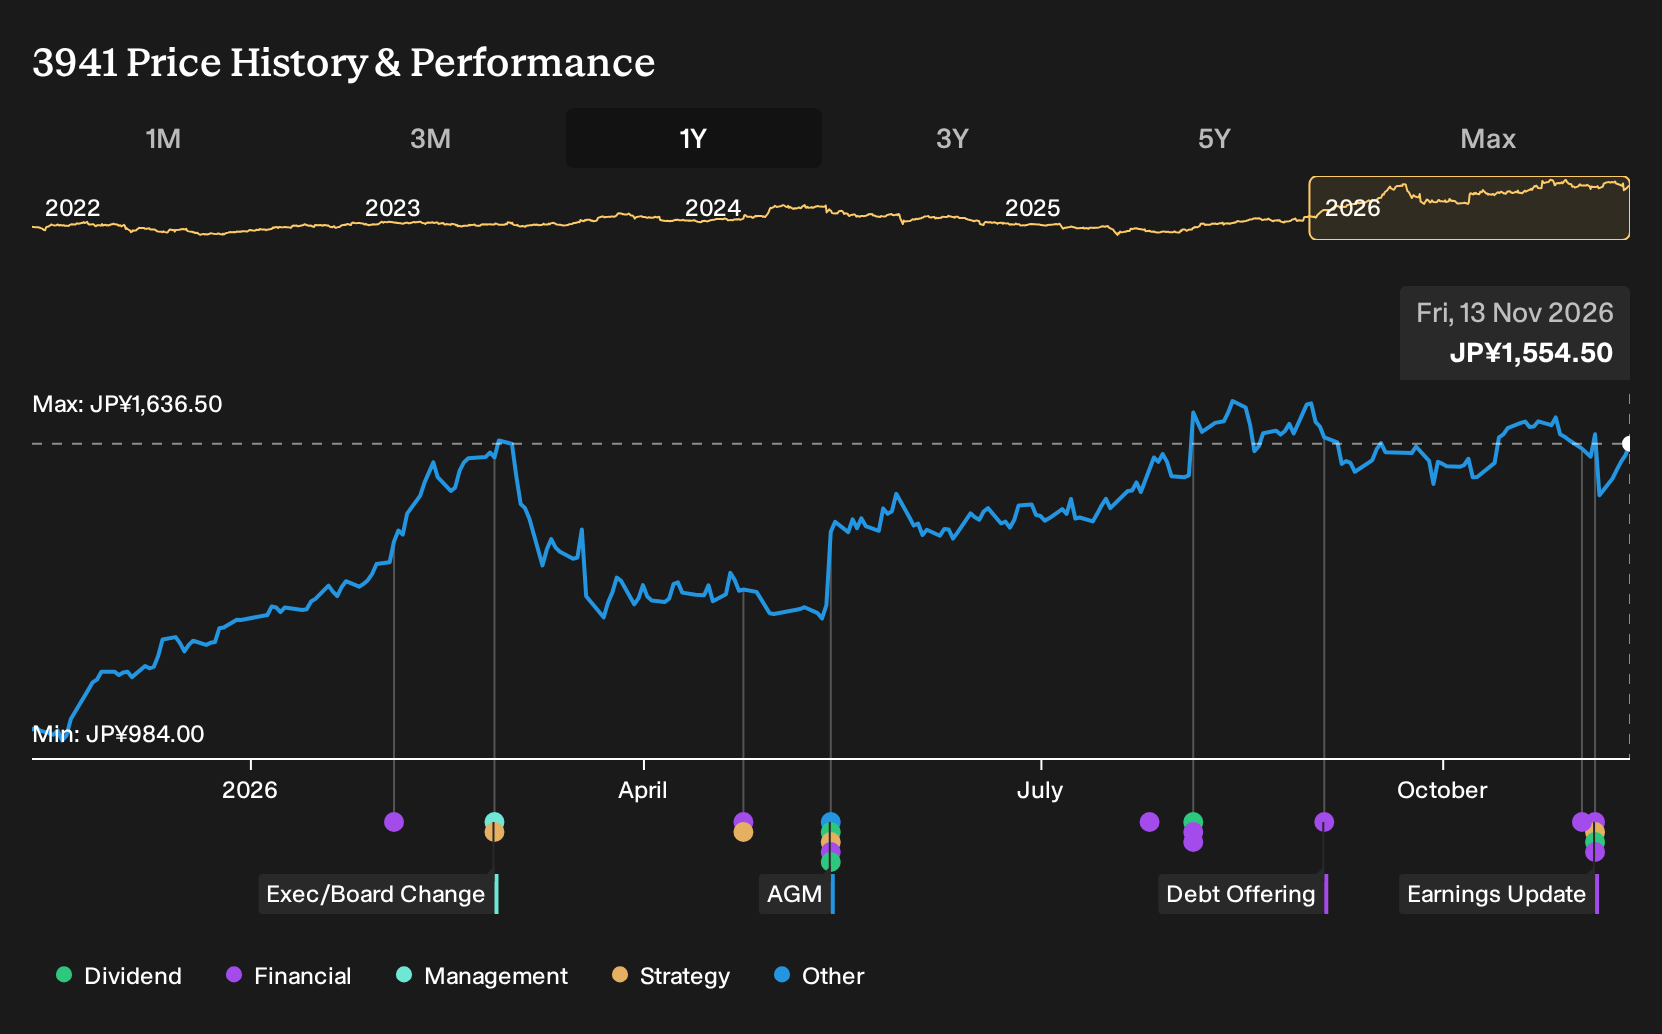
The higher second quarter dividend and the planned absorption type merger of a wholly owned subsidiary both point to a board trying to tighten capital allocation. Earnings growth has recently accelerated, net margins are higher than a year ago and the share price has climbed 60.1% over 12 months. At the same time, debt coverage and dividend cash support remain key pressure points.
That said, once you stack Rengo's upgraded guidance, higher payout and recent share price run against one uncomfortable funding detail, the picture becomes more complex.
There's only one way to know the right time to buy, sell or hold Rengo. Head to Simply Wall St's company report for the latest analysis of Rengo's Fair Value.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rengo research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rengo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rengo's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rengo?
Rengo's story is only one piece of your portfolio puzzle. If you want to pressure test your thinking and spot other opportunities with different risk and income profiles, the Simply Wall St Screener can help you scan the market using the same data driven lens.
- For investors who like to pair income with resilience, filter for companies that aim to defend their payouts with robust cash generation and balance sheets by reviewing our 29 dividend fortresses.
- If you want businesses where financial strength and funding flexibility take priority, narrow your search using a list of solid balance sheet and fundamentals (24 results) to see which tickers keep leverage in check.
- To widen your watchlist beyond well known stocks, use a 72 high quality undiscovered gems that surfaces under the radar companies with strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com