


EN
Will 5 Gig Fiber Launch Change T Mobile's Narrative For T Mobile (TMUS)
- T-Mobile US recently launched a 5 Gig fiber plan with a 10-year price guarantee and showcased advanced 5G capabilities at the Las Vegas Formula 1 event, while also updating investors on a stronger 2026 profitability and free cash flow outlook.
- The combination of high-capacity fiber, real-time 5G solutions for a complex live event and a more confident long-term financial outlook highlights how T-Mobile US is trying to deepen its broadband reach and monetize its network investments across multiple use cases.
- This article examines how T-Mobile US's faster 5 Gig fiber launch could shape the existing investment narrative around broadband expansion.
T-Mobile US Investment Narrative Recap
To own T-Mobile US, you need to believe the analyst consensus Narrative on Simply Wall St that the business can keep turning its dense 5G footprint and broadband build into higher value postpaid and home internet revenue while holding churn in check. The short term swing factor is execution on rate plan modernization without pushing more customers away as higher bills flow through.
The biggest risk still sits with customer sensitivity to pricing and promotions. Aggressive offers from rival carriers and cable operators could force T-Mobile US to either spend more on incentives or accept slower account additions. The recent F1 and fiber headlines do not significantly change that near term equation.
The Fiber 5 Gig launch is the clearest link to those broadband catalysts. It shows T-Mobile US leaning into higher speed tiers that tie directly to the thesis of scaling 5G broadband and fiber to support service revenue. The 10 year price guarantee, unlimited data and included equipment keep the pitch simple for households weighing cable and rival telecom bundles.
For you as a shareholder, the question is less about this single plan and more about repeatable execution. Uptake of fiber and fixed wireless will feed into the higher 2030 broadband targets and free cash flow ambitions that analysts are watching. The main operational risk is that heavy capital needs and high debt tighten flexibility if adoption of these offers disappoints.
T-Mobile US' story assumes revenue of US$105.5b and earnings of US$18.2b by 2029, built on 4.0% yearly revenue growth and an earnings increase of about US$6.9b from US$11.3b today.
Discover why T-Mobile US' fair value points to a 34% potential upside from its current price, which may materialize sooner than many investors anticipate.
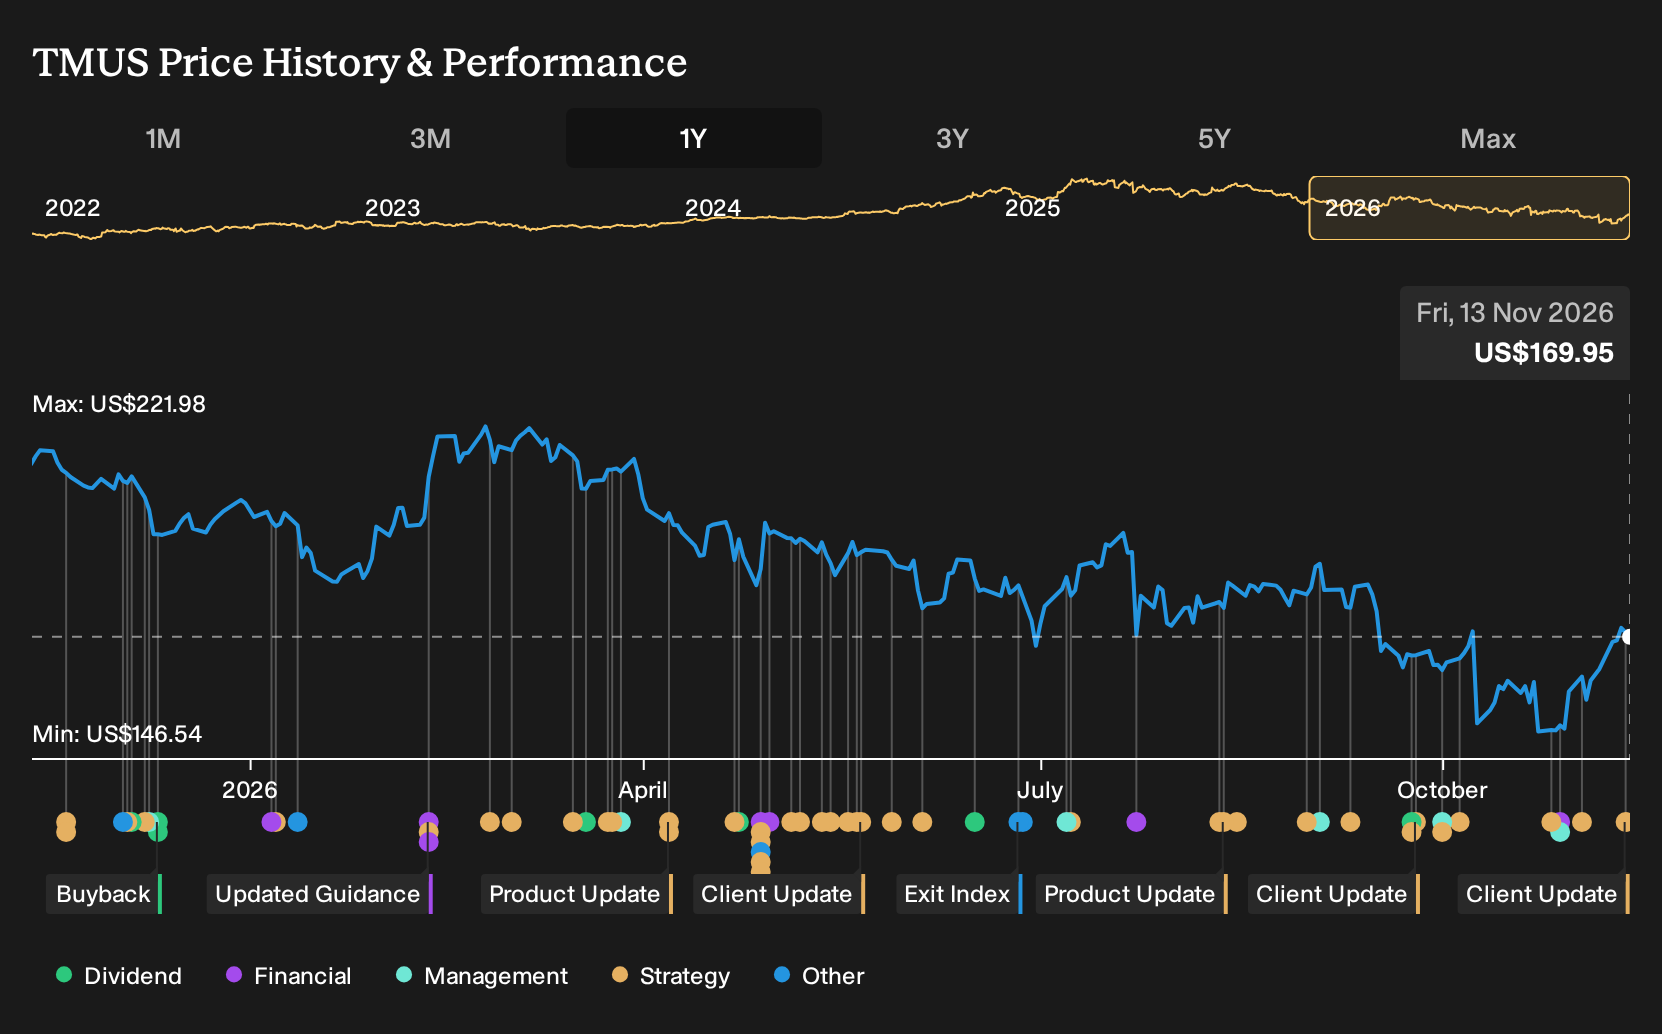
Exploring Other Perspectives
Some of the most optimistic analysts frame the Formula 1 and 5 Gig fiber news as potential proof points for a much bigger broadband and enterprise story. Before these headlines, the bullish camp was already penciling in about US$107.7b of revenue and US$22.0b of earnings by 2029. You can compare that to the more cautious consensus view and decide which version of T-Mobile US feels closer to your own expectations, knowing both narratives may shift as this kind of event driven execution plays out.
Explore 2 other T-Mobile US fair value estimates, including one that suggests as much as 237% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your T-Mobile US research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T-Mobile US. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T-Mobile US' overall financial health at a glance.
Looking for more investment ideas beyond T-Mobile US?
If T-Mobile US has sharpened your interest in connectivity and cash generative business models, it can be useful to widen the lens and compare it with other opportunities that share similar financial strengths or income profiles.
- For investors who care most about durable income streams, consider a shortlist of companies offering stronger yield profiles through 6 dividend fortresses.
- If capital preservation and steadier risk characteristics are higher on your list, you may want to focus on businesses screened for resilience using the 29 resilient stocks with low risk scores.
- When balance sheet strength matters more than headline stories, start with a curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com