


EN
China Mobile (SEHK:941) Stock Looks In Line With Earnings Strength
China Mobile has delivered a powerful long term share price run, yet the recent pullback raises a fresh question about whether today's valuation still lines up with its earnings strength. For anyone looking at telecoms as an income and stability anchor in a portfolio, the key puzzle is how much of China Mobile's current price can be pinned to its profit power rather than sentiment.
- Over the past 5 years the stock has returned 141.9%. This now puts a lot of weight on whether those gains rest on a durable earnings base.
- The group runs a capital intensive network business. Cash flow, depreciation and ongoing investment all feed directly into how much of its earnings can realistically be paid out or reinvested.
- The analysts covering China Mobile have run their own numbers. See what analysts think China Mobile's shares could be worth.
The stock's next move may depend on whether China Mobile's current price looks well supported by its earnings when set against a Fair Ratio benchmark.
If you want a second reference point while you assess China Mobile against its earnings power, you can apply the same approach to a broader set of companies using the 195 high quality undervalued stocks.
Does China Mobile Look Fairly Valued on Earnings?
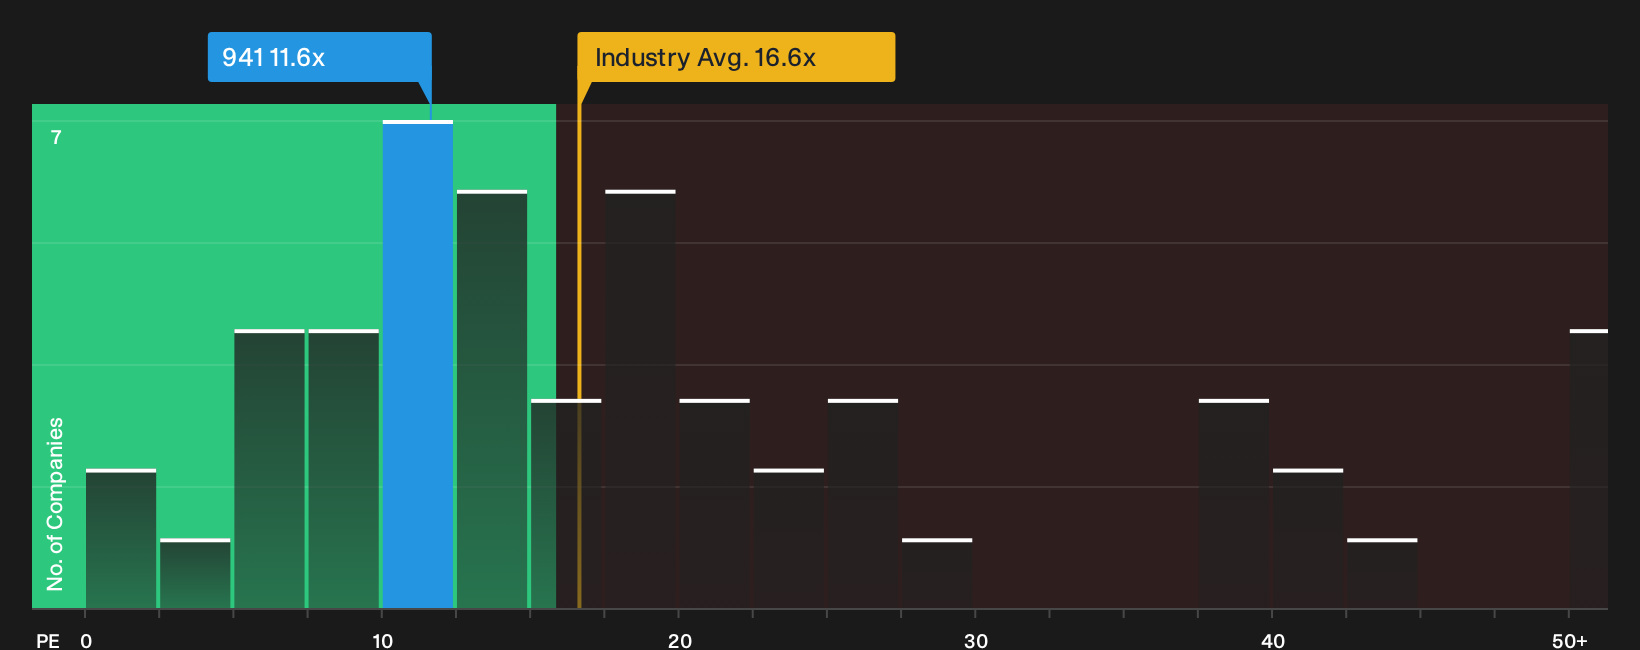
The P/E ratio suits China Mobile because investors often look at it as an earnings and dividend workhorse rather than a high growth story. On this measure, the stock trades on about 11.6x earnings, which sits below the wireless telecom industry average of roughly 14.8x and also under the broader peer group at about 24.3x. That marks a clear gap between what the market currently pays for China Mobile's profits and what it pays for telecom earnings elsewhere.
The tailored Fair Ratio, which blends factors such as the group's margins, growth profile, market size and risk, points to a level close to where China Mobile now trades. The current P/E sits only slightly above that modelled anchor, so the share price does not screen as especially expensive or particularly cheap on this single metric. Anyone weighing the stock now is really judging whether the quality and resilience of its earnings justify a multiple that is a discount to sector averages but broadly aligned with its own Fair Ratio. Explore the numbers behind China Mobile's P/E valuation.
The China Mobile Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation question on China Mobile leaves off. On the Community page, they spell out which paths for future growth, margins and earnings would need to unfold for the shares to look meaningfully higher or lower than they do today. Each scenario links a potential fair value to a clear storyline about China Mobile's possible catalysts and risks so you can track over time which version of events seems to be emerging.
One of the top community narratives on China Mobile: 33% undervalued
According to kapirey, an investor in the Simply Wall St Community, China Mobile is slowly reshaping itself around digital infrastructure and AI services.
"While traditional telecom services show low growth, emerging segments (cloud, AI, computing) are becoming the primary drivers of long-term value creation..."
Discover why this Narrative puts China Mobile at 33% undervalued.
One more piece to weigh before acting on China Mobile's valuation
Before you lean too hard on today’s multiples and narratives, it is worth checking how professional analysts currently map China Mobile’s earnings path over the next few years and how that aligns with the market price. Explore where analysts expect China Mobile to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com