


EN
Learn Why The Bull Case For Ciena Stock Could Change Following December Earnings Report
- Ciena heads into its December 10 fiscal fourth quarter and year-end earnings release with management focused on ambitious margin improvement targets through 2029.
- The business now leans heavily on a small group of hyperscaler customers, so any slowdown in AI driven optical demand could affect how efficiently it converts backlog into revenue and cash.
- We will look at how Ciena's investment narrative compares with these margin ambitions and its reliance on hyperscalers ahead of the earnings update.
Scan how Ciena's setup compares with other potential beneficiaries of the same AI infrastructure build out by reviewing our hand picked 53 AI infrastructure stocks.
Ciena Investment Narrative Recap
To own Ciena, you need to believe that AI driven optical demand and data center connectivity stay robust enough for the firm to work through its large backlog while moving margins toward management’s 2029 targets. The near term hinge is simple: can Ciena show on December 10 that component supply and deliveries are lining up with those ambitions?
The key risk sits on the customer side. Around half of Ciena’s sales now come from hyperscalers, so any slowdown in their orders would matter more than short term share price swings, including the recent pullback. If the earnings update only confirms known issues in supply or demand, the impact may be limited.
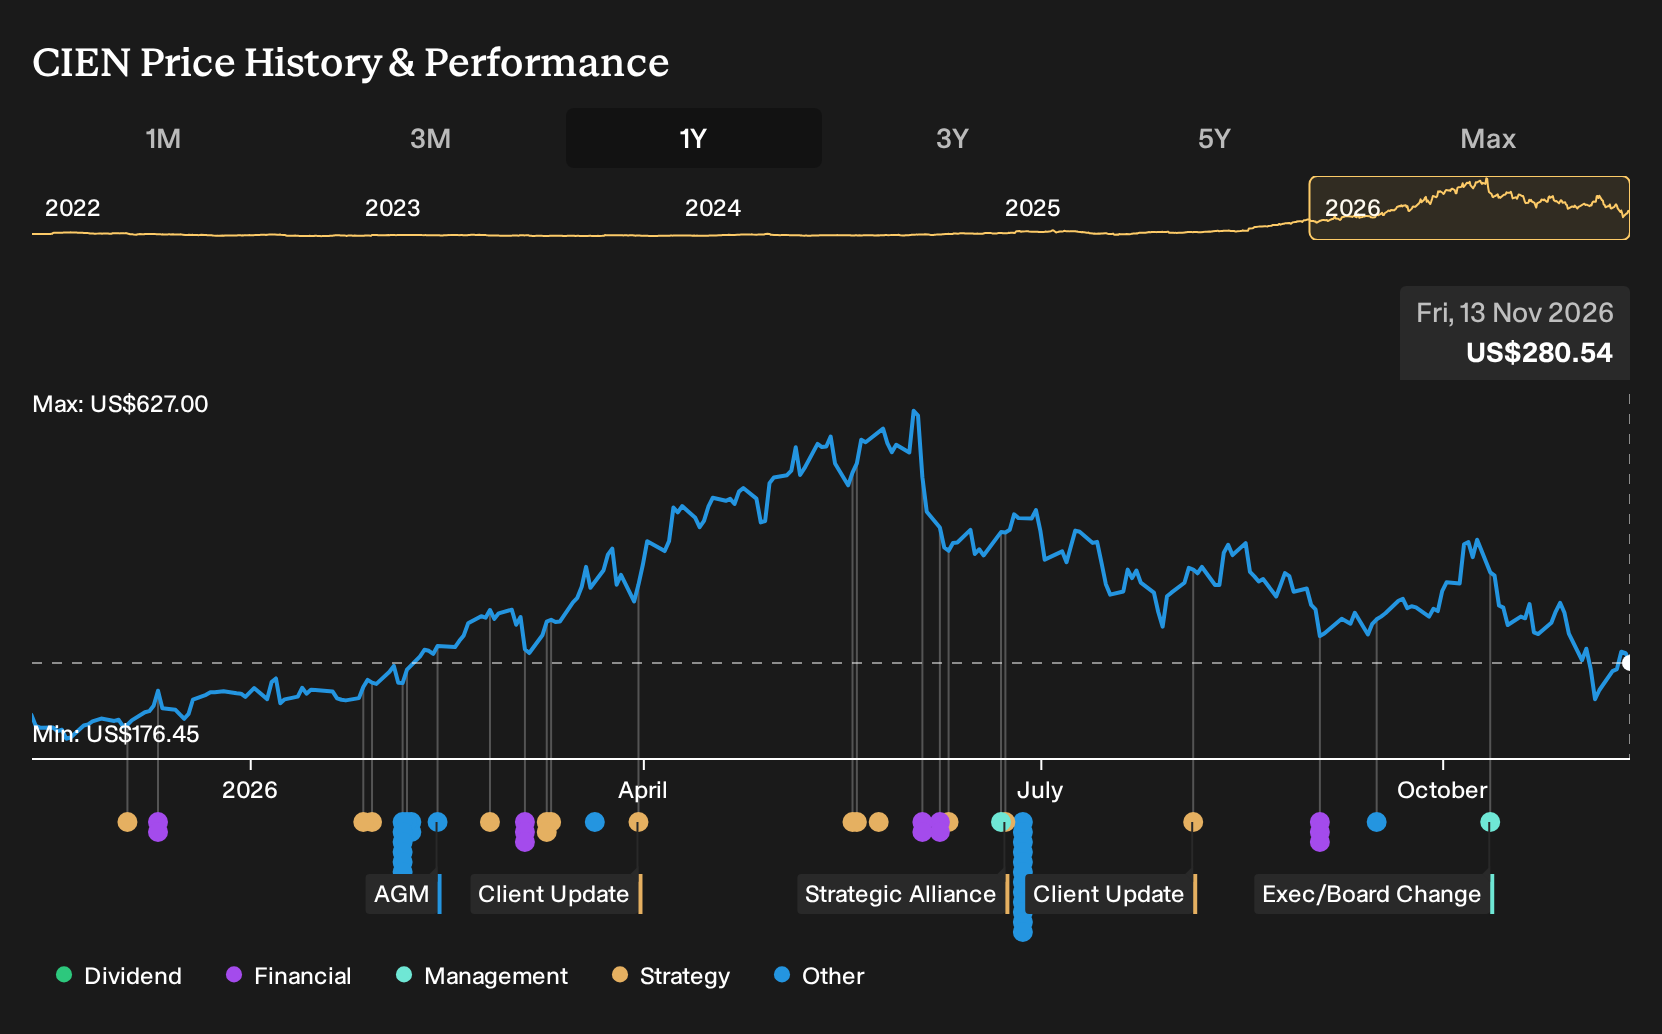
The analyst consensus narrative on Simply Wall St leans heavily on Ciena’s margin roadmap and the idea that higher profitability by 2029 could justify today’s valuation even after a roughly 7x multi year share price move. That framework makes the upcoming earnings call less about the past quarter and more about whether management keeps reaffirming those margin and free cash flow goals.
With no fresh company announcements tied directly to this report, the most relevant “announcement” is management’s existing plan to push gross margin toward about 50% and operating margin into the low to mid 30s by 2029. Each quarter, including this one, becomes a check in on how pricing, product mix and supply agreements are tracking against that target, and whether heavy exposure to a few hyperscalers is helping or quietly increasing execution risk.
Ciena's narrative projects US$13.0b revenue and US$3.0b earnings by 2029. That path assumes revenue grows by 29.4% per year and earnings rise by about US$2.3b from US$654.4m today to reach the analyst consensus target.
Uncover why Ciena's fair value points to an 83% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view leans on a different catalyst. Bullish analysts focus on Ciena using its AI focused backlog to support higher earnings than consensus. Some of them were modelling about US$14.6b of revenue and US$3.3b of earnings by 2029, which is more optimistic than the US$13.0b and US$3.0b baseline. These projections were set before this earnings update, so treat them as starting points rather than finished conclusions, and compare several viewpoints before deciding what matters most to you.
Explore 4 other Ciena fair value estimates, including one that suggests as much as 135% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ciena research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ciena. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ciena's overall financial health at a glance.
Looking for more ideas beyond Ciena?
Once you have a view on Ciena, it can help to cross check that thesis against other opportunities that match different risk and income profiles using the Simply Wall St Screener.
- For investors hunting for higher potential upside in smaller companies, scan a curated set of 13 elite penny stocks with strong financials that already show stronger financial foundations than most in their bracket.
- If you want quality at a discount and care about cash flow strength, compare Ciena with a 34 high quality undervalued stocks that blend solid balance sheets with healthier fundamentals.
- For a steadier ride with an eye on capital preservation, weigh Ciena against a 29 resilient stocks with low risk scores that score well on resilience and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com