


EN
Earnings Beat Could Be A Big Moment For Onto Innovation Stock (ONTO)
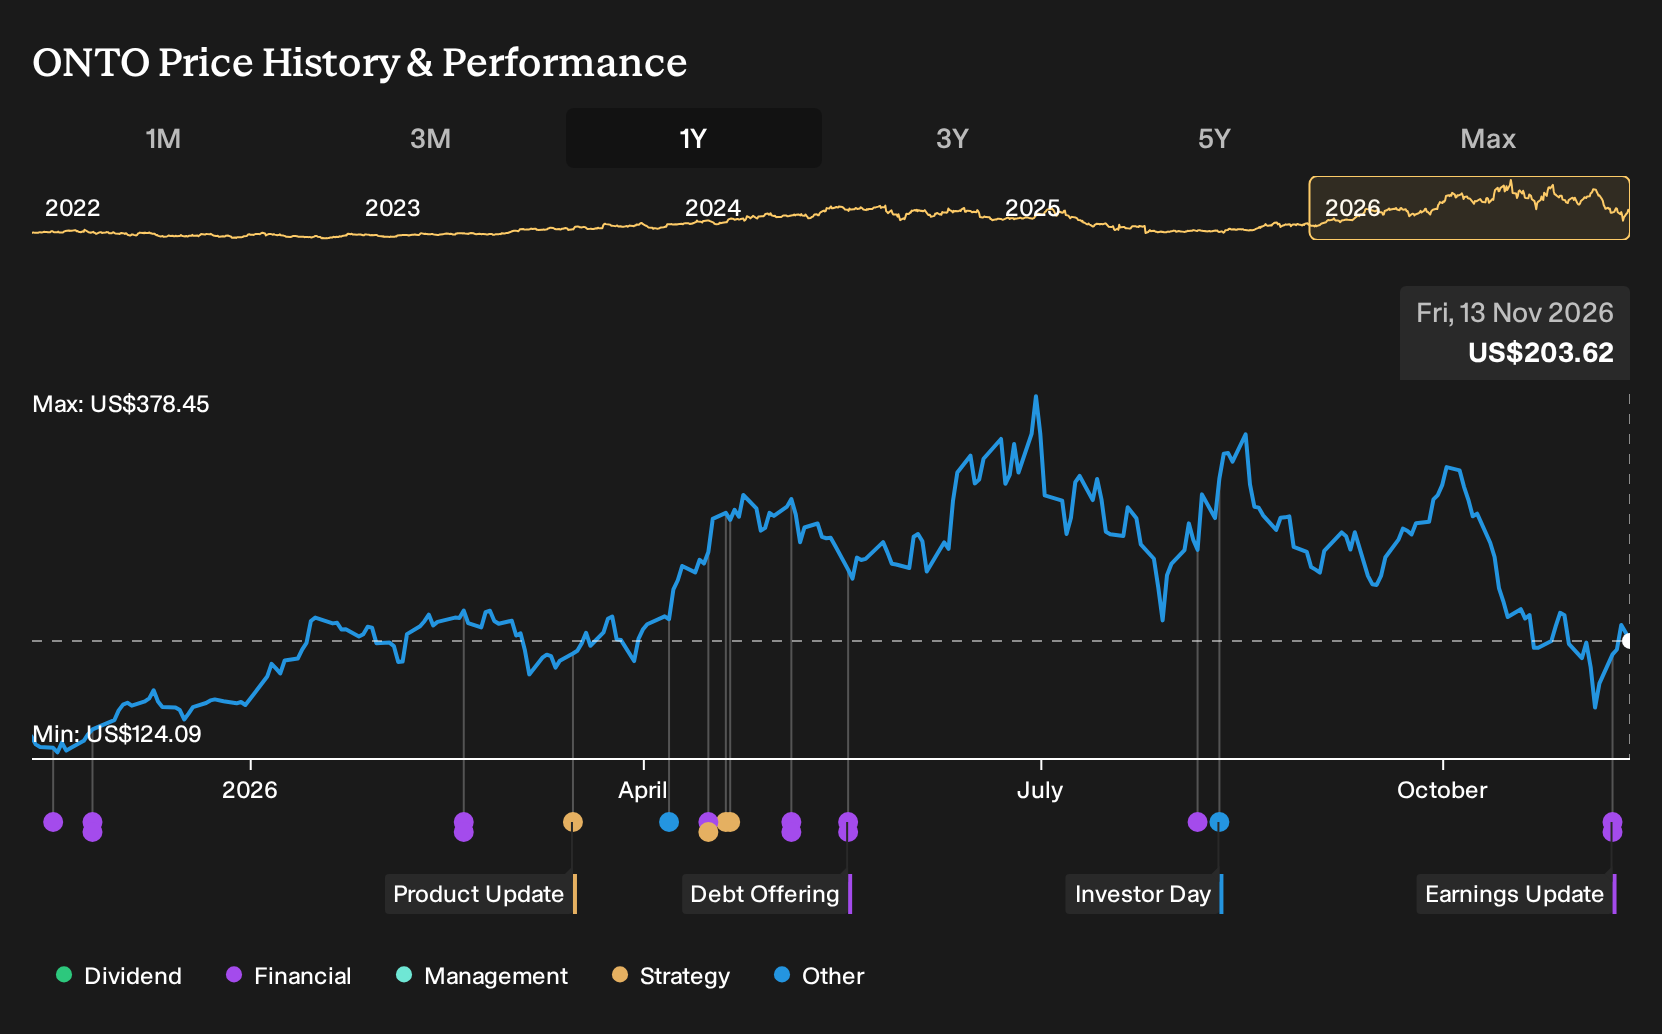
- Onto Innovation reported third quarter 2026 sales of US$409.75 million and net income of US$46.85 million, with diluted EPS from continuing operations of US$0.95, and issued fourth quarter guidance that includes expected revenue between US$430 million and US$450 million.
- The latest results show Onto Innovation generating higher quarterly sales and earnings than the prior year, while guiding to further revenue growth and operating income between US$105.1 million and US$111.9 million. This reflects execution on current demand and expectations for continued operational scale.
- We will now look at how Onto Innovation's strong third quarter sales performance could influence its existing long term investment narrative.
Scan how Onto Innovation's latest earnings momentum compares with other chip and automation plays by weighing it up against a hand picked set of 53 AI infrastructure stocks.
Onto Innovation Investment Narrative Recap
For an investor to stay with Onto Innovation, the core belief is that AI focused packaging, advanced nodes and panel level tools can offset softness in areas like power semis and turn multi year orders into consistent earnings. The analyst consensus narrative on Simply Wall St rests on that execution, along with extended factories that support margins as volume builds.
The new third quarter numbers and fourth quarter outlook indicate that demand is still flowing through the income statement, so the near term revenue catalyst appears intact. The bigger swing factor remains whether legal investigations, lower net margins and the large Rigaku commitment restrain earnings quality or balance sheet flexibility.
The clearest link to that thesis is the fresh fourth quarter 2026 guidance. Management is calling for US$430 million to US$450 million of sales, operating income of US$105.1 million to US$111.9 million and GAAP diluted EPS of US$1.95 to US$2.07. Those figures help investors track how effectively Onto Innovation is converting its AI heavy backlog into profit.
That guidance also frames the trade off that investors are watching. Stronger operating income can support the idea of higher future returns, while ongoing margin pressure, large one time items and any fallout from fiduciary duty investigations could limit how much of that guidance translates into long term earnings power.
Onto Innovation's narrative projects US$2.6b revenue and US$990.7 million earnings by 2029. This assumes revenue expands at 25.6% per year and requires roughly a 6.6x earnings increase from US$151.2 million today.
Explore how Onto Innovation's fair value indicates a 74% potential upside to its current price, before that gap starts to close.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Onto Innovation’s extended factories as the key catalyst. Before this earnings release, they were pencilling in about US$2.8b of revenue and US$845.9 million of earnings by 2029. You can treat this as a higher gear version of the consensus and then ask whether today’s results nudge you closer to that view or toward more cautious forecasts.
Explore 4 other Onto Innovation fair value estimates, including one that suggests as much as 87% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Onto Innovation research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Onto Innovation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Onto Innovation's overall financial health at a glance.
Looking For More Ideas Beyond Onto Innovation?
If Onto Innovation has sharpened your thinking about where to put fresh capital, use that same lens across the broader market. The Simply Wall St Screener can help you filter for clear themes and financial traits instead of scrolling through tickers at random.
- If you want potential mispricings with quality fundamentals, start by reviewing a curated 19 high quality undiscovered gems that may not yet be on every investor's radar.
- For readers who care most about resilient balance sheets and solid finances, scan the list of solid balance sheet and fundamentals (24 results) to find businesses that prioritize financial strength.
- If keeping downside risk in check is your first filter, narrow the field with a 29 resilient stocks with low risk scores that focuses on companies with more stable risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com