


EN
Entegris (ENTG) Could Be 22% Undervalued As Kioxia Partnership Expands
Expanded Kioxia partnership puts Entegris’ materials engine in focus
The fresh expansion of Entegris (ENTG) and Kioxia’s partnership around BiCS FLASH 3D memory puts the materials specialist’s role in next generation chips squarely on investors’ radar.
The collaboration leans heavily on Entegris’ materials science, AI driven modeling, and digital twin tools, combined with Kioxia’s memory process know how, to tighten the link between device requirements and materials development.
Entegris’ latest share price of US$147.41 comes after a 7 day share price return of 15.18% and a year to date share price gain of 64.59%, while the 1 year total shareholder return of 88.88% contrasts with a 5 year total shareholder return that is slightly negative. This suggests momentum has picked up recently as investors weigh the expanded Kioxia alliance, the newly announced US$500 million repurchase plan and fresh comments on pursuing value focused M&A at the 2026 Capital Markets Day.
See how Entegris fits into the broader chip materials story by comparing it with a curated 53 AI infrastructure stocks that supports next generation computing and data center demand.
After a sharp run to US$147.41 and a roughly 23% gap to the US$190.50 analyst target, Entegris now sits between optimism and caution. Is the market’s discount pointing to risk or opportunity on valuation?
Most Popular Narrative: 22% Undervalued
On the analyst consensus Narrative on Simply Wall St, Entegris screens as undervalued, with a fair value of $189.07 against the last close at $147.41. That gap frames how much of the AI and fab build story is already reflected in the price.
Analysts expect Entegris to continue benefiting from AI-linked advanced node and memory demand, as well as multi-year fab construction and wafer equipment investment that support growth in both consumables and capex-driven products.
The main factor that has to go right is that Entegris maintains its margin and cash flow progress by successfully ramping newer facilities, closing dilutive operations, and using its existing manufacturing capacity while keeping capital spending disciplined.
See why 13 investors see Entegris as 22% undervalued.
Result: Fair Value of $189.07 (UNDERVALUED)
Still, the Entegris narrative can be knocked off course if high P/E expectations collide with sector volatility, or if recent revenue and free cash flow patterns persist.
Find out about the key risks to this Entegris narrative.
Another Angle on Entegris’ Valuation
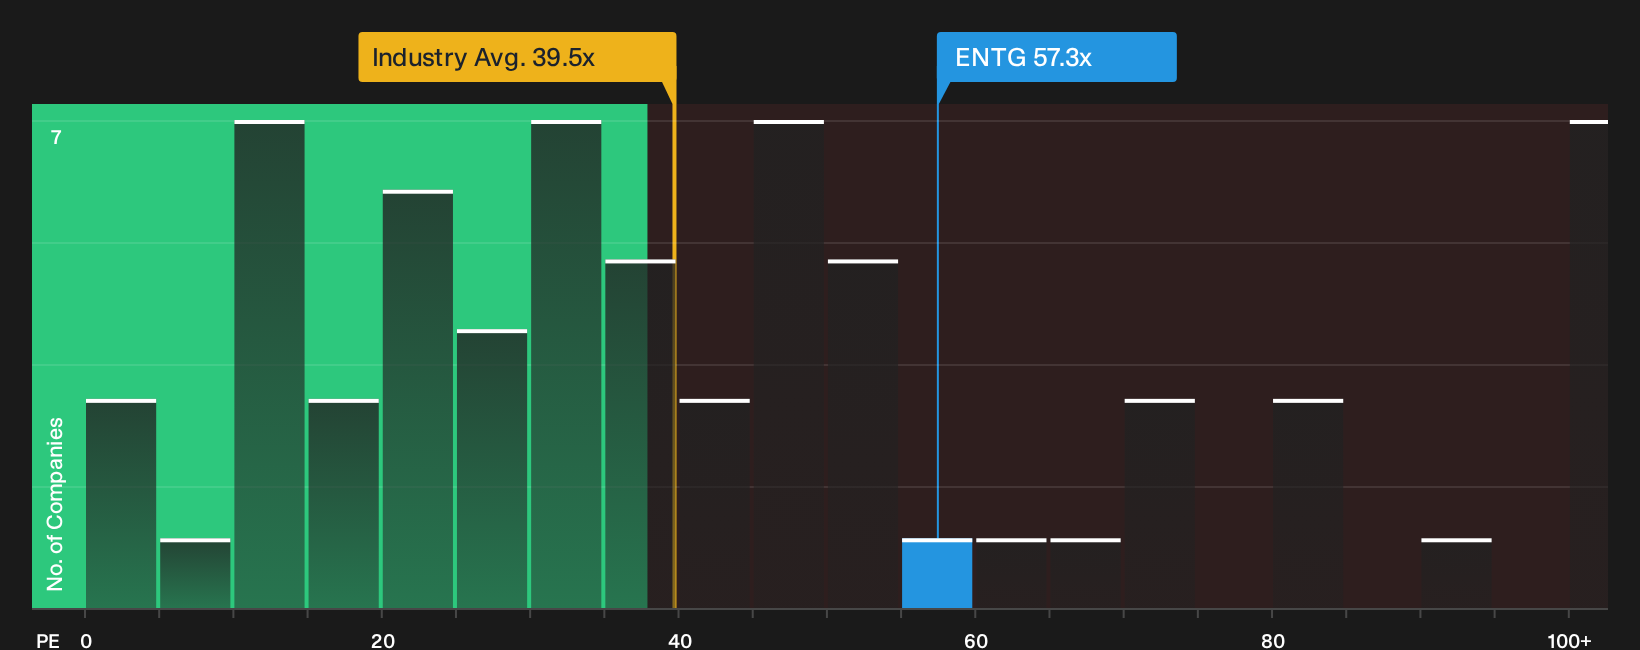
Analysts see Entegris as undervalued against a US$189.07 fair value, yet the P/E of 57.3x paints a very different picture. That level is far above the peer average of 27.8x and the fair ratio of 35.8x, which raises a simple question for investors. Is growth quality strong enough to justify paying so far ahead of both sector and modelled fair ratio?
For a closer look at how the current price stacks up against earnings power, it is worth reviewing a detailed multiples breakdown and how it links back to quality, growth and risk in Entegris’ story, then comparing that to other semiconductor materials stocks See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of strong share price momentum and premium P/E on Entegris leaves you unsure, that is the right instinct. Act while the information is fresh, compare the upside and the risk signals together, and then decide where you stand with 2 key rewards and 1 important warning sign.
Looking for more Entegris-sized investment ideas?
Do not stop with Entegris. Broaden your watchlist now, compare different risk reward profiles, and give yourself more options before the next big move slips away.
- Target potential mispricing by scanning a curated set of quality businesses trading below their implied value using the 34 high quality undervalued stocks.
- Prioritize resilience first and look for companies with robust finances through a focused list of solid balance sheet and fundamentals (24 results).
- Identify potential future market favorites early by filtering for strong fundamentals in a tightly selected pool of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com