


EN
DoorDash (DASH) Stock Looks Overvalued On Current Earnings
DoorDash has fallen back this year after a strong multi year run, which puts a spotlight on whether the current share price lines up with what the business earns. Recent product launches and partnerships keep the story busy, but the question for you is whether the earnings profile supports where the stock now trades.
- Over the past 3 years the stock has delivered a gain of 80.1%, which raises the stakes on whether the underlying earnings power has kept pace with that move.
- The rollout of robot deliveries in Australia and the Lyft Go and $12 Meal Box initiatives may support expectations for order volume, unit economics and ultimately earnings quality if they scale efficiently.
- Your read on DoorDash is one view; the desks covering it have another. See what analysts think DoorDash's shares could be worth.
The issue now is whether DoorDash's current market value is adequately backed by its earnings today and what analysts expect those earnings to look like over time.
If you are weighing whether DoorDash's recent drop lines up with its earnings profile, it can help to compare that same question across 34 high quality undervalued stocks.
Does DoorDash Look Pricey on Earnings?
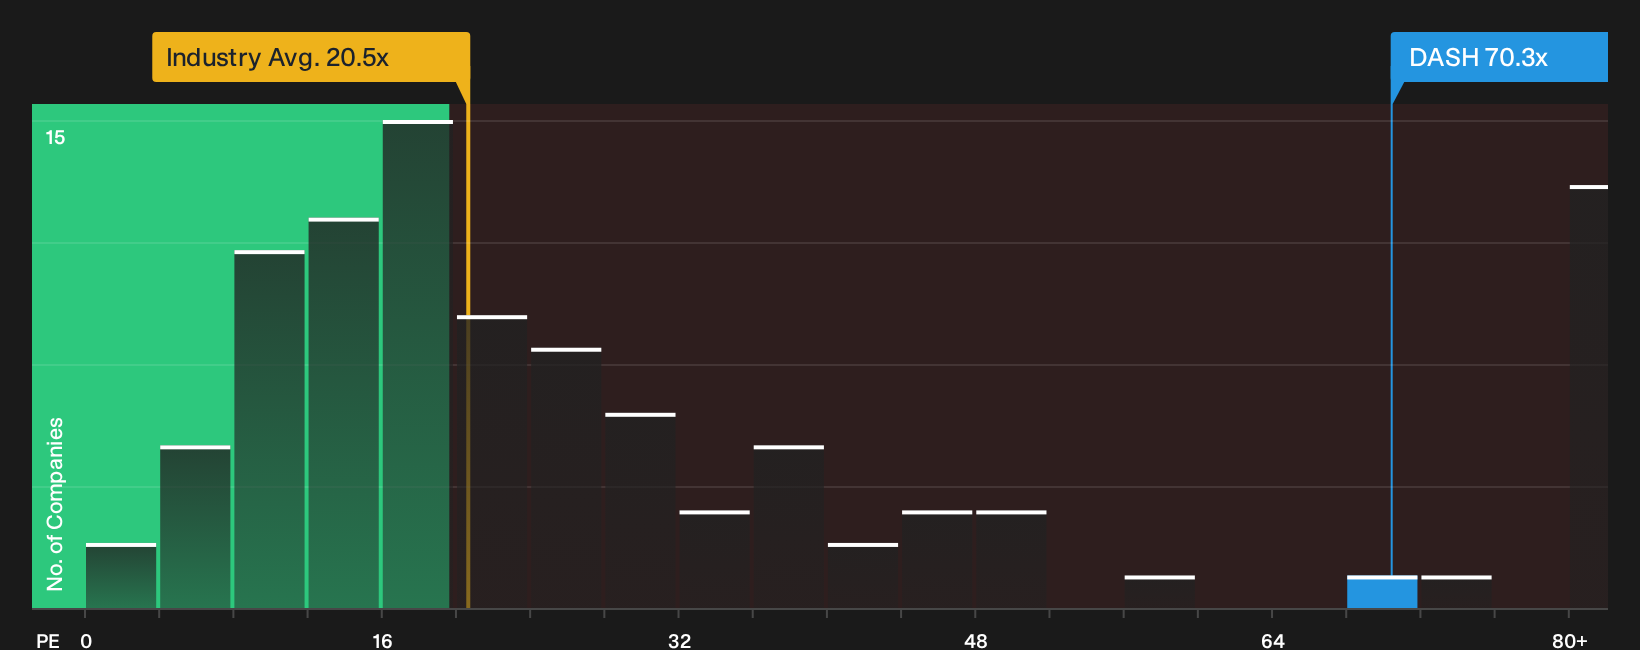
The P/E ratio suits DoorDash because the story investors are watching is ultimately about how much profit each share is tied to. At roughly 70.3x earnings, DoorDash stock trades at a much richer multiple than the broader hospitality industry, where the average is about 20.5x, and also above the peer group near 27.3x. That gap means you are paying a far higher price for each dollar of current earnings than for many other consumer and services platforms.
The Fair Ratio framework, which blends factors like DoorDash's growth outlook, margins, sector and risk profile, points to a lower earnings multiple than the current P/E, so the shares look overvalued on this lens. Despite the buzz around Lyft Go and the $12 Meal Box rollout, the market is still assigning a premium valuation compared with what this earnings based yardstick suggests might be more typical for DoorDash. Explore the numbers behind DoorDash's P/E valuation.
The DoorDash Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the DoorDash valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to play out for the stock to be worth substantially more or less than it is today. Each one treats fair value as a thesis about DoorDash's business that you can track over time, instead of a static number that never gets revisited, and they sit on the Community page.
One of the top narratives on DoorDash: 31% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that DoorDash turns fast-growing grocery, retail, and international operations into consistently gross profit positive businesses…"
Discover why this Narrative puts DoorDash at 31% undervalued.
Before you act on DoorDash’s valuation, there is one more piece to check
Price and profits only tell part of the story for DoorDash, because the people setting priorities and how they are rewarded can heavily shape where the business goes next. See who runs DoorDash and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com