


EN
3 Undervalued Stocks Trading At Least 33% Below Cash Flow Value
The Fed’s preferred inflation gauge lands on November 25, and a hot reading could keep borrowing costs elevated for longer. Expensive credit often punishes companies that rely heavily on debt, which can leave cash rich businesses on sale. That is where mispriced cash flow generators come in. This article breaks down three stocks from a cash flow focused value screen that appear cheaply priced against their long term cash potential.
The three stocks highlighted below are a small sample from the screen. The full process surfaced 432 more companies with cash flow stories that may be just as compelling but are not covered here. To cast a wider net and identify ideas that match your own risk, sector, and valuation filters, head straight into the Undervalued Stocks Based On Cash Flows screener.
PORR (WBAG:POS)
PORR is a Vienna based construction group that leans heavily on civil engineering and infrastructure work. Long dated public contracts and PPP projects can support the cash flow focus of this screen.
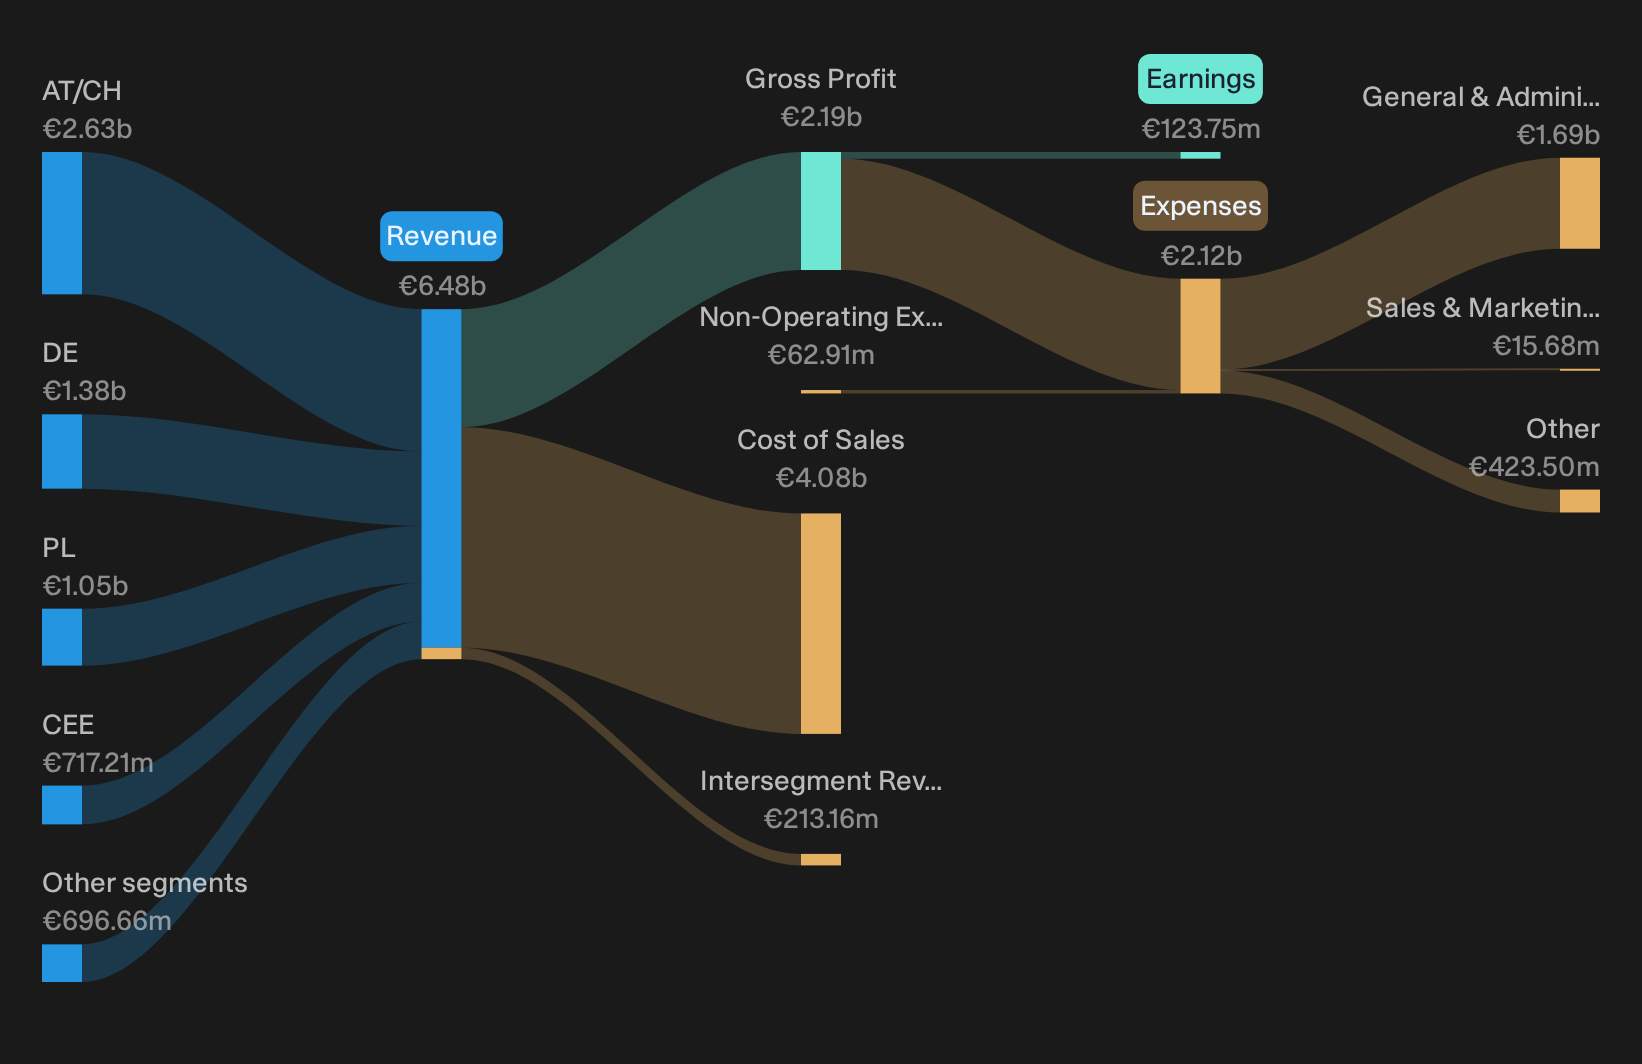
PORR generates most of its revenue from AT/CH at about €2.6b, with sizeable contributions from Germany at roughly €1.4b, Poland near €1.1b, CEE at around €700 million, and a smaller Infrastructure International unit at about €500 million. The stock carries a market value of roughly €1.3b.
The analyst consensus Narrative on Simply Wall St highlights how PORR’s current project mix links that cash flow story directly to higher value, technically complex infrastructure work.
"The higher share of complex design and build work in PORR’s record order backlog, including international tunneling and railway construction in Poland and Romania, points to a growing mix of technically demanding projects that can support EBIT margins and profitability as this portfolio is delivered."
What happens if one less visible cost pressure quietly eats into those future project margins?
If that gradual increase in costs is important to your thesis, read the full narrative for PORR to see how PORR’s project mix and balance sheet could be decoupling.
Oracle (ORCL)
Oracle runs a broad suite of enterprise software, databases, and hardware. However, its cloud subscriptions, from OCI and Fusion Cloud to NetSuite, are what tie it most directly to the screener’s cash flow theme. These offerings drive most of the US$62.8b in cloud and software revenue, alongside US$5.8b from services and US$3.2b from hardware, all underpinned by a roughly US$390.8b market value.
According to TickerTickle, an investor in the Simply Wall St Community who wrote a detailed Narrative on the stock, Oracle’s repositioning around AI workloads is central to understanding its future cash flows.
"The foundation of Oracle’s AI narrative rests on its Gen2 AI infrastructure and the validation it received from the premier generative AI powerhouse, OpenAI."
What happens to that optimistic cash flow story if one crucial assumption about how quickly those massive AI commitments convert into spendable dollars starts to shift?
If that timing question is on your mind, read the full narrative for Oracle to see how Oracle’s AI infrastructure bets could accelerate or stall future cash generation.

Amazon.com (AMZN)
Amazon.com is best known for its online retail and Prime membership ecosystem, yet the AWS cloud division is what links it directly to this cash flow focused screen, according to MarketMuse, an investor in the Simply Wall St Community who wrote a detailed Narrative on the stock.
Amazon.com runs global online and physical stores plus advertising and subscription services. AWS contributes the key cloud compute and AI cash flows. Recent revenue was about US$460.3b from North America, US$175.8b from International, and US$161.4b from AWS, against a roughly US$2,883.4b market value.
"AWS reaccelerated through 2025 with roughly 20% year-over-year growth, exiting the year with an annualized revenue base exceeding $130 billion."
What happens to that cash flow story if one unseen pressure on how profit from this expansion is shared across the wider Amazon.com group shifts?
That shifting pressure is exactly what the full narrative for Amazon.com unpacks, separating AWS cash strength from group wide capital demands and identifying where Amazon.com’s next leg of acceleration might come from.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first and slow research often gets caught chasing momentum after the breakout. Scan under the radar for now, while it matters, and get in early.
- Target durable income streams while others chase headlines, and review the 221 dividend fortresses built to spotlight high-yield payers that still keep an eye on balance sheet strength.
- Track where resilience meets calm compounding by scanning the 207 resilient stocks with low risk scores, which filters for businesses with sturdier risk profiles and room for steadier progress.
- Ride structural shifts in global infrastructure by using the 44 power grid technology and infrastructure stocks, tuned to companies that are more directly connected to long term electricity demand and grid upgrades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com