


EN
Does Earnings Jump Change The Bull Case For UDR Stock (UDR)?
- UDR, Inc. reported third quarter 2026 revenue of US$428.08 million and net income of US$216.09 million, with diluted EPS from continuing operations of US$0.67, compared with US$0.12 a year earlier.
- The sharp increase in earnings relative to largely stable revenue suggests that UDR’s cost structure, mix of assets, or non operating items had a meaningful impact on profitability.
- We will now look at how UDR’s sharply higher net income reshapes the existing investment narrative built around capital recycling.
Compare UDR’s earnings increase with its peers that are recycling capital and tightening costs by reviewing our curated 29 resilient stocks with low risk scores.
UDR Investment Narrative Recap
To own UDR, investors need to be comfortable with a multifamily REIT that is leaning on capital recycling, data tools and resident retention to support earnings, while accepting that some of the recent profit strength comes from large one off items. The analyst consensus Narrative on Simply Wall St already assumes modest revenue expansion and a decline in margins, so the sharp year on year EPS move does not automatically reset the short term story.
The near term swing factor still sits in how well management offsets supply and pricing pressure in Sunbelt markets and manages interest costs that are not well covered by earnings. The biggest risk remains that proceeds from roughly US$650 million of asset sales and the US$380 million debt and preferred equity run off are reinvested slowly or at lower returns. This could leave revenue, NOI and EPS tracking below the expectations implied in that narrative.
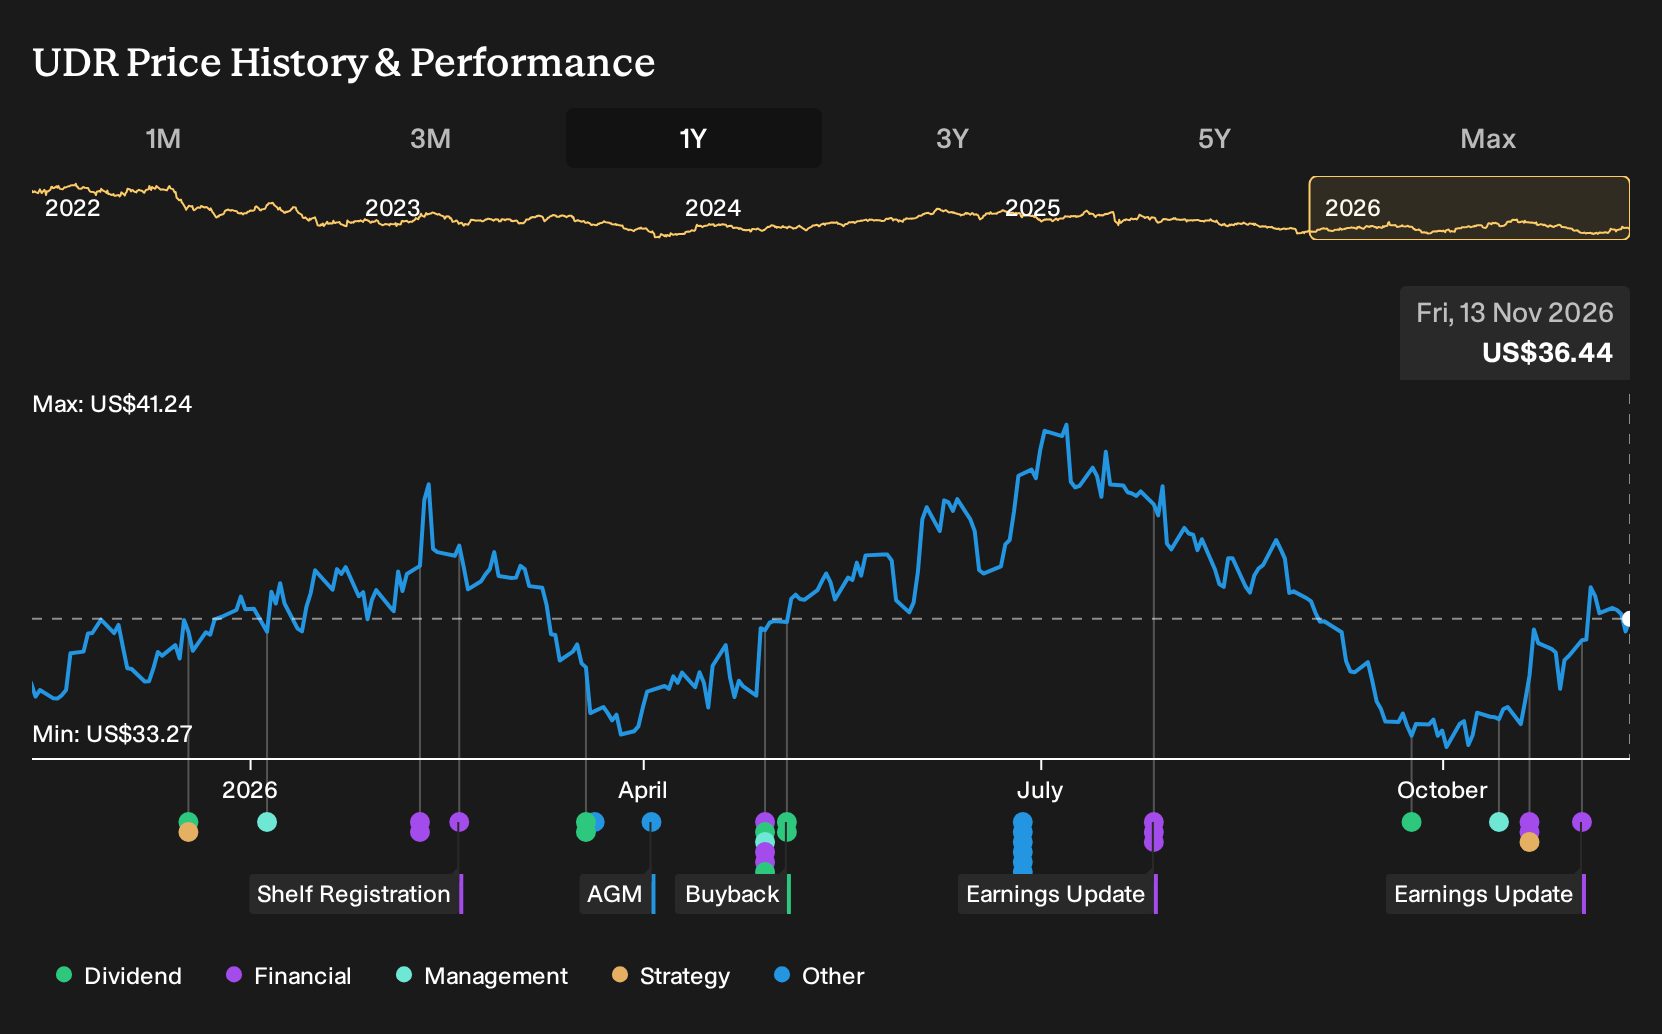
The latest quarterly release is the key data point to watch. UDR reported third quarter 2026 revenue of about US$428 million and net income of about US$216 million, and for the nine months to September 30 it recorded revenue of about US$1.28b and net income of about US$475 million. Management also disclosed that EPS growth versus last year is heavily affected by very large non recurring items, which already feature in the risk flags.
That context matters for catalysts built around capital recycling and Orion analytics. If a large slice of the recent earnings step up eventually unwinds as those one off items roll out of the numbers, then execution on same store performance, resident retention, fee income growth and redeployment of the remaining US$380 million portfolio become even more important. This is particularly relevant for anyone using these results as a reference point when weighing the current UDR share price against the analyst consensus Narrative on Simply Wall St.
UDR's narrative projects US$1.8b revenue and US$182.4 million earnings by 2029. This implies 1.0% yearly revenue growth and an earnings decrease of about US$334.9 million from US$517.3 million today.
Uncover how UDR's fair value indicates a 9% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Fair value views on UDR from the Simply Wall St Community already span roughly US$39.64 to US$58.97 across 2 separate assessments, so you are looking at a wide bracket of expectations. When you also consider risks around Sunbelt rent pressure and regulatory costs, the spread in opinions starts to look even more understandable.
Explore another UDR fair value estimate, including one that suggests it could be worth just $39.64.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your UDR research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for UDR. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UDR's overall financial health at a glance.
Looking for more investment ideas beyond UDR?
If UDR has you rethinking how you allocate capital across your portfolio, it can help to line it up against other companies with very different risk and reward profiles using the Simply Wall St Screener.
- For investors who care most about financial resilience, compare UDR with a list of solid balance sheet and fundamentals (24 results) that can help you focus on businesses with sturdier foundations.
- If potential mispricing is your main interest, use our curated 34 high quality undervalued stocks to find companies where fundamentals and share prices look out of sync.
- Income focused investors can cross check UDR against a hand picked 6 dividend fortresses that highlights companies offering higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com