


EN
Record Revenue Might Change The Case For Investing In U.S. Bancorp (USB)
- U.S. Bancorp recently completed and announced multiple fixed income offerings across U.S. dollar and Canadian dollar markets, while reporting record third quarter net revenue, planning to resume share buybacks, and continuing a major hiring push in middle market banking.
- The combination of new callable senior notes, record net revenue, and 60 planned middle market hires suggests U.S. Bancorp is leaning into fee driven payments, lending, and capital markets expansion rather than pulling back.
- Now the focus shifts to how this record net revenue and planned buyback restart could reshape U.S. Bancorp's existing investment narrative.
See how U.S. Bancorp's funding moves compare with other financially resilient banks by reviewing our hand picked 29 resilient stocks with low risk scores in a single, focused view.
U.S. Bancorp Investment Narrative Recap
To own U.S. Bancorp, you need to be comfortable with a large universal bank that leans heavily on fee income, technology spend and capital markets build out, as described in the analyst consensus Narrative on Simply Wall St. The near term story revolves around turning that fee mix, BTIG integration and middle market push into steadier earnings while keeping credit costs in check.
The fresh wave of callable senior notes looks incremental to that thesis rather than a major swing factor. In the near term, the key upside driver remains execution in payments and capital markets. The biggest risk continues to be credit stress in commercial real estate or weaker regional economies that would pressure earnings and capital flexibility.
The recent CAD 1b fixed to floating rate notes due 2032 are most relevant here because they show U.S. Bancorp actively using wholesale markets to support its broader build out. That sits alongside plans for higher branch investment, multi billion dollar tech spend and capital markets expansion through BTIG.
For you, the question is whether this extra term funding supports the catalysts in the analyst consensus Narrative on Simply Wall St, such as growing fee income toward a larger share of total revenue and holding CET1 around the 10% target. Any misstep in deploying this capital, or a turn in credit, would weigh on that story.
U.S. Bancorp's narrative projects US$37.8b revenue and US$9.1b earnings by 2029. This implies 10.7% yearly revenue growth and an earnings increase of about US$1.1b from US$8.0b today.
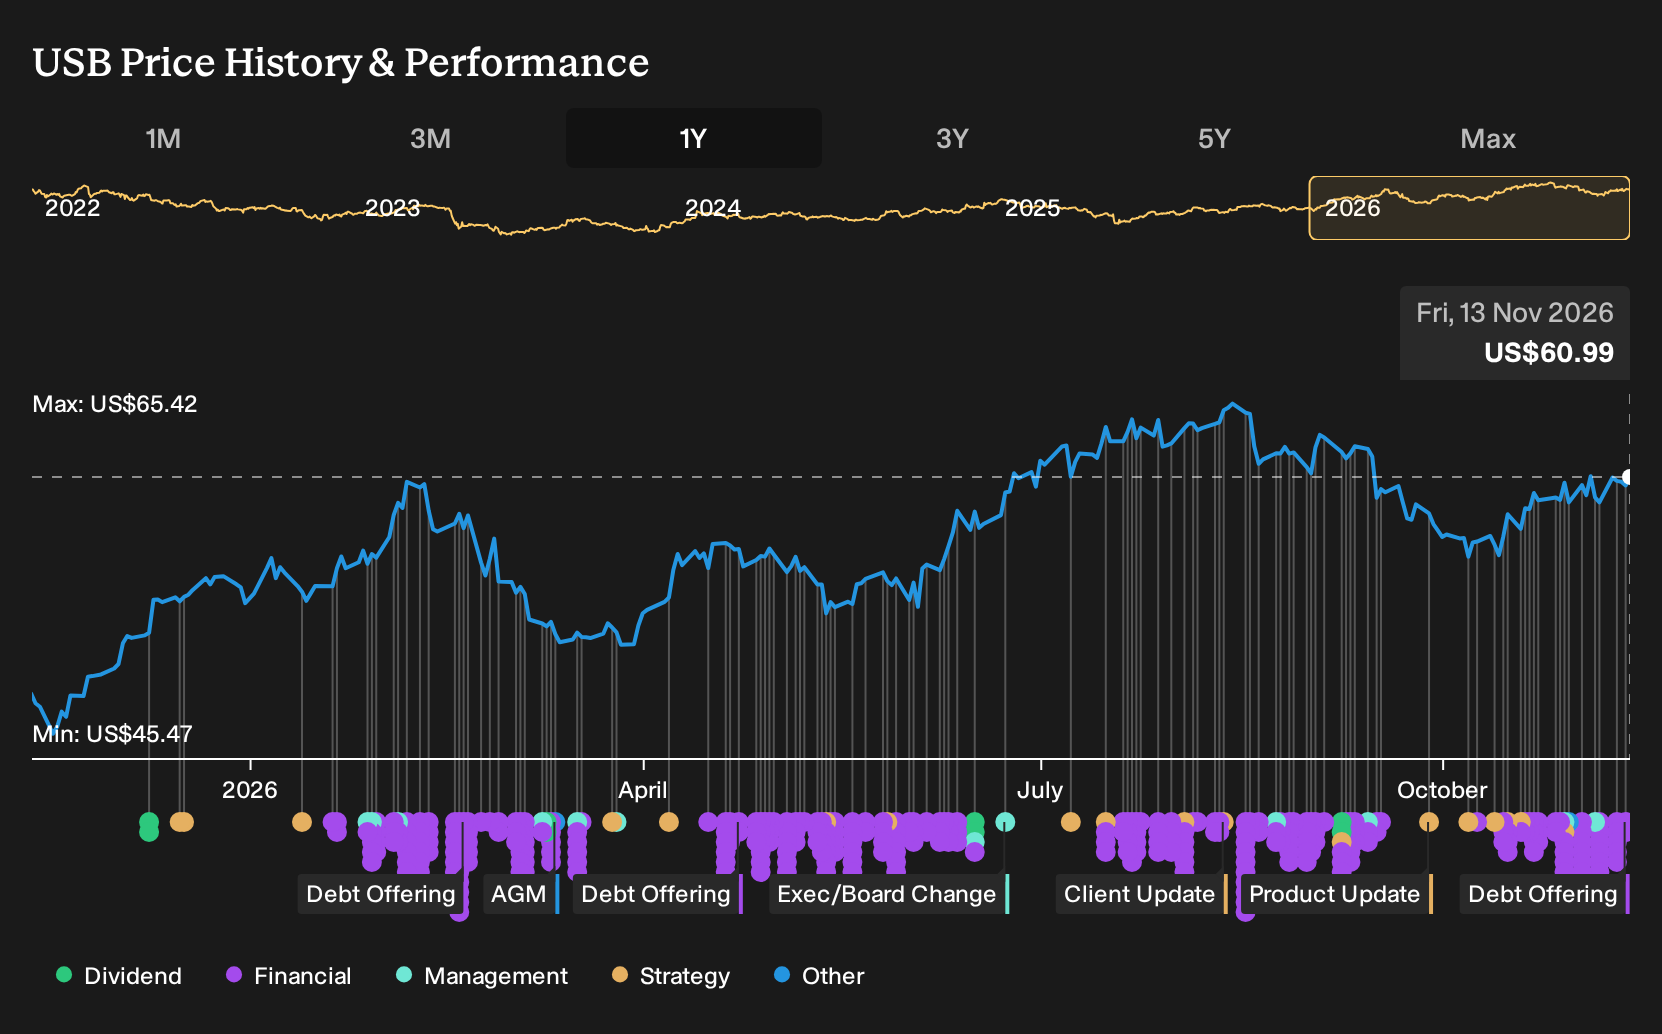
Uncover why U.S. Bancorp's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly US$58 to US$98, so some U.S. Bancorp watchers see a wide gap between price and their own models. Those views sit beside fresh fixed income issuance and an expanding payments and capital markets push, which can sharpen or challenge your own thesis. Opinions differ widely, so explore several of these alternative viewpoints before deciding how the story fits your portfolio.
Explore 4 other U.S. Bancorp fair value estimates, including one that suggests potential upside of up to 61% from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your U.S. Bancorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for U.S. Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate U.S. Bancorp's overall financial health at a glance.
Looking for more U.S. Bancorp sized investment ideas?
If the U.S. Bancorp story has sharpened your thinking, use that same framework across a wider watchlist by scanning for other companies that match your preferred mix of quality, balance sheet strength and income potential on the Simply Wall St Screener.
- If you want steadier balance sheets to compare against U.S. Bancorp, start with a focused list of solid balance sheet and fundamentals (24 results) that share strong financial foundations.
- For investors hunting for mispriced quality, widen your watchlist by checking a curated group of 34 high quality undervalued stocks that may warrant a closer look.
- If reliable income is a priority, round out your research with a set of 6 dividend fortresses that combine higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com