


EN
Nvidia Stock Slide Has Investors Looking At AI Chipmakers With Less China Exposure
Nvidia’s 28% slide from its peak and the swirl of China-related allegations have shaken confidence in one of the market’s marquee AI stocks, yet the real story for you sits in how money may quietly rotate into other chipmakers with cleaner exposure. That shift could benefit investors who do the homework early. This article examines three stocks from our Non-China-Focused AI Chipmakers and Foundry Capacity screener that appear positively exposed to this turmoil and explains why they may merit a closer look now.
The stocks covered below are just a starter pack. The full Non-China-Focused AI Chipmakers and Foundry Capacity screen surfaced 69 more companies with equally compelling stories that do not fit into a single article. If you want to move quickly from curiosity to a focused watchlist, head straight into the Non-China-Focused AI Chipmakers and Foundry Capacity screener to identify and analyze the highest conviction ideas for your own criteria.
IntelliEPI (Cayman) (TPEX:4971)
IntelliEPI (Cayman) produces compound semiconductor epitaxy wafers that feed into high speed wireless links and data transmission around AI data centers, which is fully aligned with this wafers and foundry focused screen. The business generated about NT$1.16b in semiconductor sales and carries a market value near NT$19.1b.
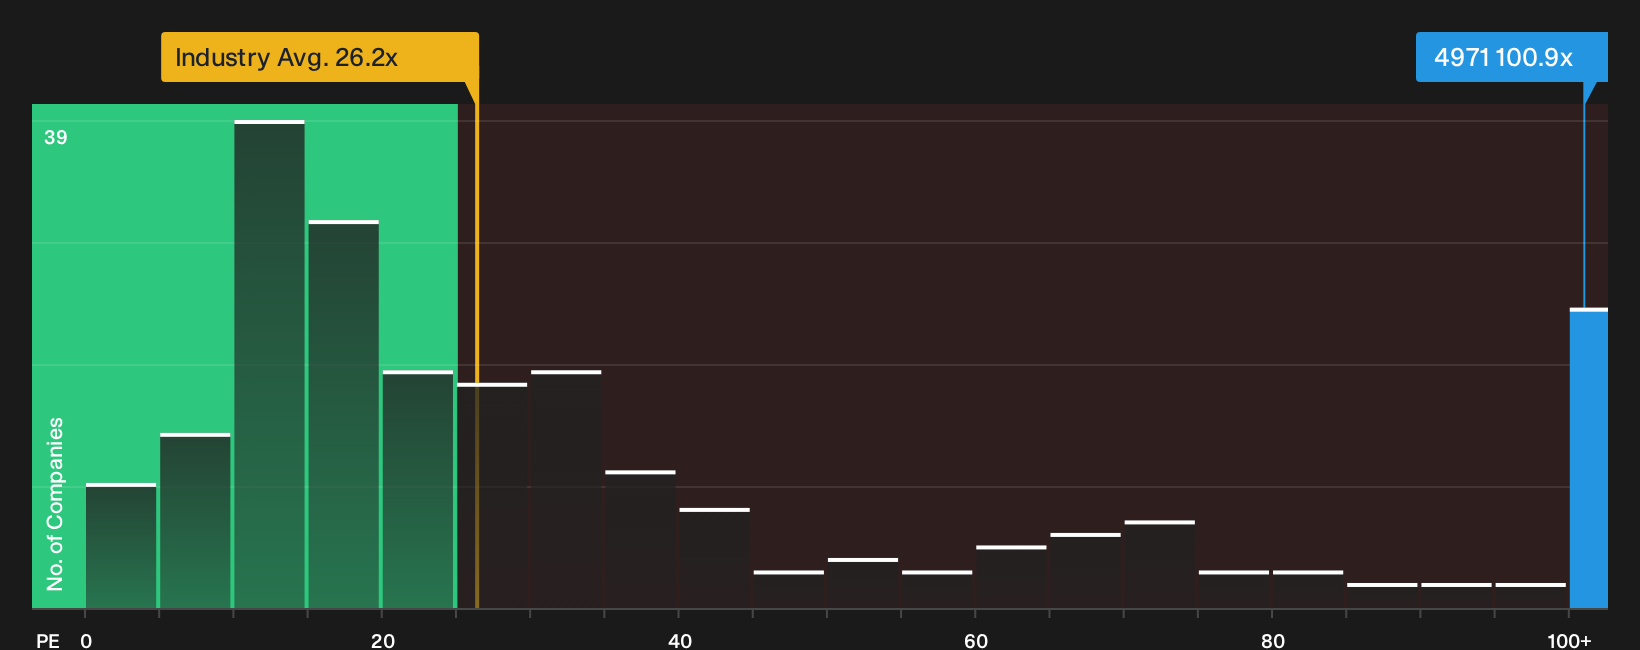
Investors looking at non China focused AI infrastructure should notice IntelliEPI (Cayman) supplying specialty epitaxy wafers for wireless, data links and defense across the US, Germany, Korea and Japan, with 2026 sales and profit now positive. A key consideration is how its premium P/E holds up if a single assumption on future demand intensity shifts.
If that premium P/E is what worries you, go straight to the 2 key rewards and 2 important warning signs (1 is major!) to see what might be masking or amplifying IntelliEPI (Cayman)’s edge.
Microchip Technology (MCHP)
Microchip Technology supplies embedded control and connectivity chips that sit behind AI data centers, servers, and industrial systems, which fits the Non-China-Focused AI Chipmakers and Foundry Capacity theme. The business generated about US$5.39b from Semiconductor Products and US$212 million from Technology Licensing, and carries a market value near US$33.6b.
For investors looking beyond Nvidia, Microchip Technology offers a way to tap into AI infrastructure through controllers, connectivity and memory that plug into servers, industrial gear and aerospace systems. The analyst consensus Narrative on Simply Wall St describes how that translates into hard numbers and future expectations.
Microchip Technology is seeing structural expansion in data center and AI infrastructure exposure, with total data center revenue expected to increase from about US$591 million in 2025 to roughly US$1 billion in 2026 and PCIe Gen6 design wins, including an estimated US$100 million annual program starting in 2027, which together indicate a larger contribution to future revenue.
Everything now depends on how one less visible constraint shapes the balance between that AI demand potential and the margins supporting it.
That invisible constraint is exactly what the full narrative for Microchip Technology unpacks, mapping how accelerating AI demand, capacity choices, and capital returns could be pulling in different directions.

Diodes (DIOD)
Diodes supplies the quiet plumbing of AI hardware, with broad power, analog, and mixed-signal chips used in servers, networking gear, and data centers. The company generates about US$1.78b from standard semiconductor products and has a roughly US$4.0b market value.
While Nvidia’s troubles push investors to rethink where AI infrastructure spending actually lands, Diodes offers a different angle into that theme through everyday chips that keep data centers, autos, and industrial systems running. The analyst consensus Narrative on Simply Wall St describes how that story connects directly to its manufacturing footprint.
Increasing vertical integration and qualification of in-house wafer fabrication are expected to reduce reliance on costlier outsourced production, improve supply reliability, and lower costs. This is anticipated to support better net margin and earnings stability as utilization rises.
What really matters from here is how a quiet shift in its product and capacity mix shapes the earnings power behind that AI demand.
To see how that quiet product and capacity shift could re rate Diodes in the AI supply chain, read the full narrative for Diodes for the overlooked upside and pressure points.

Seeking Alternatives Before The Crowd
Fresh breakouts, fading laggards, and under the radar momentum can get caught quickly as attention flies elsewhere. Scan these ideas before the edge drops and consider them in a timely manner.
- Spot resilient cash generators before momentum chasers arrive by running the list of solid balance sheet and fundamentals (198 results), which filters for sturdier balance sheets and cleaner fundamentals while they are still under the radar.
- Hunt for income workhorses while yields remain elevated by using the 221 dividend fortresses, focused on businesses paying 5%+ and aiming to keep those payouts funded.
- Track early infrastructure names tied to AI build outs using the 53 AI infrastructure stocks, which highlights companies positioned in the picks and shovels of this trend.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com