


EN
What Mitsubishi Chemical Group Holders Bought Into
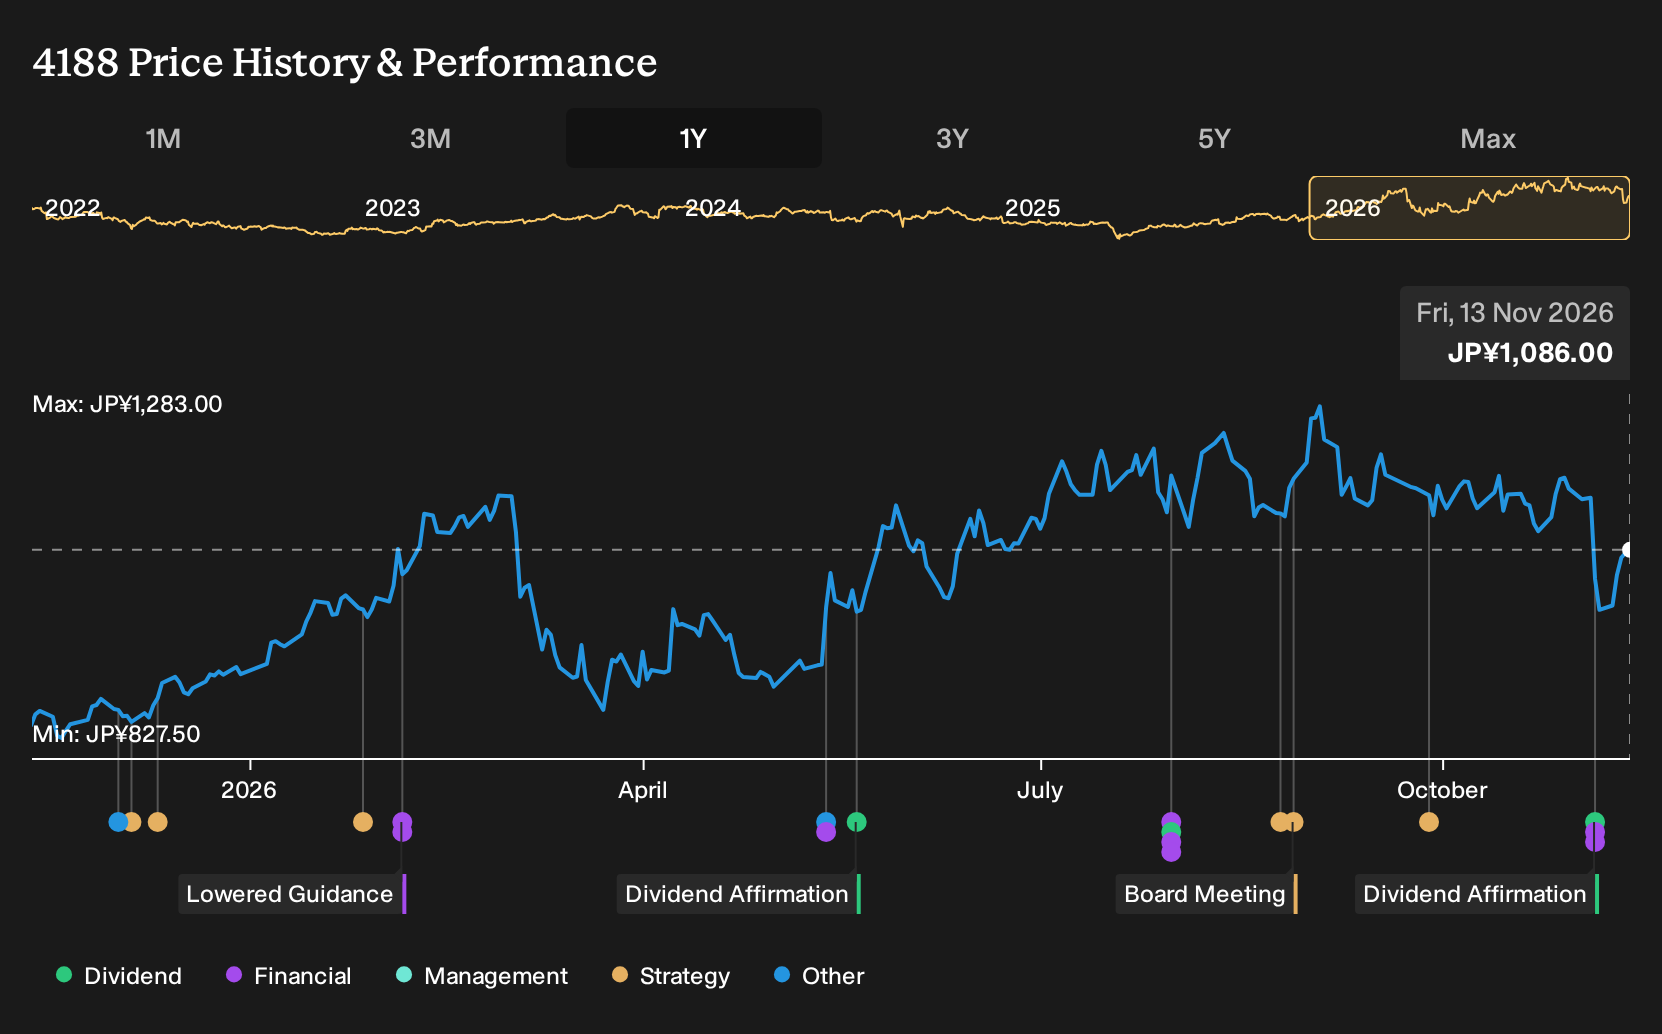
If you had bought Mitsubishi Chemical Group on 13 November 2025, you would now be looking back at a very different set of questions than the ones you started with. For Mitsubishi Chemical Group shareholders, the return over the past year was 29.5%, including dividends. Early buyers were weighing bullish arguments about share repurchases and margin resilience against bearish worries about regulation and Chinese competition. Were those investors really paying for a durable earnings mix, or just leaning into a generous capital return story?
Mitsubishi Chemical Group is not the only name tied to this theme. Zero in on 33 best rare earth metal stocks and compare how each one is priced.
The Argument You Would Have Been Weighing Up On Mitsubishi Chemical Group
The shares cost ¥858 at the start of the period, and anyone looking at Mitsubishi Chemical Group then was really choosing between two grounded stories about where the business might head.
On the bullish side, one camp saw the shift toward specialty and sustainable materials and share repurchases as the main draw. Their fair value was ¥923, a price they felt the earnings assumptions could justify if margins improved and the product mix moved further away from lower value basic materials.
The bearish view put more weight on rising environmental rules and low cost Chinese competitors. That group pinned fair value at ¥700, a level they thought reflected the risk that legacy petrochemicals, oversupply in MMA and higher compliance costs would keep profitability under pressure.
What The Results Changed For The Mitsubishi Chemical Group Thesis
The clearest new fact was Mitsubishi Chemical Group’s guidance revision for the year to March 2027, lifting expected sales and core operating income and supporting the optimistic case around specialty and sustainable materials. Reported numbers added another datapoint. Revenue moved from ¥918,472m in Q2 2026 to ¥1,032,848m in Q2 2027, and a prior loss turned into ¥32,467m of profit, with net margin shifting from -0.2% to 3.1%. The evidence cut both ways on durability but aligned with the more optimistic view on profitability.
The lesson is simple. When a story leans heavily on better margins, treat net margin and core earnings guidance as the main “trust but verify” line items. Then track whether those figures move in the same direction as the narrative at other companies you research.
What Mitsubishi Chemical Group's Price Seems To Assume Now
After a 29.5% gain over the past year to ¥1,086, Mitsubishi Chemical Group is being priced as a cleaner, more specialty tilted business. The bearish analyst Narrative on Simply Wall St argues that its Fair Value sits below the current price.
The Narrative centers on whether specialty and semiconductor related materials can consistently outweigh pressure from MMA, Basic Materials and restructuring charges. A buyer today would need to believe that portfolio reshaping, cost cuts and growth capex keep offsetting MMA volatility and exit costs.
"The numbers imply the share price already reflects optimistic assumptions about successful execution on Chemicals portfolio reshaping, specialty materials expansion, and cost savings. This is occurring even though the company still faces MMA spread risk, potential prolonged suspension of the Saudi MMA plant, and incomplete restructuring in Chemicals."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking One Step Beyond Mitsubishi Chemical Group
Mitsubishi Chemical Group points you toward specialty materials and cleaner chemistry. One step away, another business is wrestling with a different resource question.
Instead of polymers and resins, this one focuses on gold and copper in the ground. Its entire story centers on turning a single deposit into a working operation.
Your attention shifts from product mix to ore bodies, mine plans and processing plants. Cash flow depends on the gold price doing enough heavy lifting.
Execution risk also looks different for this miner. Bringing one project into stable production could sharply reshape how investors see the business.
One Narrative has put that dependency into a written case. → See the gold company one Narrative values 51% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com