


EN
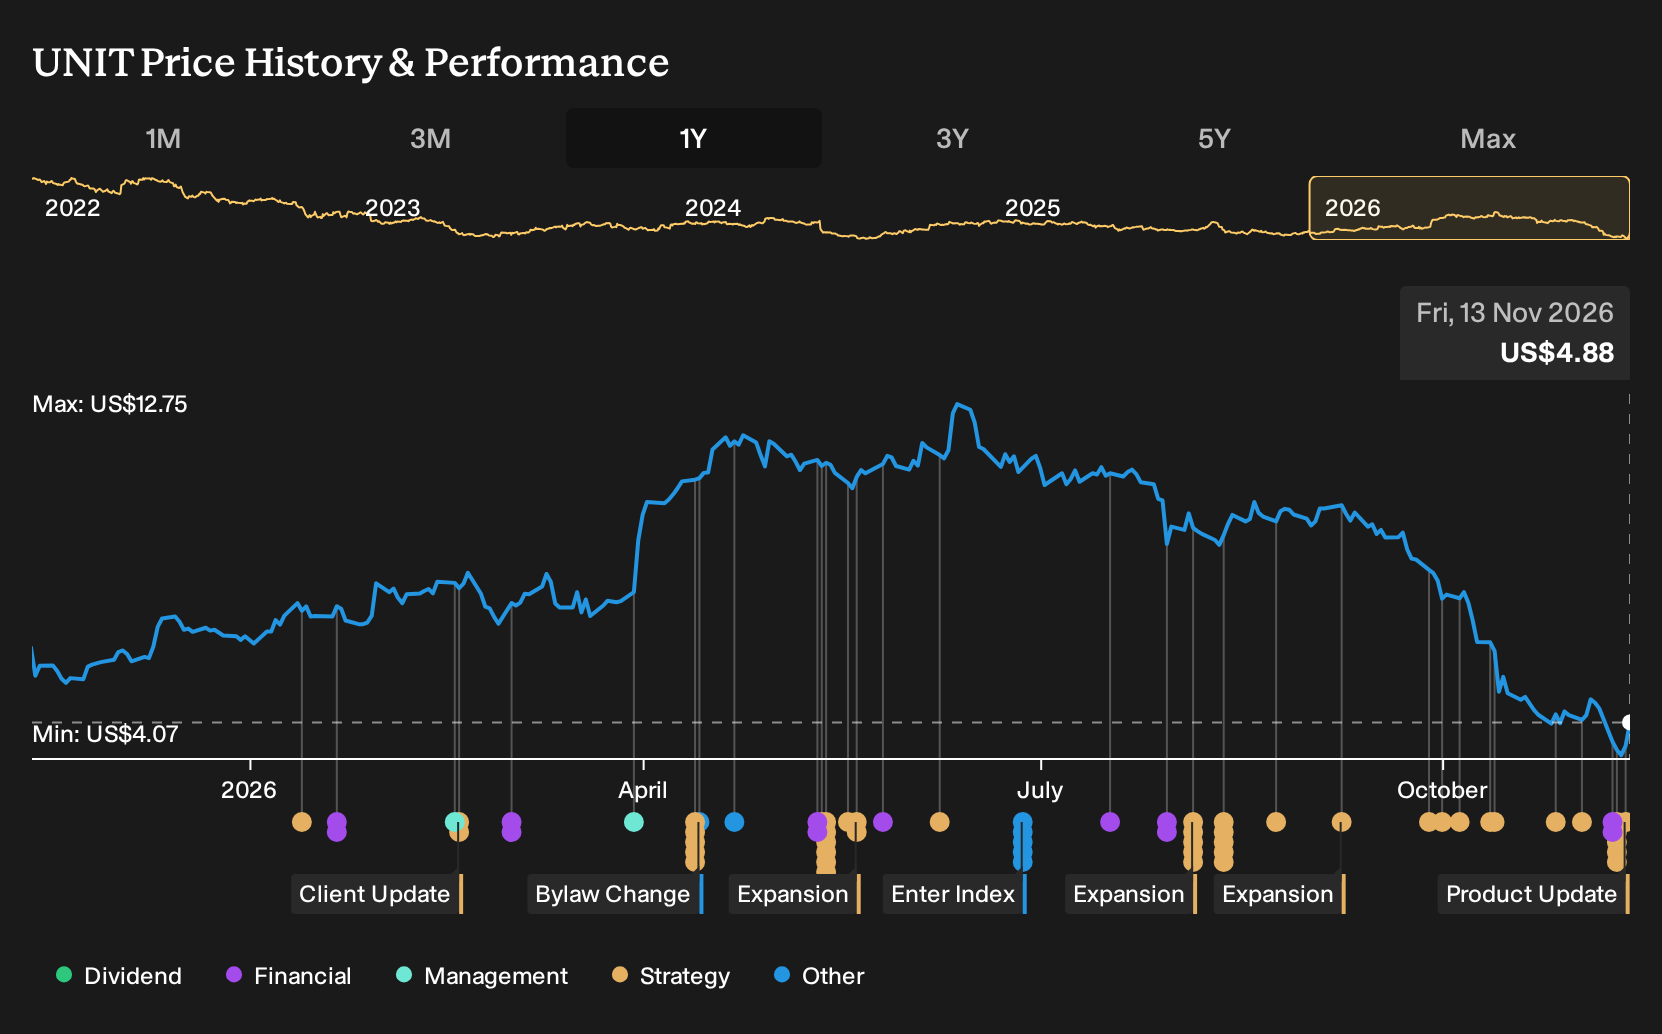
Uniti Group Stock Is Up 13.5% What's Changed In Fiber Expansion
- Uniti Group reported third quarter 2026 results that showed higher revenue alongside a sizeable net loss, while its Kinetic and wholesale units continued to build out fiber capacity, including an industry first 800 Gigabit Ethernet trial using a single fiber pair between Chicago and Lexington.
- The combination of large scale fiber expansion across multiple states and the single fiber pair 800GE trial highlights Uniti Group’s push to deepen high capacity, recurring connectivity services, even as heavy investment and leverage keep financial pressure elevated.
- The next area of focus will be how Uniti Group’s single fiber pair 800GE trial could reshape the investment narrative around its fiber build.
Scan how Uniti Group's fiber build compares with other high capacity networks by jumping across to a curated list of 53 AI infrastructure stocks that power the same data traffic surge.
Uniti Group Investment Narrative Recap
To be a shareholder in Uniti Group, an investor needs to believe the heavy fiber build, especially at Kinetic and in Fiber Infrastructure, can one day outweigh shrinking legacy services and current losses. The analyst consensus Narrative on Simply Wall St frames the thesis around growing recurring fiber revenue while keeping funding sources open enough to sustain high capital expenditure.
Recent third quarter numbers show higher revenue alongside a sizeable net loss and updated 2026 guidance that still points to a full year loss. That keeps the key near term catalyst tied to fiber lease up and bookings. The biggest immediate risk remains leverage and refinancing, rather than the operational announcements themselves.
The single fiber pair 800GE trial at Uniti Wholesale is the announcement most connected to this story. It points to a network that can support higher bandwidth services using Nokia’s 1830 GX platform, which matters if the firm wants to serve AI, cloud and large enterprise traffic on terms that justify its capital spend.
This kind of higher capacity handoff could intersect with the catalysts in the analyst consensus Narrative on Simply Wall St around AI driven dark fiber builds and record Fiber Infrastructure bookings. The operational proof point is positive for capability, although funding costs, asset monetization progress and execution on Kinetic’s large footprint still look like the elements that drive whether those potential contracts translate into better financial outcomes.
Uniti Group's narrative projects US$3.8b revenue and US$405.5m earnings by 2029. This assumes 1.3% yearly revenue growth and an earnings increase of about US$1.23b from current earnings of a US$828.2m loss.
Uncover why Uniti Group's fair value indicates a 98% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate narrative zooms in on funding risk rather than fiber capacity. The most cautious Uniti Group analysts were working off relatively flat revenue expectations of about US$3.7b and earnings of roughly US$332.1m by 2029, and saw limited P/E expansion. That view could shift if the 800G trial meaningfully reshapes future contracts.
Explore another Uniti Group fair value estimate, including one that suggests as much as 23% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Uniti Group research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Uniti Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Uniti Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Uniti Group?
If the Uniti Group story has you thinking about where fiber, data and cash flow strength intersect, it can help to widen the lens and compare it with other businesses facing very different capital and balance sheet trade offs.
- For investors who want a focus on financial resilience first, filter the market through a list of solid balance sheet and fundamentals (24 results) and see which companies pair conservative debt levels with robust fundamentals.
- If potential mispricing is your priority, scan a curated 34 high quality undervalued stocks and compare how their implied upside stacks against Uniti Group on your watchlist.
- If you prefer to keep risk contained while still staying in equities, then sort candidates using a 29 resilient stocks with low risk scores and line up their volatility and fundamentals against the fiber heavy profile you see here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com