


EN
How Investors May Respond To Ensign Group (ENSG) Systemic Neglect Lawsuit
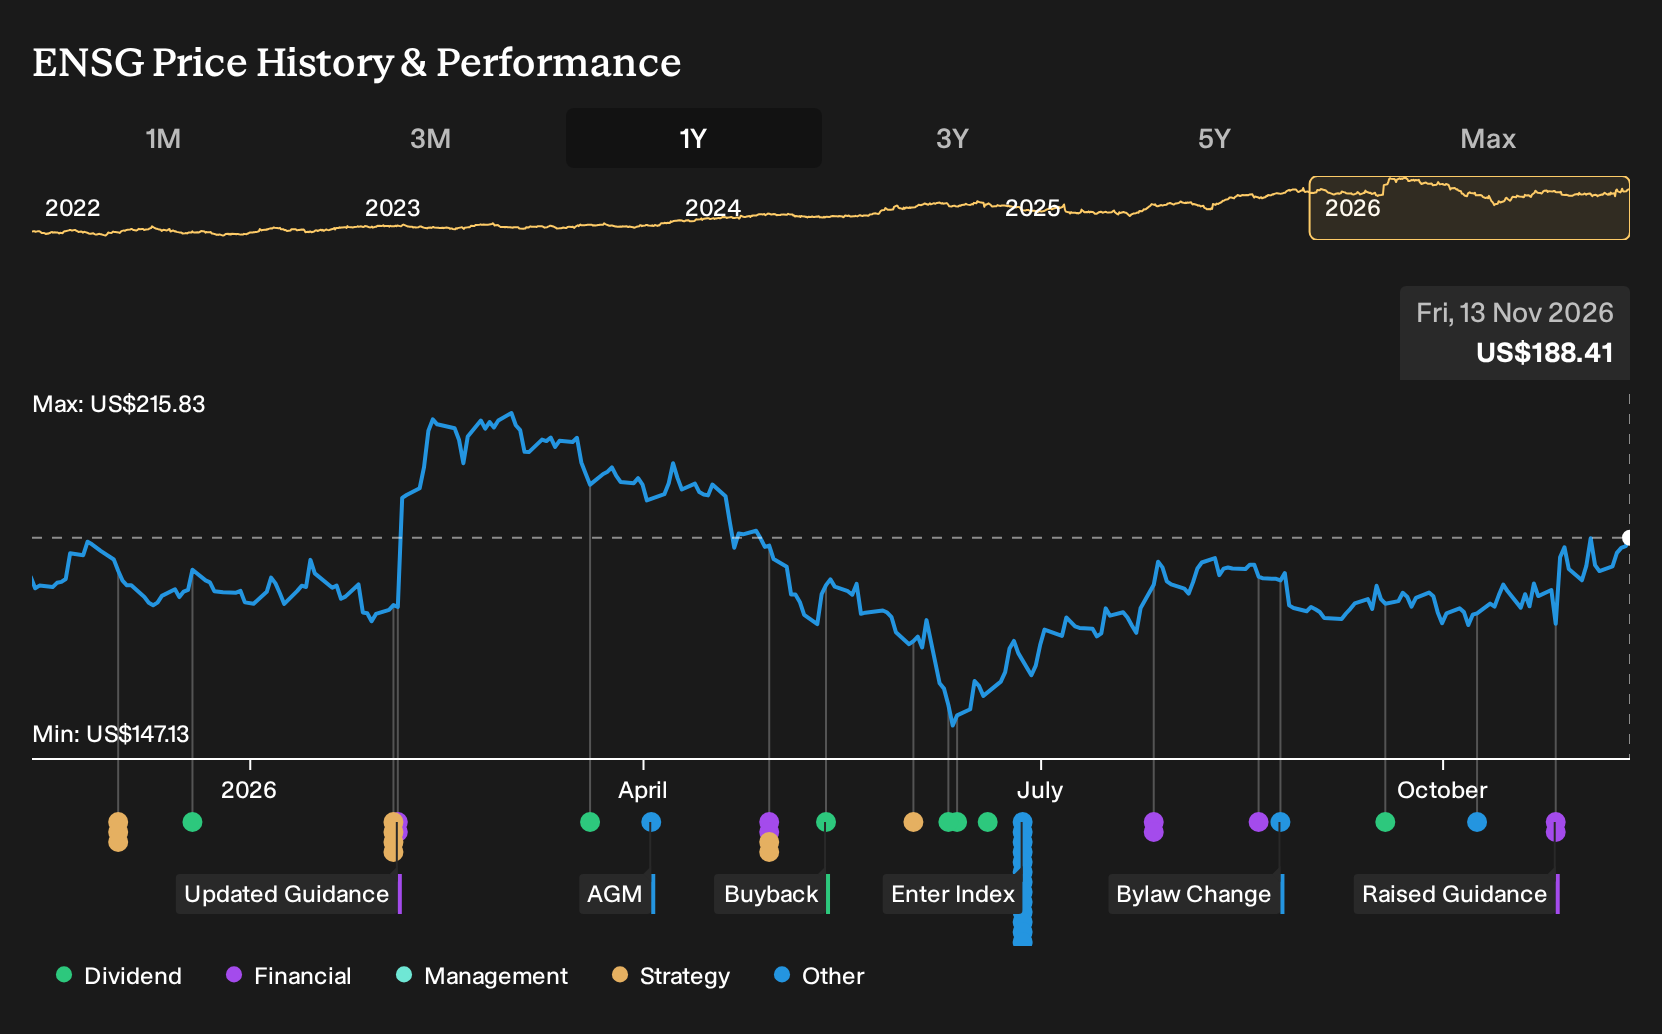
- Ensign Group is facing a securities class action in the Central District of California that alleges systemic neglect, falsified records and fraudulent Medicare and Medicaid practices across its care facilities, following a June 2026 media investigation.
- The lawsuit raises operational questions around care standards, compliance processes and documentation controls that sit directly against Ensign Group’s core model of managing a broad portfolio of post acute and senior care operations.
- We now examine how Ensign Group’s broader investment narrative could be affected by the alleged systemic neglect and documentation failures.
Ensign Group Investment Narrative Recap
To own Ensign Group, you have to buy into a large operator that leans on scale, clinical depth and government reimbursement to fill skilled nursing and senior care facilities. The analyst consensus narrative on Simply Wall St leans on ageing demographics and a pipeline of clinically challenged sites that could support occupancy and EBIT over time. The class action around alleged neglect and falsified records now sits in the middle of that care quality story and introduces near term uncertainty around surveys, referrals and staffing focus.
The biggest near term catalyst many investors watch is how effectively Ensign Group can lift underperforming acquisitions and keep CMS quality metrics high enough to sustain higher acuity referrals and managed care relationships. The lawsuit cuts close to that by questioning documentation, compliance and on the ground leadership, which were central supports in the prior thesis. Regulatory attention or tighter oversight could slow the pace or economics of further facility turnarounds and might shift management capacity from expansion to remediation work.
Among the recent references, the reminder from ClaimsFiler on November 14, 2026 that investors have until December 7, 2026 to seek lead plaintiff status in Perusek v. The Ensign Group, Inc. is the most relevant for the near term story. This timeline keeps the alleged neglect, abuse and reporting issues prominent for both regulators and capital providers. It also extends the period in which new information could emerge through filings and court submissions.
For you as a shareholder or potential investor, that matters directly to the operational narrative built around strong CMS scores, low rehospitalization rates and tight documentation that support referrals and reimbursement. It also intersects with Ensign Group’s reliance on Medicare and Medicaid, since any finding that affects billing practices could feed into funding discussions. Analyst commentary about earnings growth and P/E multiples remains secondary to how convincingly the business can evidence care standards, data integrity and local leadership depth while this litigation unfolds.
Ensign Group's current set of analyst expectations points to revenues of US$7.9b and earnings of US$601.1m by 2029. These projections are based on 11.5% yearly revenue growth and an earnings increase of about US$202m from the current US$399.1m level.
Uncover why Ensign Group's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about US$161 and US$226, which shows how far opinions on Ensign Group can stretch. Those crowd estimates pre date the class action disclosures and ongoing reliance on Medicare and Medicaid funding, so you should treat them as one input and actively seek out alternative angles.
Explore 2 other Ensign Group fair value estimates, including one that suggests as much as 20% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ensign Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Ensign Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ensign Group's overall financial health at a glance.
Looking for more investment ideas beyond Ensign Group?
If this Ensign Group story has you thinking harder about risk, quality and where you want your capital working, the next step is to widen your watchlist using the Simply Wall St Screener.
- Focus on resilience first and returns second by scanning a curated set of 29 resilient stocks with low risk scores that may better fit a cautious approach.
- If you want to lean into quality and balance sheet strength, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stressing the finances.
- For investors hunting for underfollowed ideas with room for the story to develop, the 19 high quality undiscovered gems can surface lesser known businesses with stronger fundamentals than their profile suggests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com