


EN
ICON (ICLR) Rebounds On Undervalued Narrative, Is The P E Premium Too Rich?
ICON (ICLR) has drawn fresh attention after recent share price moves, with the stock closing at $194.65. Investors are weighing this clinical research specialist’s returns over the past month and the past 3 months.
Recent momentum for ICON has cooled slightly, with the 1-day share price return down 2.92% and the 7-day share price return down 4.93%. Even so, the 30-day and 90-day share price returns of 14.38% and 14.87% suggest buyers have been more active in recent weeks. The 1-year total shareholder return of 20.02% contrasts with weaker 3 and 5-year total shareholder returns, where compounding losses of 27.89% and 31.99% show that longer term holders have had a rougher ride.
Scan how ICON fits alongside other outsourced research players and compare its recent swing with a curated list of 36 healthcare AI stocks.
Bulls see ICON’s recent rebound as the market rediscovering a solid clinical research franchise. Bears see a value trap after years of weaker long term returns. Which case do the current valuation markers support?
Most Popular Narrative: 16% Undervalued
ICON’s last close at $194.65 sits below the analyst consensus Narrative fair value of $231.29, which is built using a 9.14% discount rate and long term revenue and earnings forecasts from the analyst consensus Narrative on Simply Wall St.
The main factor that has to go right is that ICON converts strong net book-to-bill momentum and new AI and lab investments into healthier direct fee growth and a gradual rebuild of adjusted EBITDA margins, despite mix pressure from pass-throughs and FSP work.
The current valuation suggests the market is treating ICON as fairly valued, with a cautious but constructive view that accounting issues are contained, capital returns via buybacks will resume, and AI and capacity investments can support earnings over time.
Find out how 13 investors see ICON as 16% undervalued.
Result: Fair Value of $231.29 (UNDERVALUED)
Still, the ICON story can break if margin pressure from pass through work persists, or if governance concerns linger after the accounting investigation shock.
Find out about the key risks to this ICON narrative.
Another View: ICON Through The P/E Lens
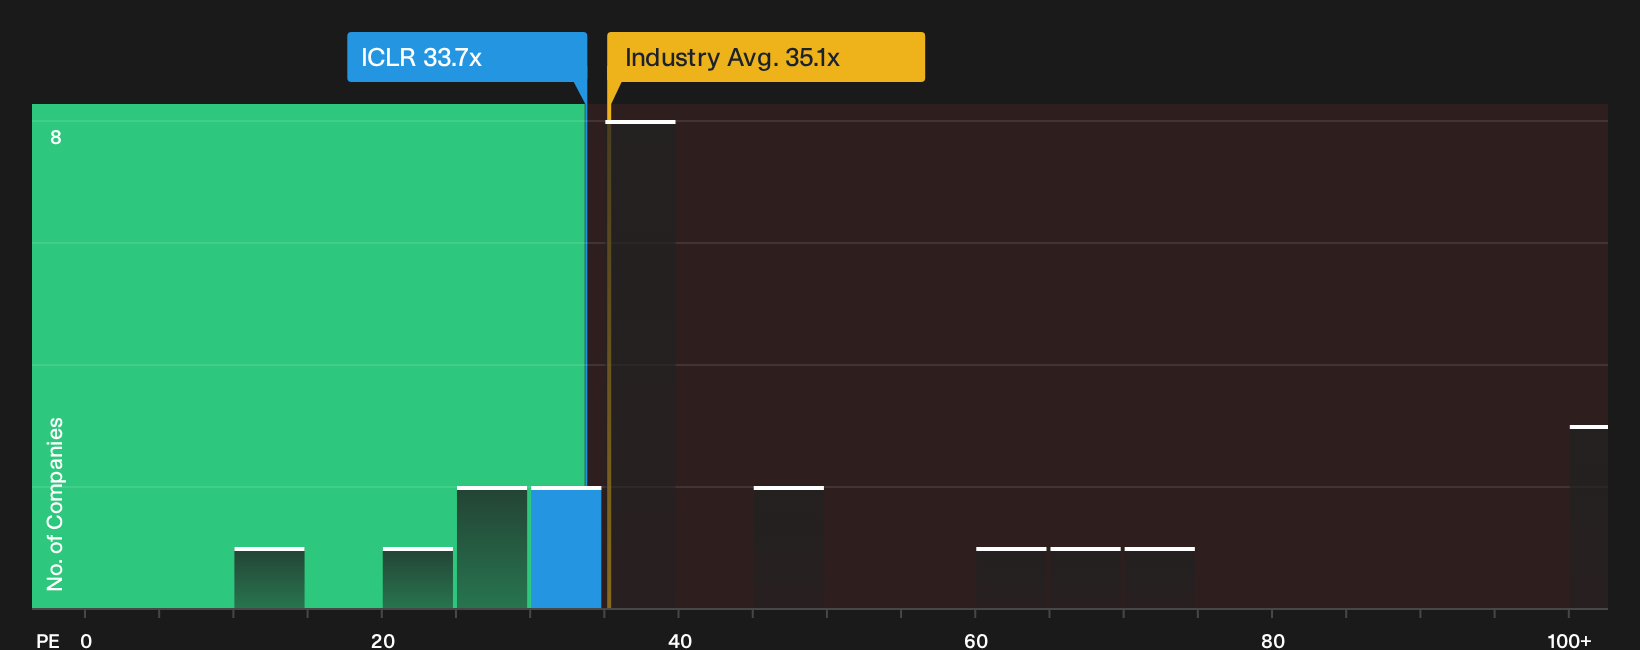
The first take paints ICON as undervalued on future cash flows, yet the P/E picture is less generous. The stock trades on 33.7x earnings versus a fair ratio of 28.2x and peer averages of 35.1x globally and 43.9x for its closest group. That gap lowers the margin for error if growth or margins slip. Which yardstick do you trust more when real money is on the line?
To pressure test this earnings based view against the cash flow story, review how the numbers stack up in the valuation breakdown, then judge whether that extra P/E premium feels comfortable for your own risk tolerance. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around ICON are clear, which is exactly why you should scan the data, weigh both sides, and then decide whether the balance of 3 key rewards and 2 important warning signs.
Ready For More Ideas Beyond ICON?
ICON’s mixed signals make this a smart moment to widen the net and stress test your portfolio against other clear, data backed opportunities on Simply Wall St.
- Target resilient compounding potential by scanning companies that pair strong fundamentals with manageable leverage through a focused list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities where quality and valuation collide by running a curated sweep across a 19 high quality undiscovered gems.
- Secure potential income streams while you wait for price moves by checking which companies stack up as 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com