


EN
3 Canadian Uranium Stocks With Earnings Growth Over 37%
Europe’s push to electrify its economy has hit a reality check as wind and solar struggle with seasonal swings and aging grids, which keeps reliable nuclear power in the spotlight. For Canadian investors, that puts homegrown nuclear energy stocks in a different light. This article walks through three of the most interesting nuclear opportunities from our Canada focused screener and how they might fit into a long term portfolio story.
The three stocks highlighted here offer a compelling starting point if you want exposure to uranium producers and reactor focused nuclear energy businesses that anchor reliable baseload power. However, if you want the standouts, these 17 nuclear renaissance stocks are the most outstanding.
Cameco (TSX:CCO)
Cameco is a heavyweight in the nuclear fuel chain, supplying uranium for power plants while also running Fuel Services and the Westinghouse reactor technology business. Recent figures show about CA$2.9b from Uranium, CA$555 million from Fuel Services and CA$3.6b from Westinghouse, with a market value around CA$43.9b.
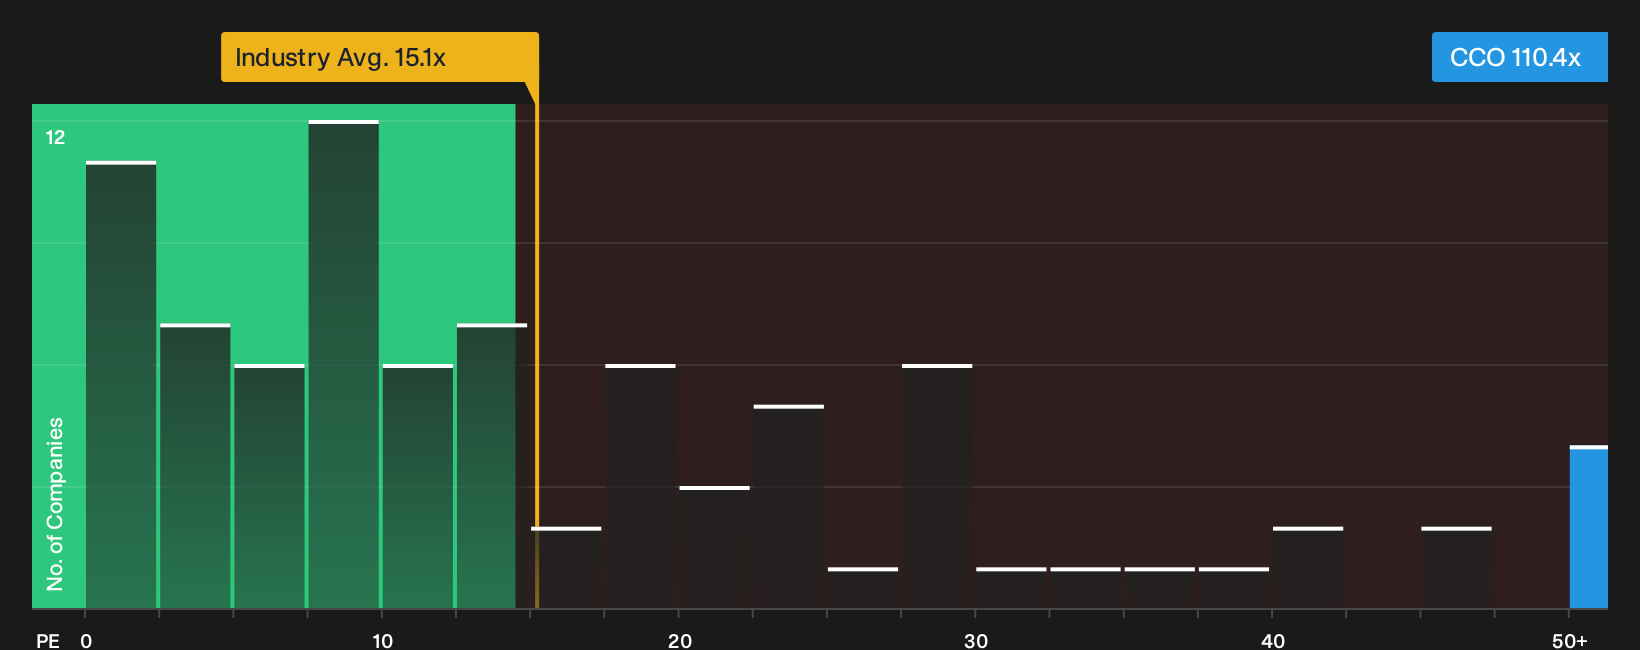
Cameco provides exposure to uranium mining, fuel processing and reactor services in one package. This aligns with a nuclear energy theme built around reliable baseload power. The stock trades on a rich P/E, and recent production issues have drawn attention to how tight the margin for error can be if a single key assumption breaks.
If that tight margin of error worries you, the Cameco financial health report shows where Cameco’s balance sheet strength might absorb a shock before it hits investors.
NexGen Energy (TSX:NXE)
NexGen Energy is a pure-play uranium explorer and developer, owning 100% of the Rook I project in Saskatchewan’s Athabasca Basin. This project anchors its role in the nuclear fuel supply chain. As a pre-revenue developer, it is valued at about CA$7.6b.
NexGen Energy provides direct exposure to potential future uranium supply for nuclear power. However, it is still pre-production, currently loss-making and funded by external capital. Interest in the company centers on how a single long-cycle uranium project, with its financing and development pressures, ultimately affects shareholders.
That single project pressure is exactly why many investors start with the analysis report for NexGen Energy to see what might accelerate or stall NexGen Energy from here.

Energy Fuels (TSX:EFR)
Energy Fuels is a rare mix of uranium supplier and critical minerals producer, with its CA$2.5b market value anchored by about US$116.8 million of uranium revenue that directly serves nuclear power customers, supported by additional rare earth, vanadium and heavy mineral sands activity.
The analyst consensus Narrative on Simply Wall St frames Energy Fuels as a way to tap directly into nuclear fuel demand through uranium production, while also tying that uranium cash engine to a broader build out in rare earths and related materials.
"Ramp up of high grade, low cost uranium production at Energy Fuels, supported by industry low production costs of about US$23 per pound and significant licensed capacity at the White Mesa Mill, has the potential to widen gross margins and support future earnings as more volumes are sold."
What really tests that potential is how one capital intensive expansion plan and its funding needs influence the eventual earnings power investors care about.
That trade off is exactly what the full narrative for Energy Fuels unpacks, separating short term noise from how Energy Fuels’ uranium and critical minerals plans could reshape its long run profile.

Curious About Alternatives You Might Be Missing?
Fresh themes keep breaking out while older stories lose momentum fast. Scan new ideas before the crowd, while they are still under the radar for now, and consider getting in at an earlier stage.
- Spot potential turnaround stories with solid finances by running the 6 high quality undervalued stocks before renewed interest changes valuations and the easier entry points are gone.
- Explore structural shifts in healthcare by scanning 7 healthcare AI stocks while these platforms are still building traction and pricing has not fully reflected the trend.
- Track the next wave of automation-focused companies through the 88 robotics and automation stocks and evaluate them before industrial demand and AI-related developments are fully reflected in prices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com