


EN
Free Cash Flow Strength Might Change The Case For Investing In KLA Stock (KLAC)
- KLA Corporation recently filed a US$229.8m shelf registration tied to an employee stock ownership plan and affirmed a US$0.23 quarterly dividend, payable on 1 December 2026 to holders of record on 16 November 2026.
- The combination of ESOP related share issuance capacity and steady cash dividends reflects KLA’s focus on employee alignment and capital returns alongside free cash flow.
- We will now look at how KLA’s record free cash flow and ESOP focused shelf registration shape the broader investment narrative.
KLA Investment Narrative Recap
For KLA, the core belief is simple. You need to think AI driven wafer equipment demand and rising process control intensity can support ongoing use of its US$12.5b backlog and keep free cash flow robust. The ESOP shelf registration and affirmed dividend do not materially change that operating picture or the near term focus on converting high margin systems and services.
The biggest near term swing factor remains customer equipment spending on advanced nodes, HBM and packaging, which ties directly into that backlog. The main risk stays on the cost and policy side, where tariffs, higher DRAM prices and China exposure can pressure margins or limit how much of that booked demand turns into earnings.
The analyst consensus Narrative on Simply Wall St highlights KLA’s role in AI infrastructure and its very high share in process control. In that context, the most relevant fresh data point is the company’s recent US$1.34b free cash flow in fiscal Q1 2027, which arrived above revenue guidance and underlines the cash generation behind those capital decisions.
That FCF performance matters for catalysts because it supports continued dividends, buybacks and balance sheet strength while KLA works through long dated orders into 2027 and 2028. It also frames the current shelf registration and dividend affirmation as operationally supported choices, while investors still need to weigh backlog execution, export restrictions and input cost headwinds as live execution risks.
KLA's current analyst framework points to forecast revenue of US$26.2b and earnings of US$11.1b by 2029, based on an assumed 21.9% yearly rise in revenue and an earnings increase of about US$5.8b from US$5.3b today.
Uncover why KLA's fair value indicates a 44% potential upside to its current price, which could narrow quickly.
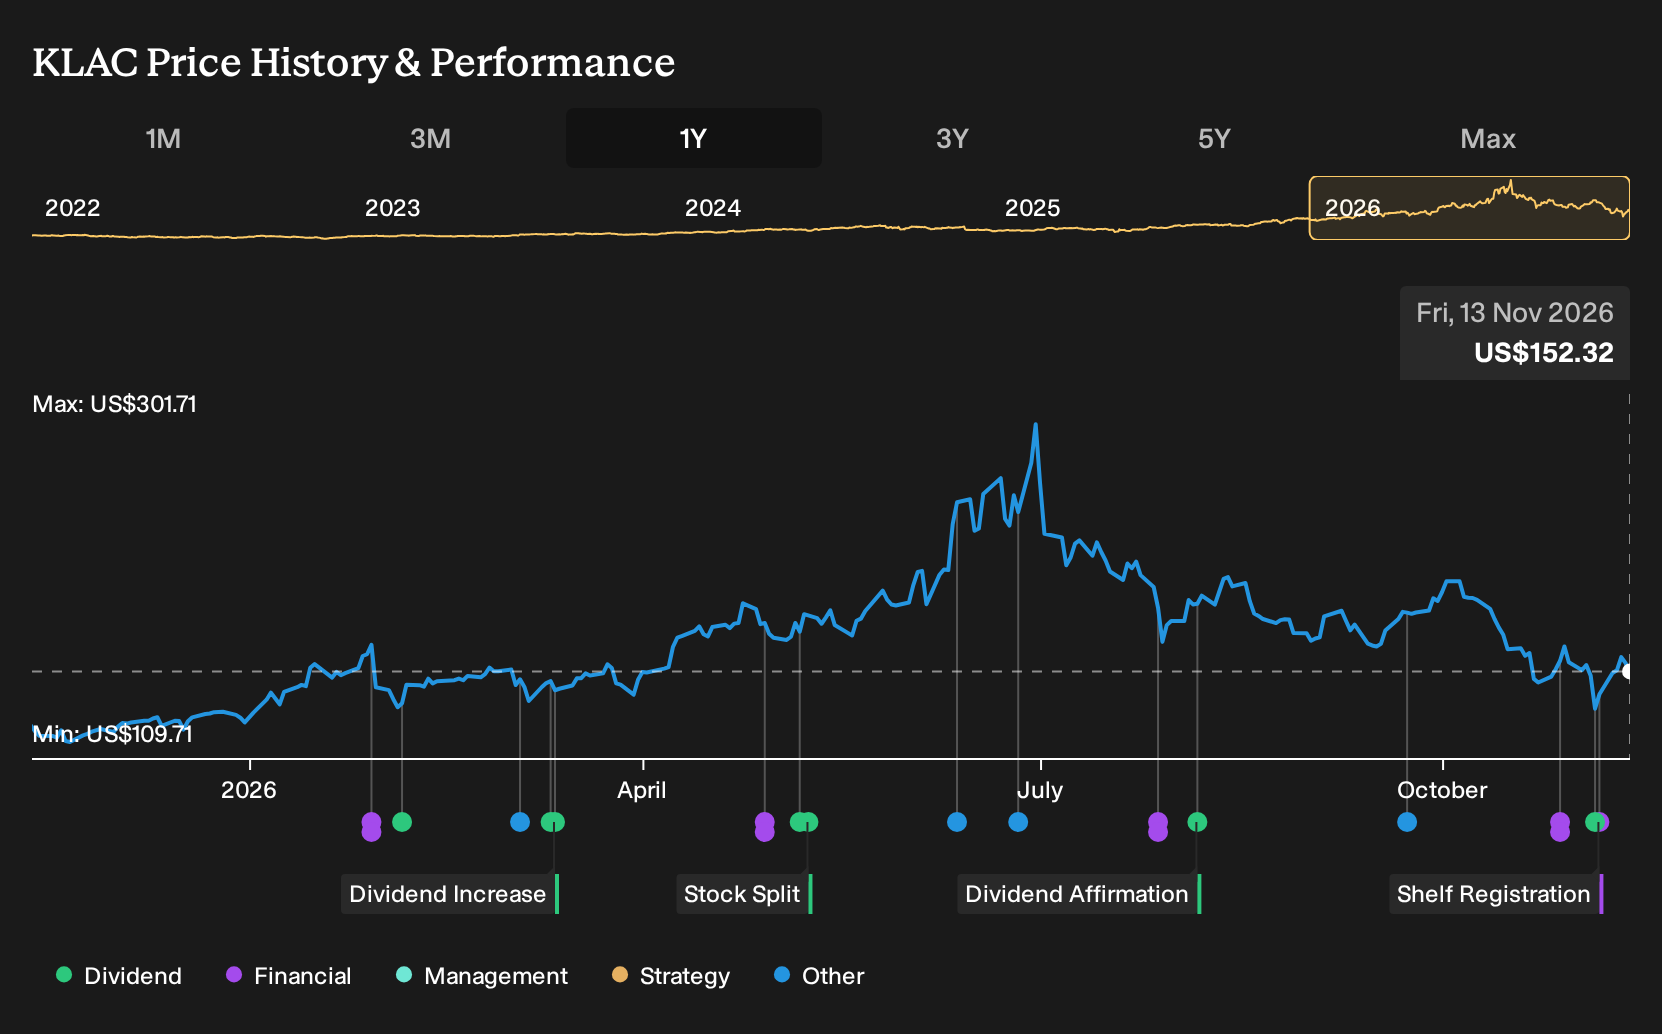
Exploring Other Perspectives
Some of the lowest ranked analysts focus on margin pressure rather than KLA’s backlog. They worry tariffs and component costs could keep profitability tight, which is why their 2029 earnings view sits closer to US$9.4b on about US$23.5b of revenue. Those forecasts, set before this ESOP shelf and dividend news, may shift.
Explore 5 other KLA fair value estimates, including one that suggests as much as 38% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your KLA research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for KLA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KLA's overall financial health at a glance.
Looking For More Investment Ideas Beyond KLA?
If KLA has sharpened your interest in AI infrastructure and strong cash generation, it can help to widen the lens and see what else fits your criteria. The Simply Wall St Screener lets you quickly filter for businesses with balance sheets, income statements and cash profiles that match the way you like to invest.
- For investors who care most about financial resilience and clean accounts, start with a list of solid balance sheet and fundamentals (24 results) that combine prudent leverage with consistent fundamentals.
- If steadier income is your priority, scan a curated set of 6 dividend fortresses that pair higher yields with supporting cash flows.
- Hunting for mispriced opportunities instead, focus on a 34 high quality undervalued stocks where quality metrics and current pricing look out of sync.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com