


EN
Should Higher Nine Month Earnings Require Action From Ezaki Glico Stock Investors?
- Ezaki Glico reported earnings for the nine months ended September 30, 2026, with sales of JPY 281,008 million and net income of JPY 7,719 million, both above the prior year period.
- The higher basic earnings per share from continuing operations, at JPY 124.96 versus JPY 114.18 a year earlier, indicates improved profitability per share.
- Attention now turns to how Ezaki Glico's higher nine month earnings per share might influence the broader investment narrative around the business.
Compare Ezaki Glico's earnings story with other consumer-focused stocks by reviewing our hand picked list of 72 high quality undiscovered gems in similar pockets of the market.
What Is Ezaki Glico's Investment Narrative?
To own Ezaki Glico, you need to be comfortable with a food group that leans on a broad brand portfolio and incremental execution rather than big swings. The latest nine month figures, with sales of ¥281,008 million and net income of ¥7,719 million, point to demand that still supports the business model, even as net profit margins remain low and sensitive to input costs and pricing decisions. For the short term, the key swing factors look more operational than related to financial structure, such as how effectively Ezaki Glico manages product mix, promotion, and overseas expansion across its six reporting segments.
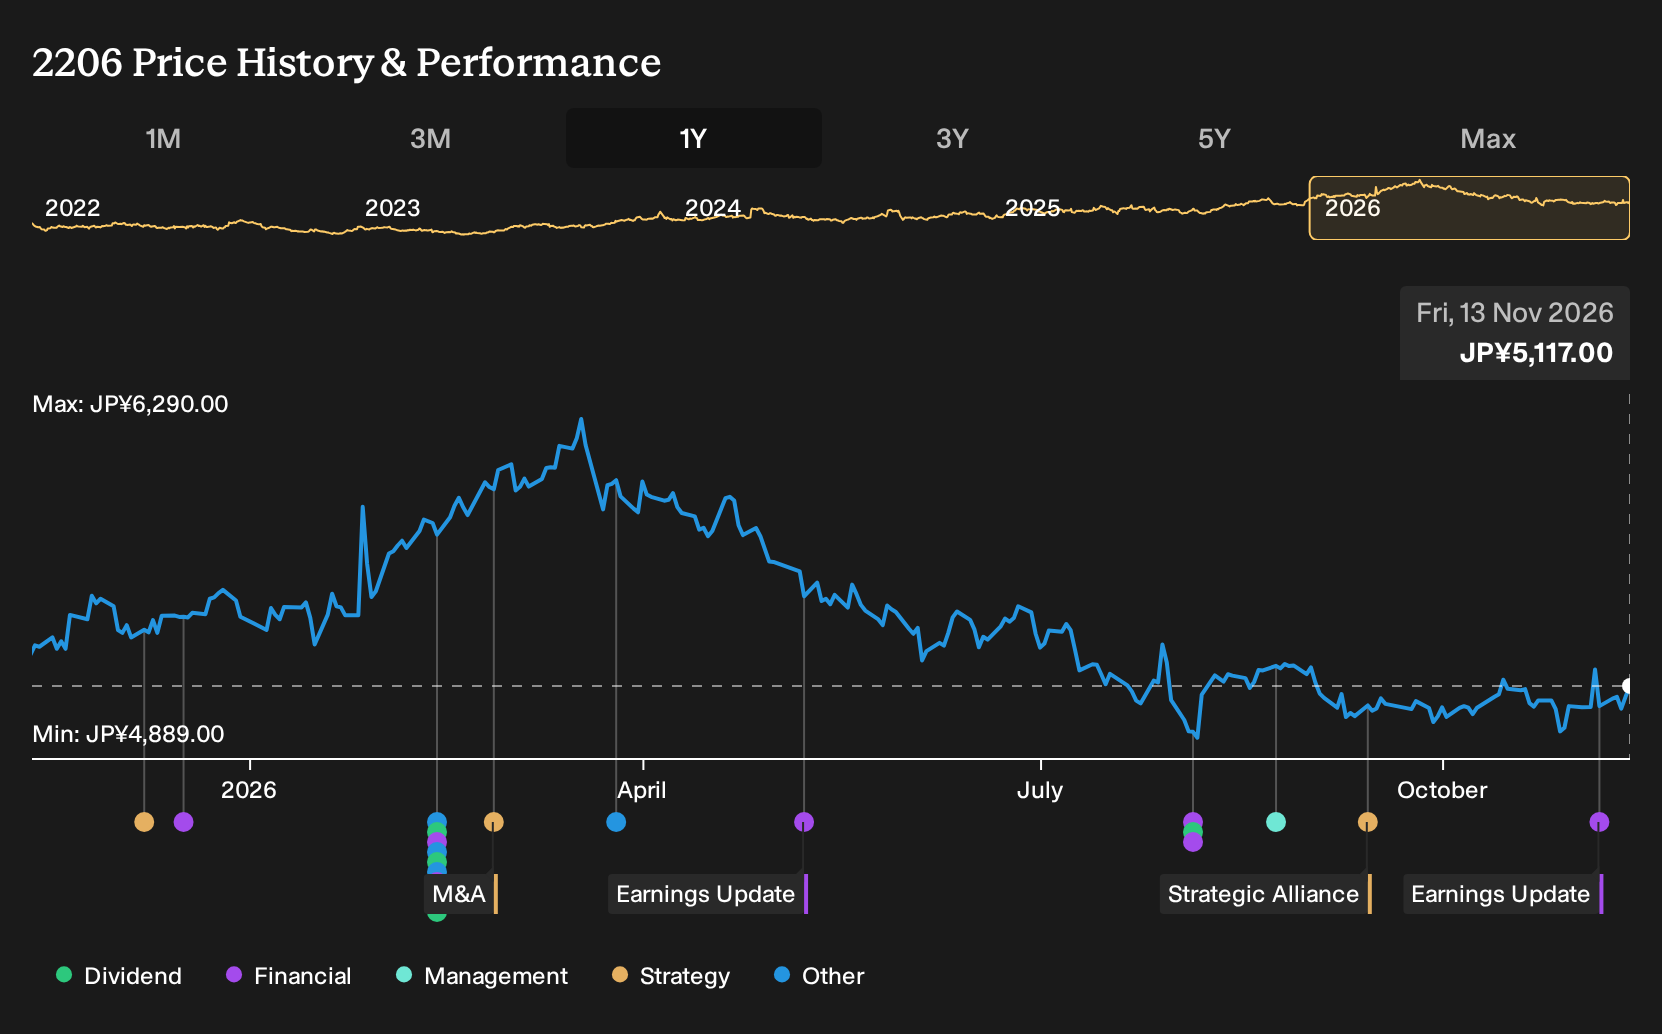
The higher basic earnings per share at ¥124.96 from continuing operations fits into a story where forecasts still point to faster earnings growth than the wider JP market, even though forecast revenue growth is slower and the current P/E of 55.4x is high compared with both industry and peer averages. That mix of expected profit improvement and expensive multiples makes execution in areas such as overseas growth, cost control and product innovation especially important, because any stumble risks being punished in a stock that has already lagged the JP market over the past year.
Yet there is a wrinkle in the Ezaki Glico story once you factor in how its recent one off items and funding profile interact with ...
There's only one way to know the right time to buy, sell or hold Ezaki Glico. Head to Simply Wall St's company report for the latest analysis of Ezaki Glico's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ezaki Glico research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ezaki Glico. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ezaki Glico's overall financial health at a glance.
Looking For More Ideas Beyond Ezaki Glico?
If Ezaki Glico's latest earnings have sharpened your appetite for opportunities, it can help to line it up against a broader watchlist. The Simply Wall St Screener lets you filter for different angles so you can see where Ezaki Glico fits within a wider set of potential investments.
- If you prefer resilient balance sheets and steadier fundamentals over headline excitement, then start with a focused list of solid balance sheet and fundamentals (24 results) that already clear a basic quality bar.
- If value is the lens you trust most, compare Ezaki Glico with a pool of 18 high quality undervalued stocks that screen well on both quality and pricing.
- For investors who care most about capital preservation and fewer surprises, narrow your search to a group of 19 resilient stocks with low risk scores that score well on risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com