


EN
Ultra Clean Holdings (UCTT) Could Be 59% Undervalued On Strong Q3 Results
Leadership shifts and mixed signals around Ultra Clean Holdings
Ultra Clean Holdings (UCTT) has been in focus after solid third quarter 2026 results, followed almost immediately by an analyst downgrade to SELL that cut against management’s upbeat AI driven capital equipment narrative.
Those headlines arrived alongside fresh leadership moves. The business elevated Brian Harding to Senior Vice President, Finance, with a brief that includes global financial planning, decision support, and the use of artificial intelligence and data analytics within the finance function.
The share price tells the story of that clash of opinions. Ultra Clean Holdings is trading at US$46.35, with the stock up 69.66% on a year to date share price basis but giving back ground recently with a 9.12% decline over 30 days and a much steeper 47.26% pullback across 90 days. Even so, the 1 year total shareholder return of 93.93% and 3 year total shareholder return of 76.57% keep the longer term record in positive territory.
Contrast Ultra Clean Holdings with other potential AI infrastructure beneficiaries and scan a hand-picked set of 53 AI infrastructure stocks that may be riding similar spending cycles.
Ultra Clean Holdings now trades at a steep discount to the average analyst target, yet it has also dropped sharply in recent months. Where does a reasonable estimate of fair value actually land within that range?
Most Popular Narrative: 59% Undervalued
On the analyst consensus Narrative on Simply Wall St, Ultra Clean Holdings screens as materially undervalued, with a fair value of $112.83 against the latest $46.35 close. This puts the focus squarely on whether the market is underestimating its capacity build out.
The main thing that has to go right is Ultra Clean Holdings successfully scaling its global manufacturing footprint and UCT 3.0 co-innovation model so that higher industry wafer fab equipment spending and new fab ramps translate into sustainable revenue and margin gains.
See why 23 investors see Ultra Clean Holdings as 59% undervalued.
Result: Fair Value of $112.83 (UNDERVALUED)
Still, the bullish Ultra Clean Holdings story can break if extended negative operating cash flow squeezes investment plans, or if sector wide multiple compression persists despite delivery on earnings targets.
Find out about the key risks to this Ultra Clean Holdings narrative.
Another View: Ultra Clean Holdings Through The P/E Lens
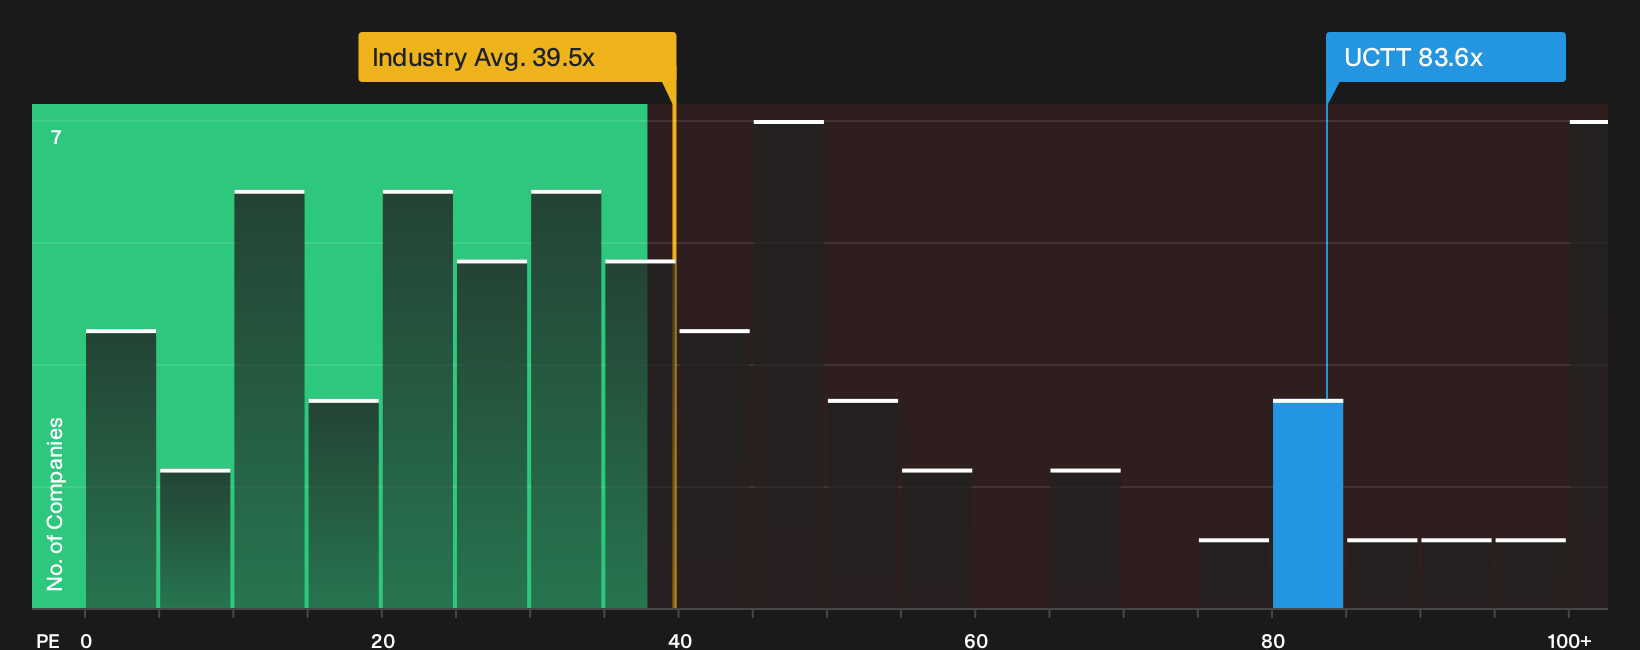
That $112.83 fair value hinges on analyst forecasts and a narrative of capacity catching up with AI demand. On simple P/E maths though, Ultra Clean Holdings looks expensive. The shares trade on 83.6x earnings versus a 39.4x US semiconductor average and a 45x fair ratio that the market could gravitate toward over time.
If earnings play out closer to the consensus narrative, that gap could compress without much fanfare. If forecasts slip or sentiment cools, the same spread can magnify downside risk far faster than many holders expect.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or just healthy debate around Ultra Clean Holdings: either way, the next move depends on how you weigh the data on both sides. Move quickly, review the full picture, and then decide where you stand after checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ultra Clean Holdings?
If Ultra Clean Holdings has sharpened your thinking about AI and capital equipment, do not stop there. Fresh ideas often show up where expectations are still muted.
- Target dependable cash generators by reviewing a list of solid balance sheet and fundamentals (24 results) that pairs healthier finances with cleaner fundamentals.
- Hunt for potential mispricing by scanning a focused 19 high quality undiscovered gems that filters for quality businesses sitting off most investors' radar.
- Prioritise sleep at night holdings and work through a 29 resilient stocks with low risk scores that screens for steadier return profiles and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com