


EN
Pilgrim's Pride (PPC) Tests Its Prepared Foods Story As Undervalued Case Faces Margin Risks
Pilgrim's Pride (PPC) is back in focus after recent commentary spotlighted its growing prepared foods portfolio, including the Just Bare brand, as well as its sensitivity to feed costs and global poultry pricing.
Pilgrim's Pride shares trade at US$28.12 after a 1-day share price return of 3.19%. However, the year-to-date share price return has fallen 29.47%, while the 3-year total shareholder return of 27.52% and 5-year total shareholder return of 16.02% point to a mixed picture where recent momentum has faded compared with longer term holders’ experience.
Scan beyond Pilgrim's Pride and compare its setup with hand-picked protein and food producers in the 34 high quality undervalued stocks that pair balance sheet strength with cash flow support.
Pilgrim's Pride looks like a solid protein producer with a broader prepared foods footprint, yet the share price slide tells a different story. Is that recent weakness a fair reflection of what investors get at US$28.12?
Most Popular Narrative: 16% Undervalued
Pilgrim's Pride closed at $28.12 compared with a narrative fair value of $33.29, which suggests upside according to the analyst consensus Narrative on Simply Wall St that ties together earnings forecasts, margins and capital spending plans.
The heavy capex cycle focused on case-ready conversions, deboning and portioning upgrades, a new prepared foods plant and European network optimization is aimed at improving yields and labor efficiency. This can support structurally higher operating margins and cash generation once larger projects move from build phase to full production.
See why 19 investors see Pilgrim's Pride as 16% undervalued.
Result: Fair Value of $33.29 (UNDERVALUED)
Still, if elevated U.S. chicken supply keeps pricing subdued or Mexico’s weaker margins persist, the Pilgrim's Pride capex and prepared foods story could stall.
Find out about the key risks to this Pilgrim's Pride narrative.
Another View: Pilgrim's Pride On Earnings Multiples
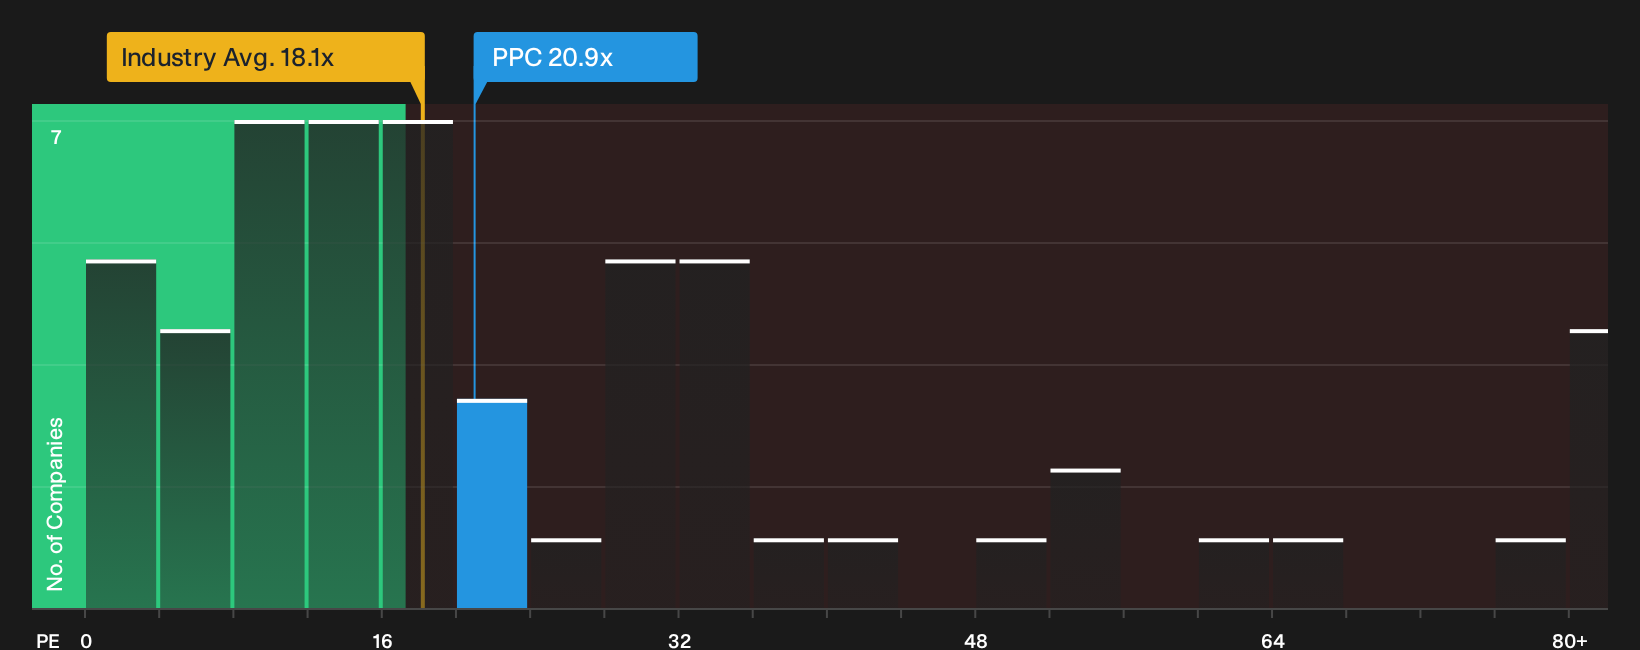
The analyst narrative leans on future earnings power to say Pilgrim's Pride looks 16% undervalued at $33.29 fair value. On current numbers, the picture is less forgiving. PPC trades on a P/E of 20.9x, richer than both the US Food industry at 18.1x and the peer average of 15.6x.
The Simply Wall St fair ratio of 37.4x implies the market could move toward a much higher earnings multiple over time. However, paying above sector and peer levels today raises the risk that weaker margins or slower progress in prepared foods leave little room for error. When you consider your own assumptions, which story do you trust more: the higher fair ratio or the cheaper peer group?
See what the numbers say about this price, find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split between risks and rewards around Pilgrim's Pride feels finely balanced, treat that as your cue to look under the hood yourself and move quickly while sentiment is still mixed. Start by weighing the 1 key reward and 3 important warning signs.
Looking for more ideas beyond Pilgrim's Pride?
You have seen how nuanced Pilgrim's Pride looks. Now widen your opportunity set with focused screeners that surface very different types of potential setups.
- Target high potential smaller names that still clear quality hurdles by scanning the 13 elite penny stocks with strong financials and see which ones earn a closer look.
- Zero in on stronger balance sheets that can better absorb shocks by reviewing the list of solid balance sheet and fundamentals (24 results) before fresh money goes to work.
- Hunt for future market leaders that are not yet widely followed by running the 19 high quality undiscovered gems so promising stories do not slip past you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com