


EN
3 Defense Stocks Backed By Rising Global Security Spending
Global defense and security spending is being rewired in real time, with governments channeling trillions toward hard protection, digital safeguards and critical infrastructure. That scale of capital can reshape entire sectors, which means ignoring it could be costly for your portfolio. This article walks through three stocks from our Global Defense and Security Contractors screener that appear well placed in light of recent news and explains why their exposure matters to you.
The stocks covered below are just a small sample, and the full Global Defense and Security Contractors screen surfaced 41 more large, liquid businesses with equally compelling stories that are not included in this article. Head straight into the Global Defense and Security Contractors screener to identify potential leaders, analyze fundamentals, and focus on the defense and security contractors that best fit your own risk and return preferences.
Embraer (BOVESPA:EMBJ3)
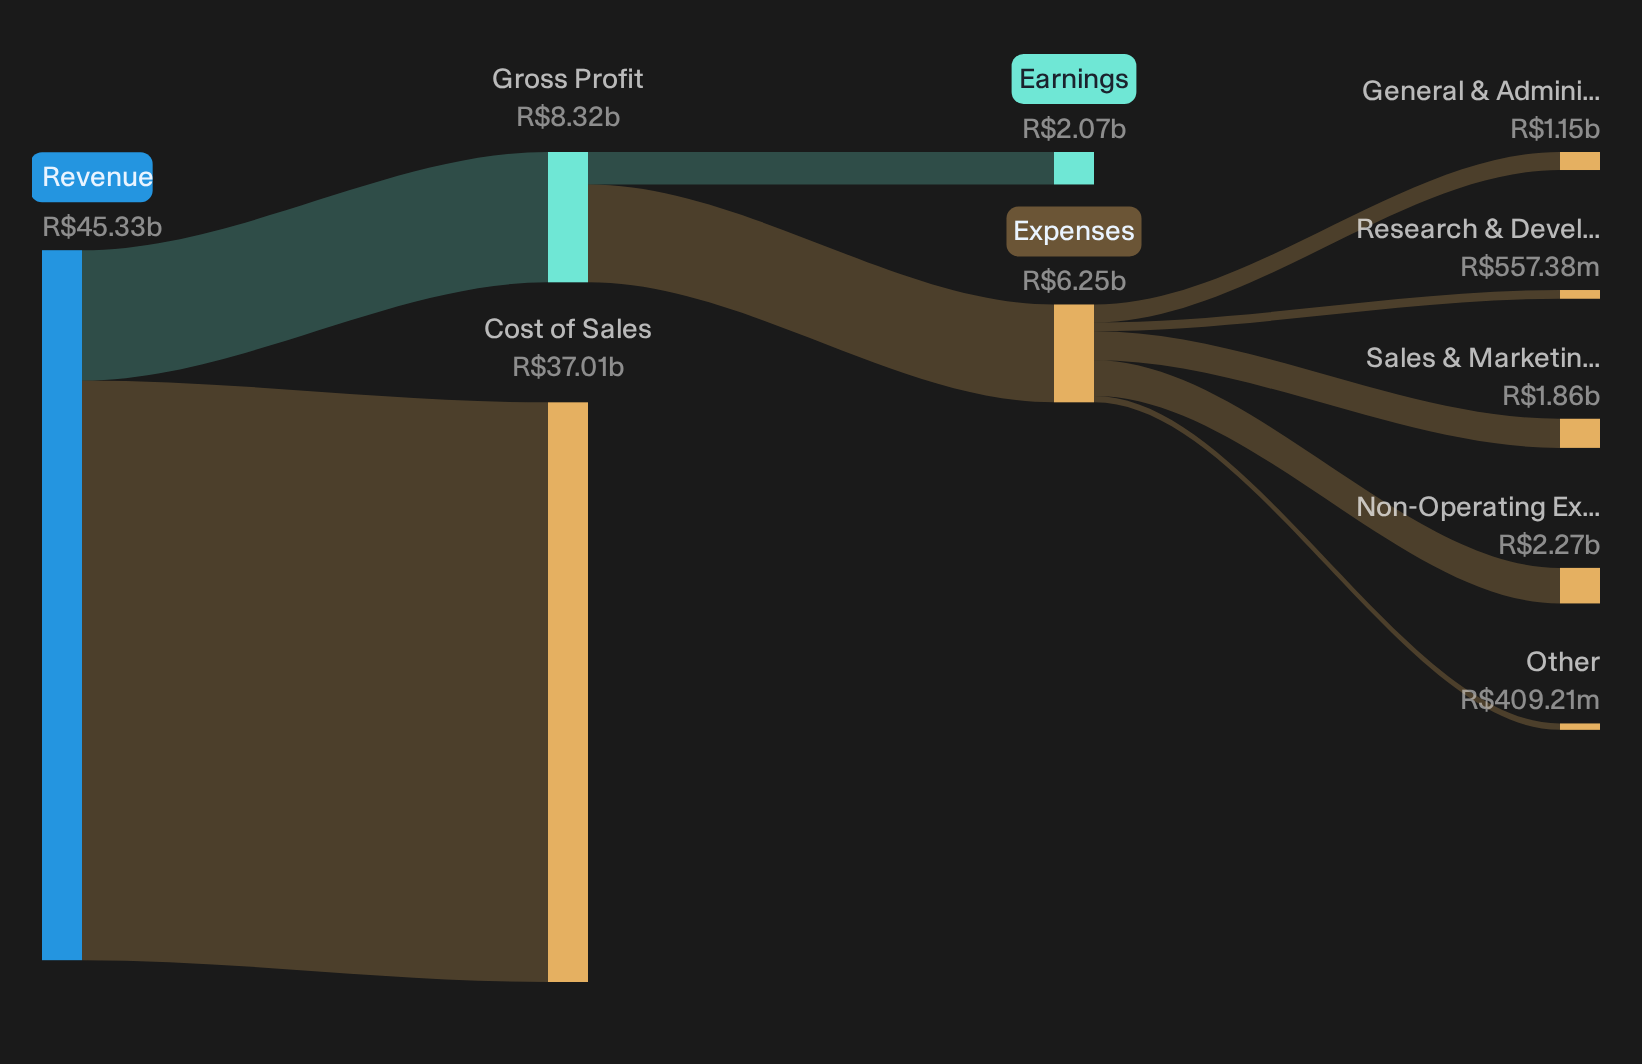
Overview: Embraer is a Brazilian aerospace manufacturer that builds commercial jets, military aircraft, executive jets, and related defense and cybersecurity systems worldwide.
Market Cap: R$79.8b
For a defense-themed screen, Embraer matters because it combines established military programs with large civil aviation exposure. HedgeY, a Simply Wall St Community investor who wrote the Narrative, argues that the real story now is how effectively this aircraft group turns a sizable order book into sustained performance.
"The first driver is simple: backlog conversion. With backlog above $31 billion, Embraer has more than enough demand visibility to keep growing if it can steadily raise output and protect margins."
What really shifts the risk reward for Embraer is how one unresolved pressure on its cost base ultimately feeds through to long term margins.
If that margin pressure is the real swing factor, the full narrative for Embraer shows how backlog conversion, capital intensity and defense exposure could be quietly reshaping Embraer’s risk profile.
Kongsberg Gruppen (OB:KOG)
Overview: Kongsberg Gruppen is a Norwegian defense contractor that supplies air defense, missiles, remote weapon stations and autonomous systems to global military customers.
Operations: The business reports NOK 38.6b of segment adjustments and NOK 2.1b from Other activities, partly offset by NOK 1.5b of eliminations.
Market Cap: NOK 298.7b
Kongsberg Gruppen is a key player for this defense and security screen because its missiles, air defense systems and autonomous platforms are closely linked to rising global and especially European military budgets. Analyst consensus commentary on Simply Wall St connects these factors with a large order backlog and ambitious long-term growth targets.
"The build out of high volume missile production through Zone 5 and new factories in Norway, Australia and the U.S., together with plans for European hubs, positions Kongsberg Gruppen to serve expected large scale orders for affordable missiles, which could add meaningful revenue while supporting group earnings once margins move from single digit levels toward the company average."
What matters now is how any coming inflection in this missile build out affects margins, cash generation and investor expectations.
That inflection risk is exactly what the full narrative for Kongsberg Gruppen unpacks, separating one-off missile ramp costs from longer term earnings power and where expectations could be quietly accelerating.

ASELSAN Elektronik Sanayi ve Ticaret Anonim Sirketi (IBSE:ASELS)
Overview: ASELSAN Elektronik Sanayi ve Ticaret Anonim Sirketi is a Turkish defense electronics group supplying military communications, sensors, weapons systems and security platforms worldwide.
Operations: ASELSAN generates about TRY 214.0b in aerospace and defense revenue, with roughly TRY 173.3b from Turkey and TRY 43.3b from exports.
Market Cap: TRY 1.6t
ASELSAN Elektronik Sanayi ve Ticaret Anonim Sirketi provides concentrated exposure to Turkish defense electronics, with recent earnings and revenue momentum tied to military systems, radar and secure communications. The key question is how one unresolved funding and cash quality tension ultimately shapes the payoff from this growth-heavy defense profile.
That funding and cash quality question is exactly what the ASELSAN Elektronik Sanayi ve Ticaret Anonim Sirketi financial health report unpacks. It highlights where strong defense demand could be masking balance sheet pressure or fresh upside potential.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every headline catches up, the cleanest entry points can be gone. Scan these under the radar lists while it matters and get in early.
- Spot resilient cash generators before they are widely talked about by tracking companies in the list of solid balance sheet and fundamentals (198 results) that keep financial risk in tighter check.
- Ride early momentum in automation by scanning the curated 88 robotics and automation stocks where industrial efficiency, sensors and smart machinery could be building quiet strength.
- Position ahead of potential spending shifts in energy infrastructure using the hand picked 44 power grid technology and infrastructure stocks that highlights grid hardware, software and critical upgrade contractors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com