


EN
Kemper (KMPR) Turns Profitable As Valuation Questions Follow The Q3 Rebound
Kemper (KMPR) just swung from a net loss to a net profit in its latest quarter, reporting US$52.4 million in earnings while revenue reached US$1,090.6 million. That pivot is drawing fresh attention to the stock.
Recent trading reflects that shift in sentiment. Kemper’s share price has risen 16.7% over the past month and 30.3% across 90 days, pointing to building momentum, even though the year to date share price return is down 13.6% and the 1 year total shareholder return is down 7.1%.
Scan how Kemper’s turnaround compares to peers and see which insurers screen well for quality and value using our curated 34 high quality undervalued stocks.
The rebound in Kemper’s share price only tells part of the story. With the stock still below analyst targets, the real question is where fair value lands within that gap between price and estimated worth.
Most Popular Narrative: 26% Overvalued
Kemper’s last close at $34.15 sits well above the bearish fair value of $27.00. The narrative on Simply Wall St leans on a discounted cash flow style view that uses a 7.35% discount rate and the most pessimistic analyst forecasts to stress test that gap.
The multi year restructuring and cost reduction program targets a Specialty Auto expense ratio below 20%. However, the recent allowance for credit losses of US$21.1 million on surplus notes and the earlier US$460 million goodwill impairment show that one off charges can offset expense savings and leave future net margins and book value more fragile than headline cost targets suggest.
See why 1 investors see Kemper as 26% overvalued.
Result: Fair Value of $27.00 (OVERVALUED)
Still, there are clear swing factors. Faster improvement in Kemper’s specialty auto combined ratio, or steadier earnings from Kemper Life, could quickly soften this cautious valuation story.
Find out about the key risks to this Kemper narrative.
Another View: What Kemper’s Sales Multiple Is Saying
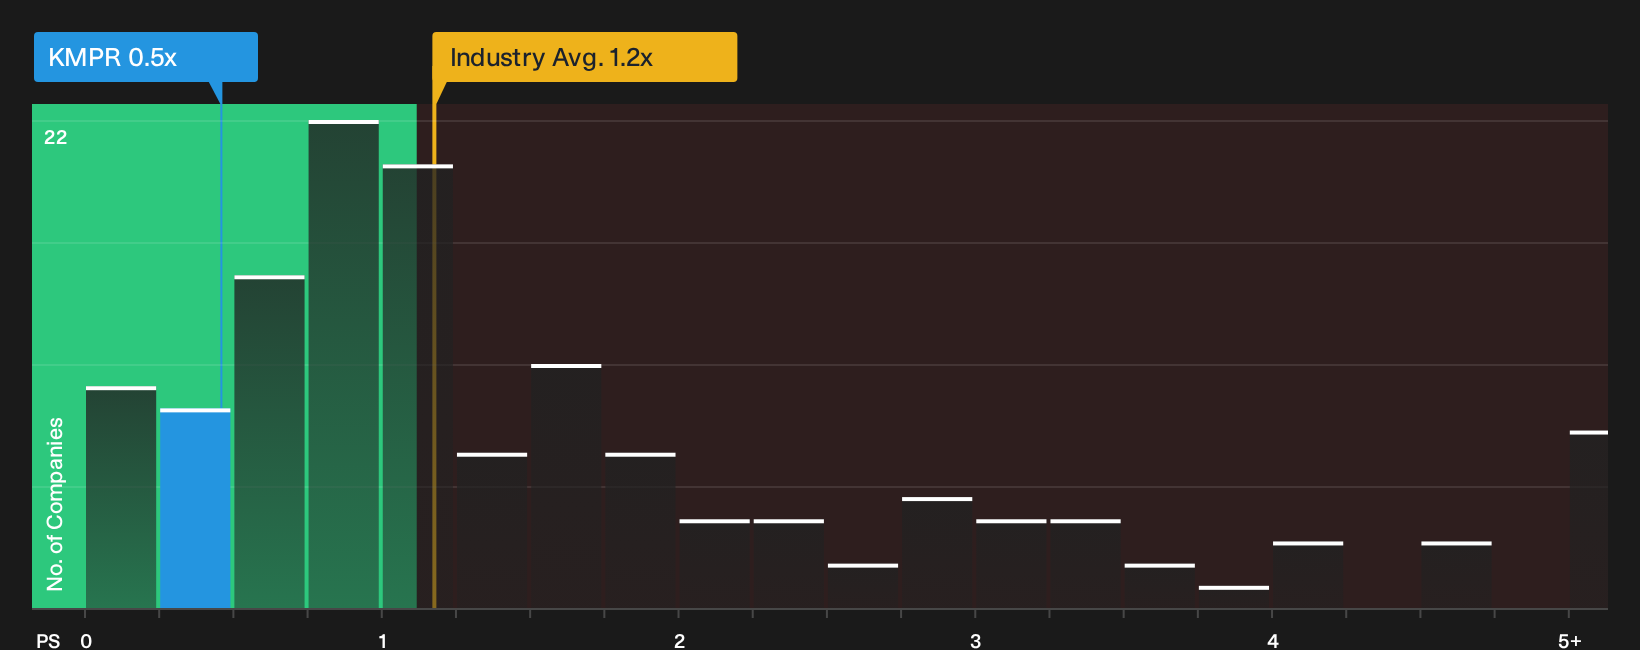
The discounted cash flow style fair value pegs Kemper at $27.00 and labels the stock as overvalued. On a simple revenue multiple, the picture is almost flipped. Kemper trades on a P/S of 0.5x versus 1.2x for the broader US Insurance industry and about 2.6x for peers, while the fair ratio is 0.8x. That gap points to pricing that already bakes in underwriting and balance sheet risk. This leaves the open question of whether investors are being too cautious or just early.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Kemper’s value case. If you want a clear view before sentiment shifts again, weigh the upside against the red flags in the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kemper?
If Kemper has sharpened your focus on value and risk, do not stop here. Broader opportunities often sit just outside the obvious tickers investors already watch.
Use the Simply Wall St Screener to move quickly from curiosity to a short list of candidates that actually fit your risk tolerance and portfolio goals.
- Target potential upside in overlooked opportunities by scanning our hand picked 19 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- Prioritise balance sheet strength and resilience by filtering for companies in the list of solid balance sheet and fundamentals (24 results) that can better handle tough conditions.
- Dial down portfolio stress with a focus on stability using our 29 resilient stocks with low risk scores built to highlight businesses with more defensive profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com