


EN
Earnings Beat Could Be A Big Moment For Yum! Brands Stock (YUM)
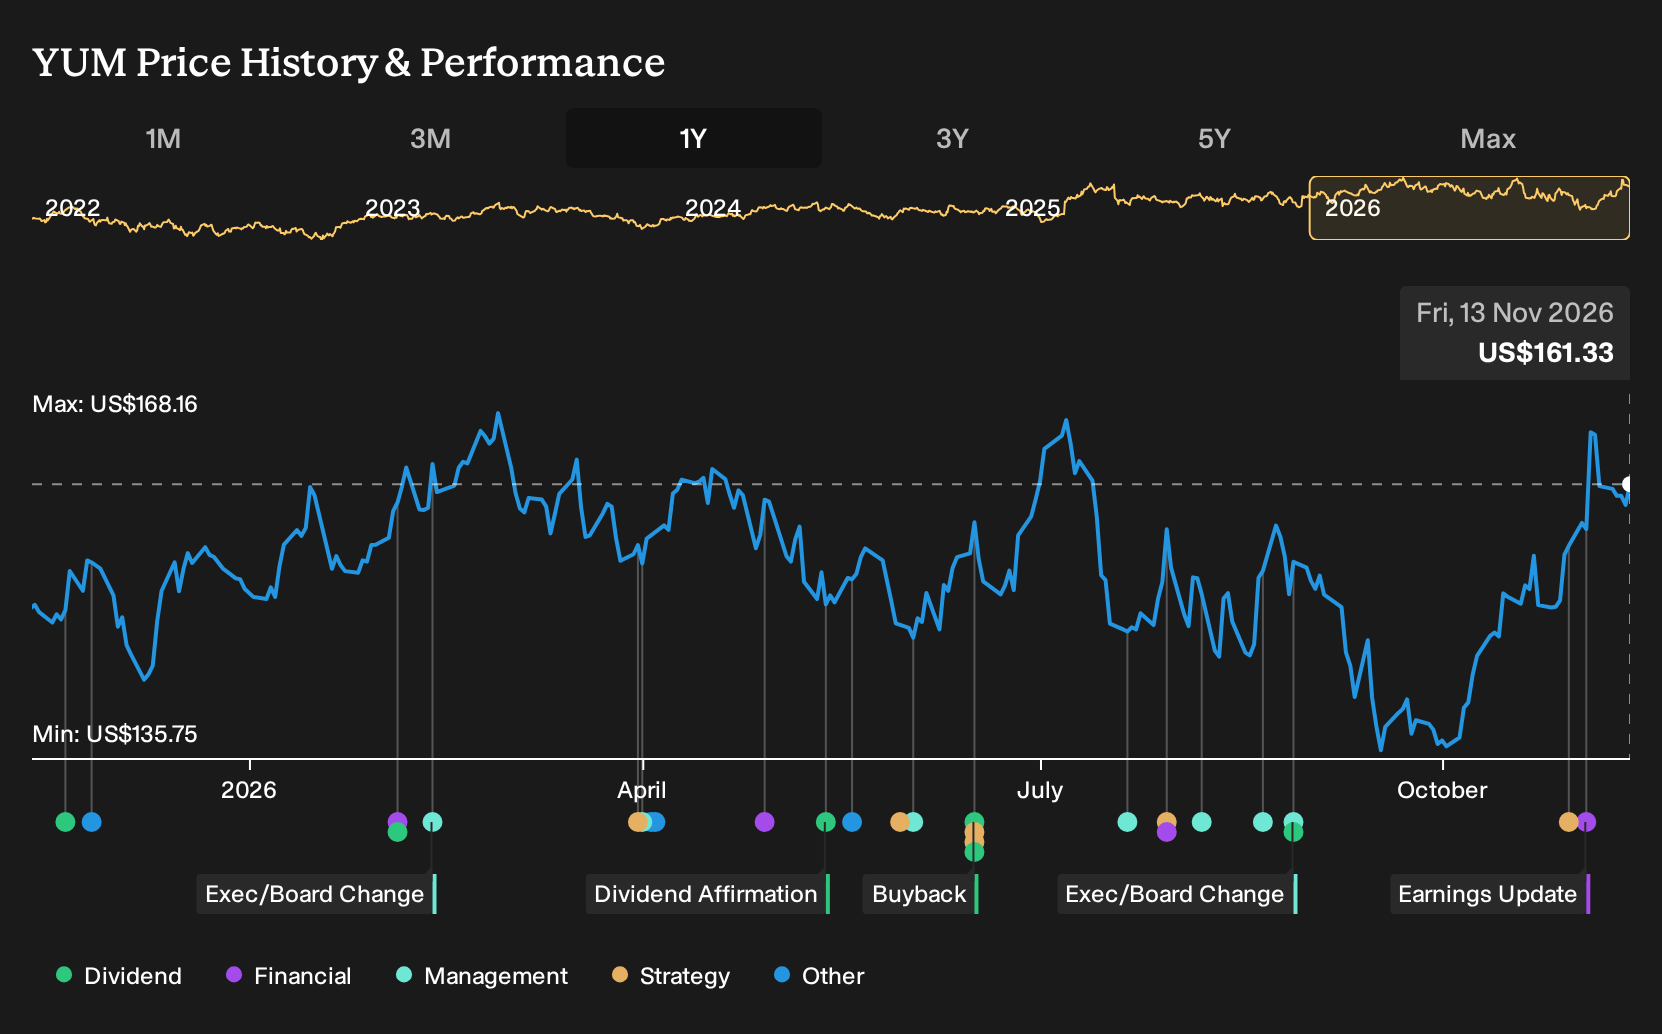
- Yum! Brands reported third quarter 2026 revenue of US$2,054 million and net income of US$1,623 million, and its board approved a US$0.75 quarterly dividend payable on December 11, 2026 to shareholders of record on November 27, 2026.
- The completed sale of Pizza Hut operations in China and other regions, combined with materially higher earnings per share, underscores how Yum! Brands' franchise-heavy model can reshape its profit mix while it manages issues such as Taco Bell traffic pressures.
- The focus now turns to how Yum! Brands' sharply higher earnings per share may influence the existing long-term expansion and franchise-led investment narrative.
Scan how Yum! Brands' latest dividend and earnings story compares with other potential opportunities by reviewing our curated list of 34 high quality undervalued stocks.
Yum! Brands Investment Narrative Recap
To own Yum! Brands, you need to believe in a long run story built on international expansion, Taco Bell’s global rollout and the asset light franchise model that DrPotato, a Simply Wall St Community investor who wrote the Narrative, highlights. The recent earnings jump and Pizza Hut divestment sharpen that focus, while Taco Bell traffic issues and food safety headlines keep operational execution in the spotlight.
The biggest near term swing factor is how quickly Taco Bell volumes stabilise alongside ongoing KFC and Habit Burger momentum. The largest operational risk sits around Yum! Brands’ balance sheet quality, where debt coverage and negative equity already flag pressure, so any sustained hit to franchise sales or royalty flows would likely matter more than a single strong quarter.
The dividend declaration of US$0.75 per share is the clearest fresh signal to look at in the current context. Income focused holders may see it as confirmation that Yum! Brands is still prioritising cash returns, even with flagged issues like an unstable dividend track record and debt that is not fully covered by operating cash flow.
That payout sits alongside very strong reported earnings per share in Q3 2026, helped by asset sales. This makes DrPotato’s focus on the franchise model and long term international rollout particularly relevant. The key investor question is how repeatable the earnings power looks once Pizza Hut exits bed in, Taco Bell traffic normalises and management proves it can support both dividends and balance sheet resilience at the same time.
On those assumptions, DrPotato’s narrative reaches a fair value of US$179.83 per share by pairing 6.0% annual revenue growth with a 25.0% future profit margin. Together, these factors support a higher long run earnings base for Yum! Brands and justify that valuation level in the model.
Uncover why Yum! Brands' fair value indicates an 11% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about US$165 and US$175 per share, so you are seeing a relatively tight band rather than outliers. Those opinions were formed before the recent earnings jump and US$0.75 dividend decision, which could reshape how different investors judge Yum! Brands' resilience and income appeal. Consider these contrasting takes and explore several other viewpoints before firming up your own stance.
Explore 2 other Yum! Brands fair value estimates, including one that suggests it could be worth just $164.52.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Yum! Brands research is our analysis highlighting 3 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Yum! Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yum! Brands' overall financial health at a glance.
Looking for more Yum! Brands investment ideas?
If Yum! Brands has sharpened your appetite for research, use the Simply Wall St Screener to widen your field of options and pressure test your thesis against other businesses with different income profiles, balance sheets and risk levels.
- For investors who care most about quality at a reasonable entry point, start with a curated set of 34 high quality undervalued stocks that combine fundamentals and pricing in a single view.
- If capital protection and steadier price moves matter more to you than chasing every upside swing, focus on a pool of 29 resilient stocks with low risk scores to see which businesses align with that approach.
- When you want to move beyond crowded tickers and find less followed opportunities, scan through a hand picked group of 19 high quality undiscovered gems that pair solid fundamentals with lower investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com