


EN
3 US Financial Stocks Worth Watching As Higher Treasury Yields Reshape Bank Earnings
Rising Treasury yields and hotter inflation data are putting pressure on many US stocks, yet the same forces can reshape the playing field for banks and insurance companies exposed to higher rates. While some businesses face a higher hurdle from steeper discount rates, others may find fresh ways to earn on lending and invested premiums. This article walks through three stocks from our screener that appear positioned to benefit and explains how the latest macro shock ties into their stories.
The three stocks highlighted below are just a sample, with the full screen surfacing 15 more US banks and insurers that share similar quality, yield and valuation traits but bring their own distinct narratives that are not covered here. To size up the full field and identify which interest-rate beneficiaries fit your own return and risk preferences, head straight into the US Financials – Banks and Insurance Benefiting From Higher Interest Rates screener.
Burke & Herbert Financial Services (BHRB)
Overview: Burke & Herbert Financial Services is a Virginia based community bank that collects deposits, makes loans, and provides wealth and treasury services.
Operations: The business generates about $394 million of revenue from community banking activities, all sourced from customers across the United States.
Market Cap: $1.44b
Burke & Herbert Financial Services is positioned as a potential beneficiary of higher interest rates, with community banking driving interest income and a 3.09% dividend providing income to investors during the current rate environment. A central consideration for investors is how much of that additional yield translates into lasting profitability, particularly if any unforeseen pressure on credit costs continues to build.
To see how that trade off looks under the hood, review the 3 key rewards and 3 important warning signs (1 is major!) and judge whether Burke & Herbert Financial Services is pricing in those pressure points or not.

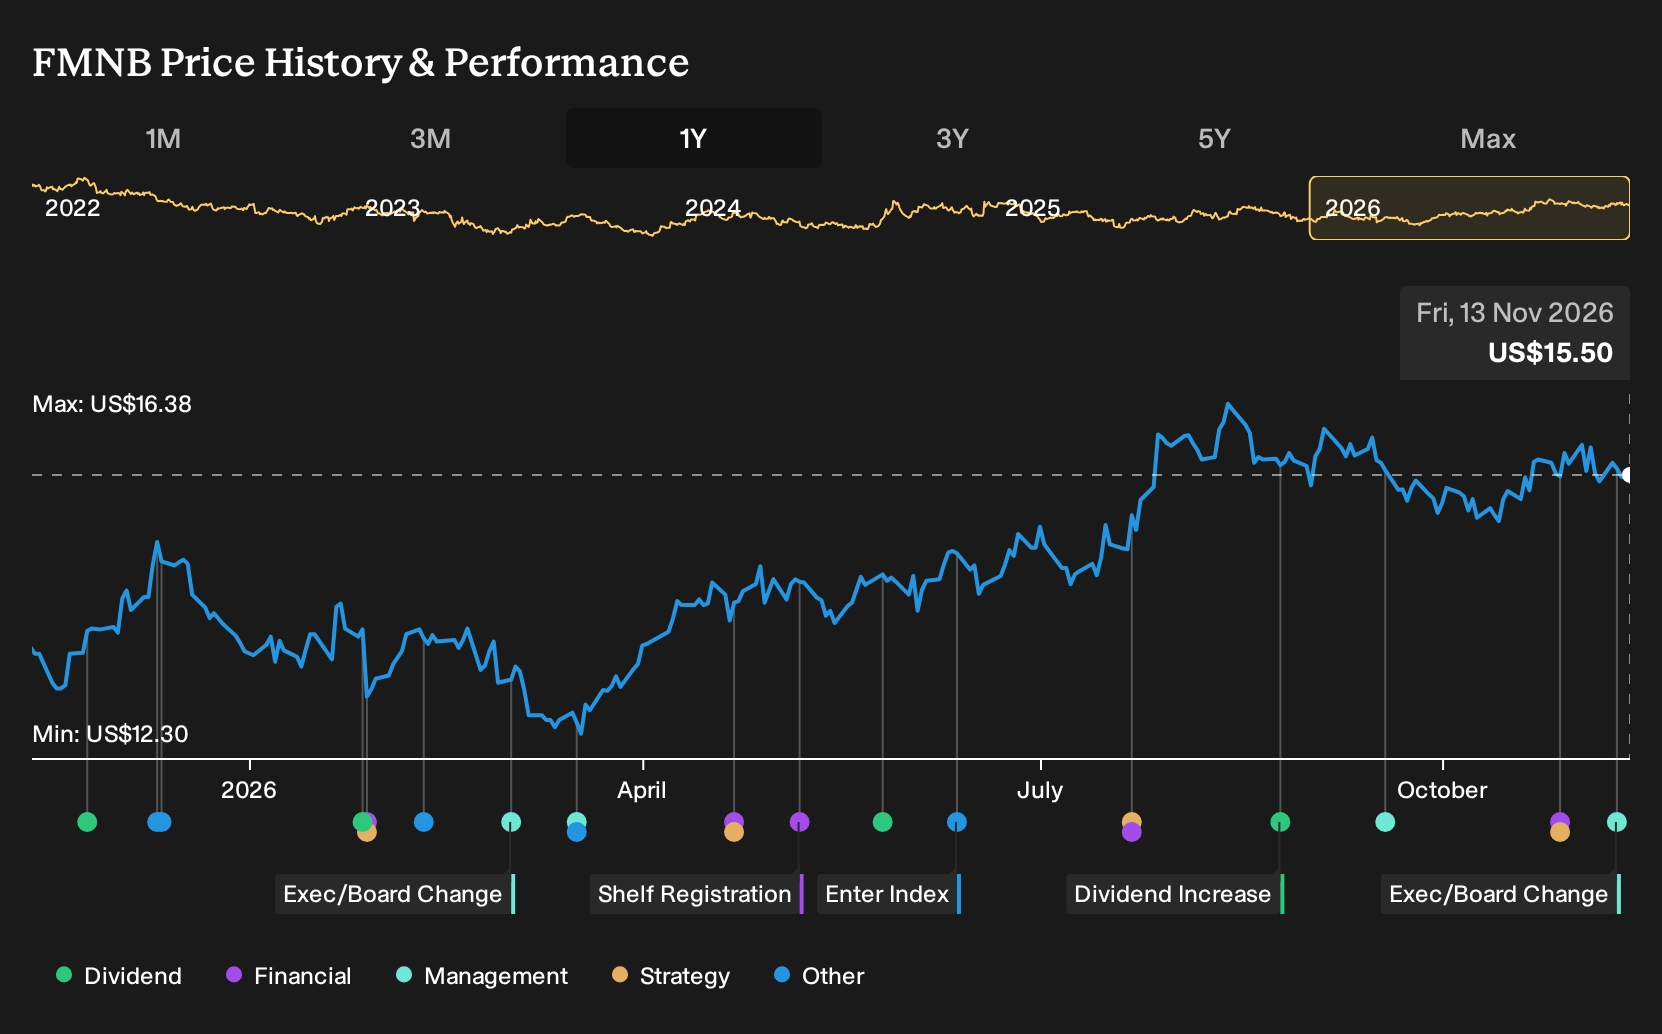
Farmers National Banc (FMNB)
Overview: Farmers National Banc is a Canfield based bank holding company offering US retail and commercial banking, trust, retirement, insurance and financial management services closely tied to interest rate levels.
Operations: Farmers National Banc generates about $181 million from its Bank segment, $16 million from trust and retirement activities, and $38 million from other revenues, all from US customers totaling roughly $235 million.
Market Cap: $918 million
Farmers National Banc is closely connected to the higher rate environment, with a traditional banking engine, fee based trust and retirement services, and insurance income all linked to yields on loans and invested funds. Income focused investors may pay attention to how its 4.39% dividend and current profitability behave if pressure on credit costs and net interest margins changes.
To see whether that 4.39% dividend is masking strength or fragility, run Farmers National Banc through the Farmers National Banc financial health report for a clearer picture of what is really driving returns.
Colony Bankcorp (CBAN)
Overview: Colony Bankcorp is a Georgia based regional bank whose earnings are closely linked to US interest rates through loans and securities.
Operations: Colony Bankcorp generates about US$139 million from its Banking Division, US$8 million from Mortgage Banking, and US$8 million from Small Business Specialty Lending, all in the United States.
Market Cap: US$555 million
Colony Bankcorp sits near the center of this higher rate theme. The analyst consensus Narrative on Simply Wall St highlights how management is trying to convert that backdrop into more durable fee income and earnings momentum.
"The build out of fee-based businesses such as Colony Financial Advisors and Colony Insurance, including almost 15% quarter over quarter growth in assets under management to US$637 million and record pretax income in the insurance unit, positions Colony Bankcorp to generate more noninterest income and reduce reliance on spread revenue over time.
What ultimately happens to returns will hinge on how one quiet source of cost pressure interacts with that fee shift and higher rate backdrop.
That quiet cost pressure is exactly what the full narrative for Colony Bankcorp unpacks, showing where earnings risk could be easing and where Colony Bankcorp’s fee shift might be accelerating.

Seeking Fresh Alternatives Beyond Banks?
Fresh opportunities move first. By the time momentum is flying and headlines catch up, the ideal entry window can be dropping out of reach. Scan these ideas before the crowd and act now.
- Target income resilience by weighing curated high-yielders in the 6 dividend fortresses while the best combinations of payout strength and balance sheet quality remain under the radar for now.
- Track early breakout potential by reviewing the 34 high quality undervalued stocks before renewed momentum is fully caught in the price and the easy mispricing edge disappears.
- Ride structural shifts in automation by checking the hand picked 88 robotics and automation stocks while valuations still reflect hesitation rather than full conviction buying.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com