


EN
Why Zeta Global Holdings (ZETA) Is Back In The Spotlight
Zeta Global Holdings (ZETA) just paired a profitable third quarter with higher guidance for the fourth quarter and full year 2026, a combination that often sharpens investor focus on execution.
That backdrop has kept Zeta Global Holdings on many radar screens, with a 7 day share price return of 18.11% and a 90 day gain of 27.12% helping push the year to date share price return to 84.08%. The 1 year total shareholder return of 98.75% and 3 year total shareholder return of more than 3x signal that momentum has been strong over both shorter and longer horizons, despite a 1 day share price decline of 1.66% to $36.65 as investors absorb the latest guidance and weigh how much of this earnings story is already reflected in the current valuation.
Scan beyond Zeta Global Holdings and see which other AI driven platforms are showing similar earnings momentum with the curated 43 profitable AI stocks that aren't just burning cash list.
After Zeta Global Holdings surged on stronger profits and fresh guidance, then slipped on the latest print, the real fork in the road now is timing. Investors must decide whether to pay up after this run or wait and risk watching it run further as the valuation case unfolds next.
Most Popular Narrative: 4% Undervalued
Zeta Global Holdings is trading at $36.65 against a fair value narrative of $38.29, which suggests a modest discount according to the analyst consensus Narrative on Simply Wall St that ties revenue and earnings forecasts directly to cash flow assumptions.
The focus on owned, opted in data and privacy friendly activation is reinforced by Zeta’s Data Cloud of over 535 million profiles with thousands of attributes each and an external study citing around 600% to 700% average return on marketing spend when combined with client data. This can support pricing power, customer retention and margins.
See why 162 investors see Zeta Global Holdings as 4% undervalued.
Result: Fair Value of $38.29 (UNDERVALUED)
Still, the whole Zeta Global Holdings story can be derailed if tighter privacy rules bite into Data Cloud monetization or if adjusted results keep diverging from GAAP earnings.
Find out about the key risks to this Zeta Global Holdings narrative.
Another View: What Zeta Global Holdings’ P/S Ratio Signals
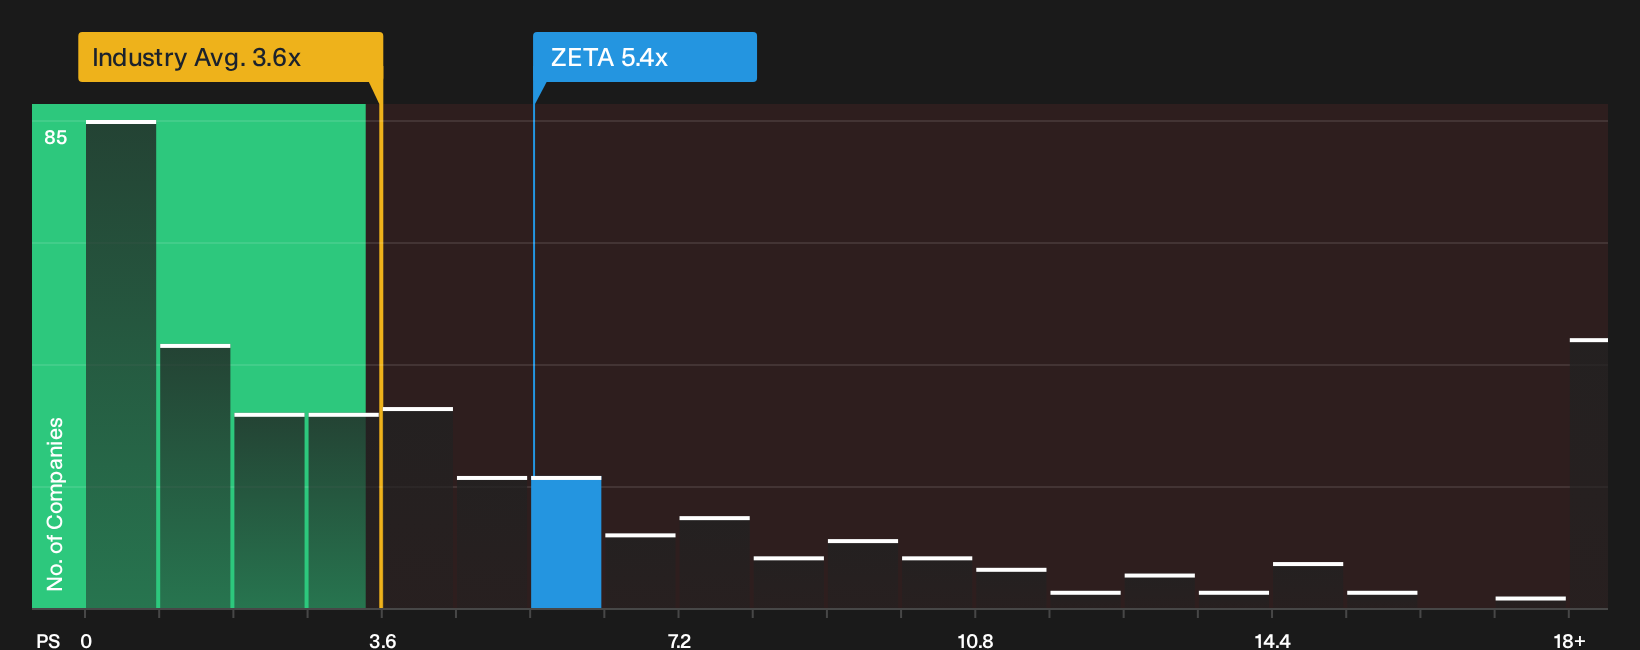
The fair value narrative leans on future cash flows, yet today Zeta Global Holdings trades on a P/S of 5.4x versus a fair ratio of 4.9x and a US software average of 3.6x. That premium points to higher valuation risk if growth or sentiment cools. Which story do you trust more?
For a closer look at how this price tag lines up with fundamentals, our valuation breakdown sets out the numbers side by side, including how the ratio could shift if sentiment changes: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed signals on Zeta Global Holdings so far. If you want to move early and rely on your own judgment, consider the full picture of both risks and rewards through 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Zeta Global Holdings?
If you are serious about building a stronger portfolio, do not stop at Zeta Global Holdings. Use the screener to spot opportunities others overlook.
- Target potential mispricing by scanning for quality companies that may trade below estimated worth through the 34 high quality undervalued stocks.
- Build a sturdier core by focusing on businesses with financial strength using the list of solid balance sheet and fundamentals (24 results).
- Boost your income stream by filtering for higher yielding payers through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com