


EN
Ormat Technologies (ORA) Lifted Guidance, Is It A Bargain Or Fully Priced?
Ormat Technologies (ORA) just delivered third quarter results that combined higher sales and earnings with a small US$150,000 impairment charge, while also raising full year revenue guidance and affirming its regular dividend.
At a share price of US$90.45, Ormat Technologies has seen the 90 day share price return fall 20.6% even as fresh earnings, raised full year revenue guidance and the affirmed dividend keep investor attention on its longer record. The 3 year total shareholder return of 42.26% remains well ahead of the 1 year total shareholder return decline of 16.35%, suggesting momentum has cooled recently even while interest in its battery storage expansion and long term contracts continues to shape expectations for risk and growth potential.
Scan other income-focused utilities with resilient cash flows and long-term contracts by reviewing our curated list of 6 dividend fortresses along with Ormat Technologies.
After a sharp 90 day slide, stronger earnings and raised guidance pull the story in the opposite direction. Does Ormat Technologies now offer enough potential reward to justify the recent volatility in price?
Most Popular Narrative: 24% Undervalued
On the analyst consensus Narrative on Simply Wall St, Ormat Technologies screens as undervalued, with a fair value estimate of about $118 against the last close at $90.45. That gap rests on detailed assumptions for revenue growth, profit margins and earnings through 2029, all discounted back at 8.57%.
The main thing that has to go right is successful execution of Ormat Technologies large geothermal, energy storage and Enhanced Geothermal Systems build out, including delivery of its identified project and interconnection pipeline within planned capital and margin frameworks.
The emerging Enhanced Geothermal Systems opportunity, including pilots at Dixie Valley and Cove Fort supported by about US$35 million of U.S. Department of Energy funding and a target of 1 GW of EGS capacity in the mid 2030s, positions Ormat Technologies to pursue a larger addressable market that could add meaningful long term revenue and earnings once commercial projects are built and contracted.
See why 12 investors see Ormat Technologies as 24% undervalued.
Result: Fair Value of $118 (UNDERVALUED)
Still, the bullish Ormat Technologies narrative leans on tighter storage hardware rules not cutting into tax credits, and on higher margin targets actually being reached.
Find out about the key risks to this Ormat Technologies narrative.
Another View on Ormat Technologies Valuation
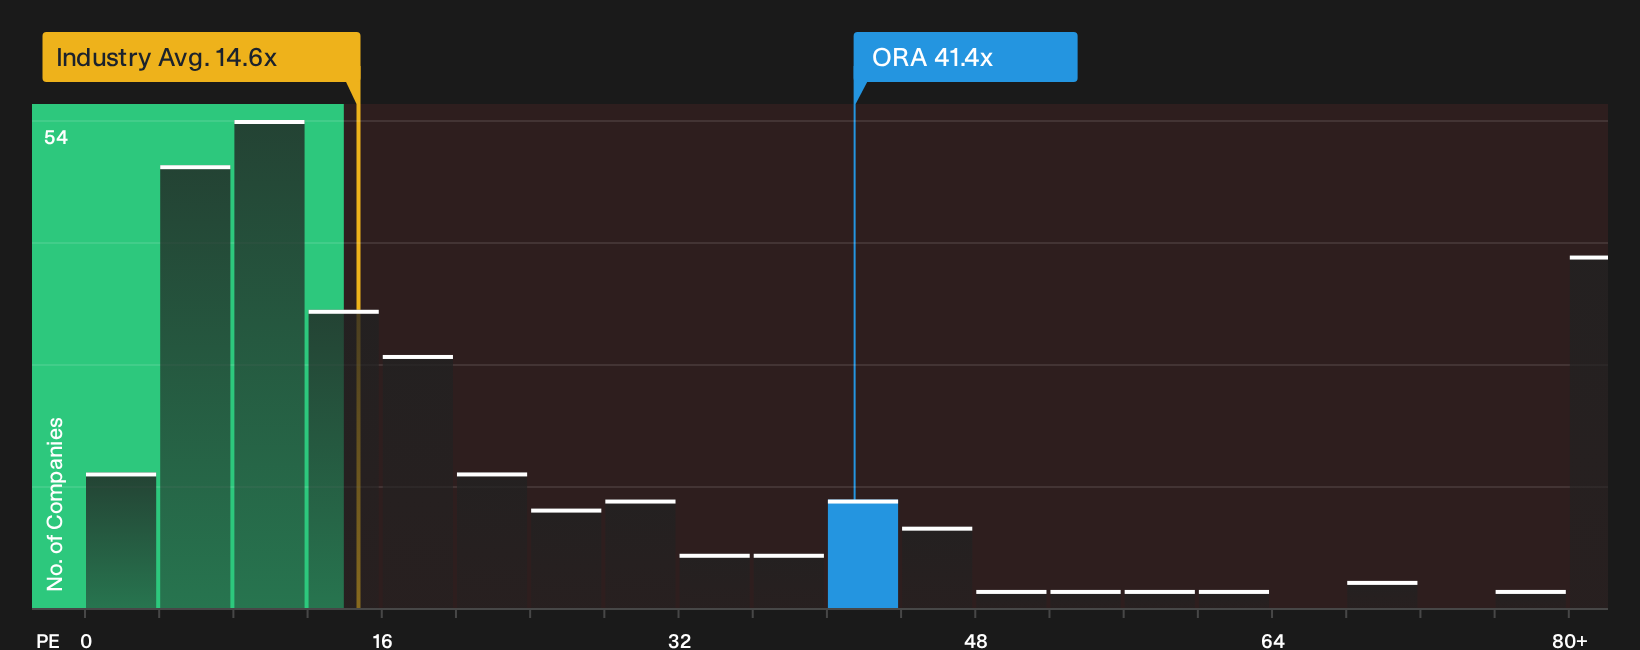
That 24% undervalued story leans heavily on long term earnings forecasts and discount rates. A simple P/E lens paints a very different picture. Ormat Technologies trades on about 41.4x earnings, while peers sit near 11.7x and the fair ratio flags 25.1x. That is a wide premium. Is the extra price truly earned?
For investors comparing these signals, the gap between Ormat Technologies current P/E and the fair ratio prompts a closer look at what expectations are already baked into the stock, and how much patience you are willing to have for the thesis to play out. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Ormat Technologies valuation and sentiment can feel messy, so review the full set of data points and pressure test your own thesis quickly. Round out that view by weighing 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ormat Technologies?
If you only focus on Ormat Technologies, you could miss other opportunities. Put a few more contenders on your radar using the Simply Wall St screener.
- Target potential mispricing by scanning companies that screen as 34 high quality undervalued stocks before the crowd pays closer attention.
- Prioritise resilience first by filtering for a list of solid balance sheet and fundamentals (24 results) that can better handle bumps in the cycle.
- Seek earlier stage potential by checking out a curated set of 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com