


EN
How Single Stage EV Charger Plans Will Impact Visteon Stock
- Visteon and SHINRY Technologies, through their joint venture Visteon Shinry Power Electronics, previously announced a collaboration with Infineon Technologies to build a single stage onboard charger for electric vehicles. The charger uses Infineon’s gallium nitride bidirectional switches for higher efficiency and full vehicle to everything capability.
- This move pushes Visteon further into high voltage power electronics and adds a bidirectional charging platform that could complement its existing cockpit, battery management and compute programs with higher content per electric vehicle.
- We will now explore how Visteon’s investment narrative could be influenced by this GaN based bidirectional onboard charger collaboration.
Scan more EV power electronics contenders alongside Visteon with a curated set of 44 power grid technology and infrastructure stocks for your watchlist.
Visteon Investment Narrative Recap
To own Visteon, you need to believe the analyst consensus Narrative on Simply Wall St is broadly right that digital cockpit wins, high performance compute programs and higher content per vehicle can offset pressure from legacy contracts and softer Americas revenue. The GaN onboard charger work with Infineon points to another content angle in electric vehicles, but it does not yet change the near term story.
The most important short term swing factor remains execution on booked cockpit and display programs while managing input cost pressure, especially memory, which has already weighed on margins. The biggest risk is that mix shift toward Asia and newer customers, plus newer adjacencies like power electronics, does not refill volume lost from Ford, GM, Nissan and Mazda quickly enough.
Among recent themes, the push into high voltage power electronics and battery management looks closest to this GaN onboard charger news. Visteon is already supplying wired and wireless battery management systems and integrated power electronics units, so an onboard charger product lines up operationally with that direction rather than creating an entirely new leg of the story.
For catalysts, the charger platform could eventually sit alongside SmartCore and the more than US$1b high performance compute cockpit bookings that analysts expect to start launching in late 2026 and ramp from 2028. Execution risk stays real, because margins are currently 4.1% compared with 7.2% last year and annual sales have recently declined, so any new program has to earn its keep without diluting profitability further.
Visteon's narrative projects US$4.6b revenue and US$263.0m earnings by 2029. This assumes 6.5% yearly revenue growth and an earnings increase of about US$104m from current earnings of US$159.0m.
Discover how Visteon's fair value indicates a 33% potential upside to its current price that could narrow more quickly than expected.
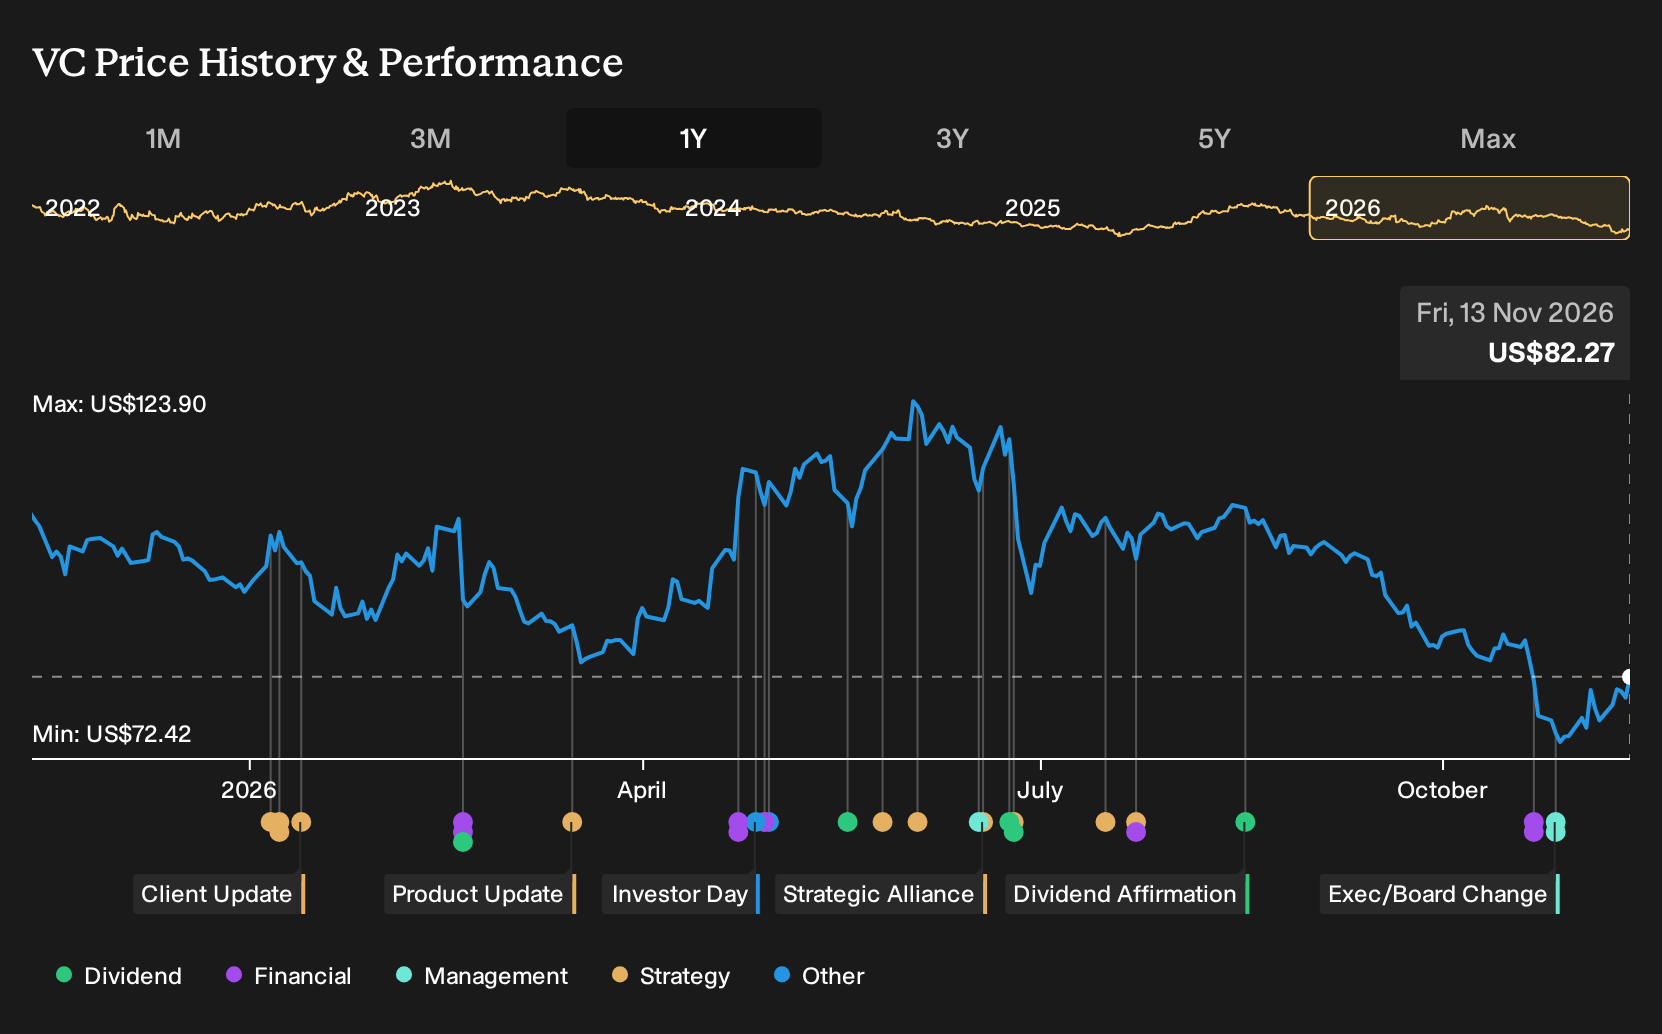
Exploring Other Perspectives
Bullish analysts focus on one big swing factor for Visteon. They see the booked software defined cockpit and Asia heavy pipeline as the real story and were already modeling about US$5.3b revenue and US$319.6m earnings by 2029 before this GaN charger news. You can treat this collaboration as a fresh prompt to compare those assumptions with your own.
Explore another Visteon fair value estimate, including one that suggests potential upside of as much as 219% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Visteon research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Visteon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Visteon's overall financial health at a glance.
Looking for more investment ideas beyond Visteon?
Once you have a view on Visteon, it can help to compare it with other opportunities that share similar quality, income, or risk profiles. The Simply Wall St Screener lets you quickly filter for companies that fit the kind of portfolio you want to build, whether you care most about balance sheet strength, income, or underappreciated potential.
- For investors who want to focus on strong fundamentals and robust finances, start with a curated list of solid balance sheet and fundamentals (24 results) that may help you stress test your risk tolerance.
- If you are hunting for mispriced opportunities where quality and valuation intersect, scan a targeted set of 34 high quality undervalued stocks that could complement or contrast with your Visteon thesis.
- Income focused readers who want potential payouts alongside resilience can review a hand picked group of 6 dividend fortresses to see which ones deserve a place on the watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com