


EN
The Call Talos Energy Bulls Got Right
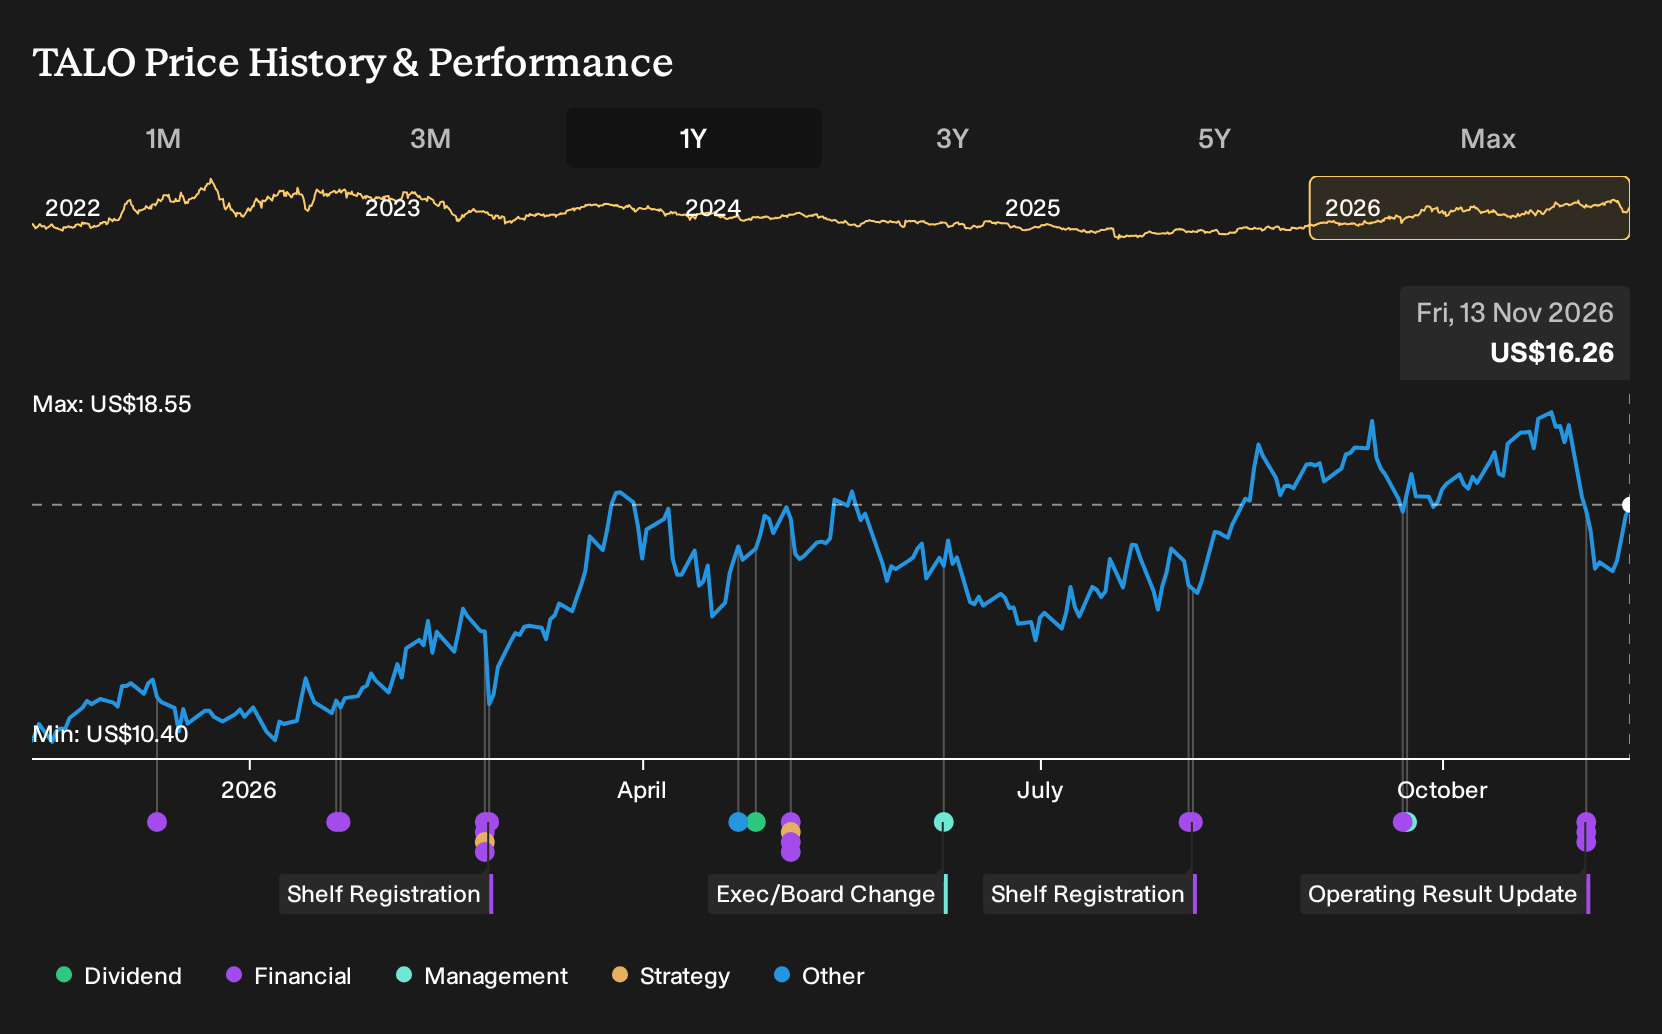
If you only read the headlines about Talos Energy buying Shell’s deepwater Gulf of America assets, with new reserves, infrastructure and fresh production, the past year might look like a simple story of deal-making meeting investor enthusiasm. Holding Talos Energy over the past year would have returned 50.0%, including dividends. If you were weighing a purchase back on 13 November 2025, how confident would you have been that this Gulf heavy portfolio was worth that kind of bet?
If the move has made Talos Energy harder to judge, start where the gap is still open and scan 34 high quality undervalued stocks.
The Two Talos Energy Stories Investors Were Arguing About
The shares cost US$10.55 at the start of the period, and anyone looking at Talos Energy then was really choosing between two competing stories about the same Gulf focused producer.
The bullish narrative saw a firm using cost discipline and Gulf of Mexico projects to build resilience, with a Fair Value of US$13.17. That price was implied by assumptions built on a targeted US$100 million a year efficiency program that was expected to improve recurring free cash flow.
The more cautious script put Fair Value at US$9, a lower implied price. It focused on heavy Gulf exposure, where hurricanes, decommissioning costs and regional regulation could raise expenses and unsettle production.
What The Later Facts Said About The Talos Energy Thesis
The clearest development for Talos Energy was the Shell deepwater deal, which brought producing Gulf of America assets and about 23 million barrels of proved reserves. This echoed the optimistic case that scale and infrastructure could support stronger free cash flow. Reported Q3 2026 figures showed revenue at US$595.953 million and a loss of US$81.244 million. Net margin improved to -13.6%, so profitability remained unproven and the evidence cut both ways.
The lesson is simple. When a story leans on efficiency, watch whether net margin and absolute profit move toward profit, not just whether new assets or projects are announced.
What Talos Energy’s Price Already Assumes Today
Talos Energy now trades at US$16.26, after a 50.0% gain over the past year. The bearish analyst Narrative on Simply Wall St still places its Fair Value above that level, based on modeled cash generation and risk.
That Narrative leans on Talos turning offshore cost advantages and the Shell deal into durable free cash flow. The key question is whether production, margins and leverage can all stay within the tight ranges that view assumes.
"The main factor that has to go right is that Talos Energy continues converting its offshore cost advantages, Gulf of America acquisition, and international portfolio into sustained free cash flow while keeping leverage below 1x and continuing share repurchases."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Talos Energy And The Pipes Beneath
Talos Energy lives where hydrocarbons are produced. Your next question is where they actually move.
Offshore fields and Gulf platforms still rely on vast networks that move gas, liquids and crude to buyers.
One large operator quietly spends heavily on new long haul gas lines, storage sites and export docks to move more volume under long contracts.
The same demand from power plants and data centers that shapes Talos forecasts also pulls on these pipes.
If that pull keeps building, a midstream owner that already controls major routes could see its role shift from background utility to crucial throughput gatekeeper.
That argument has a Narrative and a number behind it. → See the company one Narrative values 27% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com