


EN
Does Shoppable Video Launch Change The Bull Case For Adeia (ADEA)?
- Adeia Inc. recently introduced in-house e-commerce technologies, including Clickable Video and a Digital Wallet architecture, that connect shoppable video, existing payment credentials and retailer platforms to support more engaging and streamlined online purchasing.
- The company is already licensing these media commerce tools to large retailers and digital platforms, which ties Adeia’s patent-heavy business model to new transaction-based monetization opportunities.
- This development may influence Adeia’s investment narrative as Clickable Video enables e-commerce monetization across media partners.
Compare Adeia's push into shoppable video with other companies tying media to checkout by scanning through our hand picked 53 AI infrastructure stocks for potential peers in this commerce infrastructure trend.
Adeia Investment Narrative Recap
To own Adeia, you need to believe the IP licensing engine can keep converting its large patent stack into long running media, semiconductor and now commerce contracts. The key short term swing factor still sits in licensing timing and litigation outcomes, which the analyst consensus Narrative on Simply Wall St already flags as sensitive for revenue and earnings volatility.
The shoppable video push speaks more to medium term positioning than to the next few quarters. In the near term, the lowered 2026 guidance, higher legal spend and customer concentration remain the biggest watchpoints. This new e commerce layer helps diversify, but does not yet change the core licensing and cash collection story.
The launch of Clickable Video and the Digital Wallet architecture feels most relevant here because it ties directly into Adeia’s existing media and OTT customer base. If these tools gain traction, they could deepen relationships with streaming platforms and retailers by tying royalties to higher value commerce enabled use cases instead of only content delivery.
That said, execution risk is clear. Adeia is entering a crowded commerce infrastructure arena at the same time analysts expect earnings to decline over the next 3 years and litigation costs to rise. For investors, the question is whether this e commerce push can offset guidance pressure, customer disputes and high legal expense over time.
Adeia's narrative projects US$454.7 million revenue and US$78.6 million earnings by 2029. This aligns with analyst assumptions that revenue stays fairly flat, while earnings decline by US$37.5 million from current earnings of US$116.1 million.
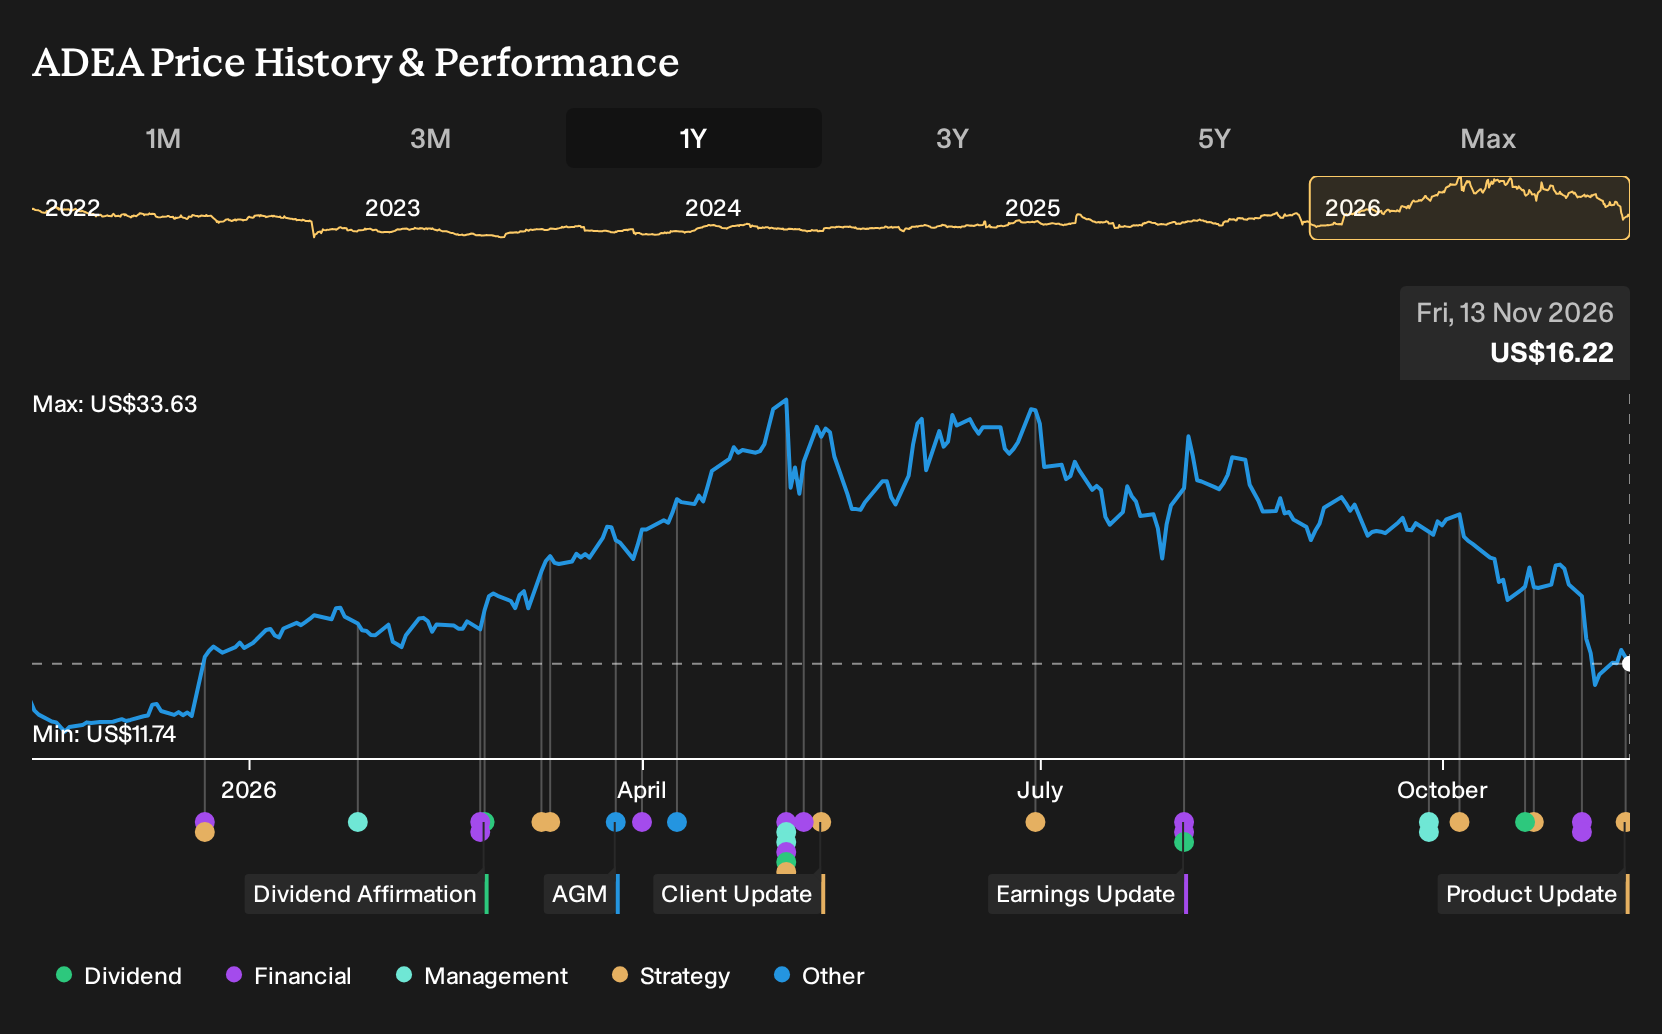
Uncover why Adeia's fair value indicates a 136% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Adeia’s shoppable video move as a possible accelerator for recurring royalties, which contrasts with the consensus focus on litigation and guidance cuts. That bullish group was already modelling 2029 revenue around US$477.0 million and earnings near US$111.5 million before this announcement; their narrative may shift further if commerce traction improves.
Explore 4 other Adeia fair value estimates, including one that suggests potential upside of as much as 208% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Adeia research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Adeia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adeia's overall financial health at a glance.
Looking for more Adeia sized investment ideas?
If Adeia has you thinking about where patents, platforms and cash flow meet, it can help to widen the lens and compare it with other businesses that fit different risk and reward profiles.
- Prefer a watchlist of companies with less balance sheet strain and steadier fundamentals? Run your eye over our list of solid balance sheet and fundamentals (24 results).
- If you care most about valuation and want to focus on quality assets that might be priced below what their fundamentals suggest, scan through the 34 high quality undervalued stocks.
- For readers who prize resilience over excitement and want companies that score well on overall risk checks, the 29 resilient stocks with low risk scores is a useful hunting ground.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com