


EN
What Eregli Holders Got Right
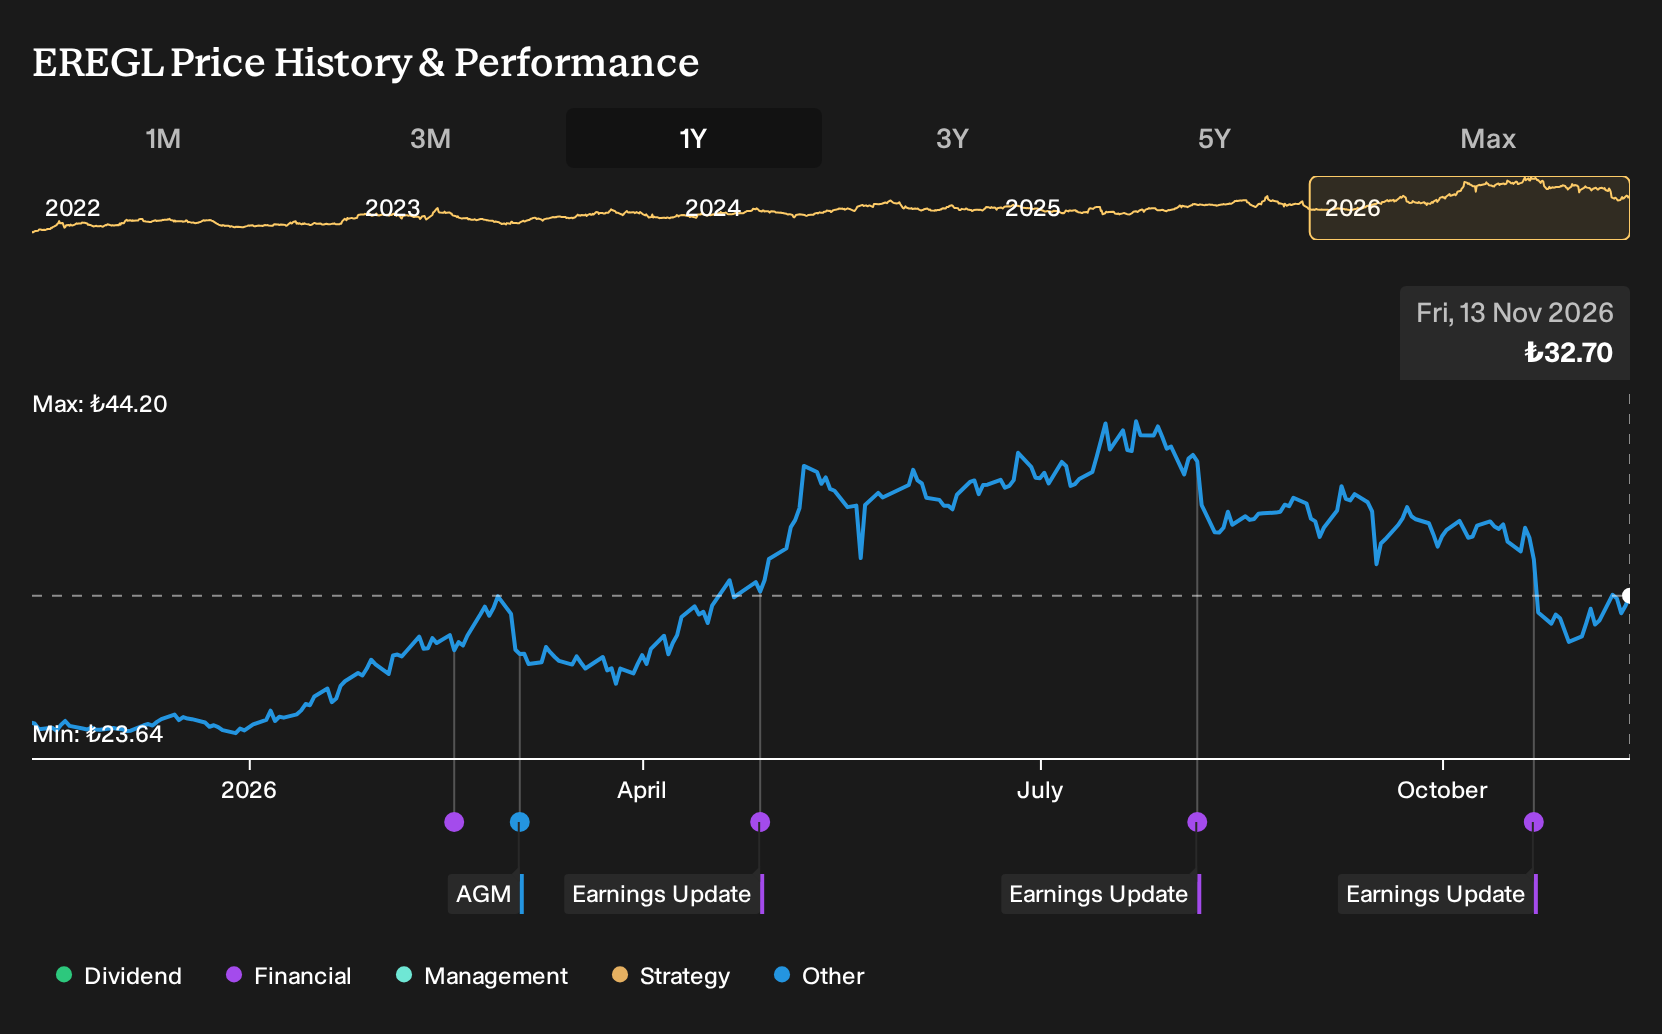
For Eregli Demir ve Çelik Fabrikalari T.A.S shareholders, the return over the past year was 38.7%, including dividends. If you had put money into the stock on 13 November 2025, that outcome now begs a simple question: With one bullish report arguing fair value was 15% above the start price and a bearish view sitting 34% below it, what exactly were early buyers weighing around decarbonization costs, export reliance and steel overcapacity?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Eregli Demir ve Çelik Fabrikalari T.A.S has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Weigh On Eregli Demir ve Çelik Fabrikalari T.A.S
The shares cost TRY24.28 at the start of the period, and anyone looking at Eregli Demir ve Çelik Fabrikalari T.A.S then was really choosing between two different stories.
The bullish narrative saw fair value at TRY27.99. This view was built on the idea that new blast furnaces, coke batteries and energy projects could lift efficiency and support higher margins, while an EU focused export strategy diversified sales.
The bearish narrative put fair value at TRY16.09. It emphasized that heavy blast furnace reliance, rising decarbonization capex and possible EU trade barriers might keep compliance costs elevated and put pressure on long term profitability.
What The Results Changed For Eregli Demir ve Çelik Fabrikalari T.A.S
The clearest new fact was the Q3 2026 report. Total revenue was TRY71,291.395m and net income was TRY2,210.474m, compared with TRY52,957.615m and TRY651.157m in Q3 2025. Net margin moved from 1.2% to 3.1%. That shift in profitability supported the optimistic case about efficiency gains, although one set of quarterly figures did not settle the long term debate.
The main lesson is simple. When a story leans on better margins at a company like Eregli Demir ve Çelik Fabrikalari T.A.S, you test it against reported net income and net margin, not just revenue lines or share price moves.
What Eregli Demir ve Çelik Fabrikalari T.A.S Buyers Are Pricing In Now
Eregli Demir ve Çelik Fabrikalari T.A.S trades at TRY32.7 today. The bearish analyst Narrative on Simply Wall St sees Fair Value below that level and frames the stock as already pricing in a lot of good news.
The Narrative highlights that recent efficiency gains, heavy capex and tight trade rules all have to keep working together. A buyer at today’s price needs confidence that EBITDA per tonne and high utilization can be sustained while leverage stays within management’s comfort zone.
"Although Eregli Demir ve Çelik Fabrikalari T.A.S has guided 2026 EBITDA per tonne at $75 to $85 and reported Q2 2026 at $75, reliance on a still evolving uplift from new blast furnace and coke battery investments creates risk that any operational issues or slower productivity gains could cap EBITDA per tonne closer to the low end of guidance."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 47% below our estimate - builds AI driven hiring and local services platforms that monetise matching and fee-based placement.
- Company 2 - 33% below our estimate - expands a maintenance focused elevator portfolio while improving modernization project mix and pricing discipline.
- Company 3 - 48% below our estimate - sells accelerated computing hardware and software enabling large scale AI infrastructure for enterprise customers.
That is three of the list. See all 198 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com