


EN
Earnings Beat Could Be A Game Changer For Murphy Oil Stock (MUR)
- Murphy Oil reported third quarter 2026 revenue of US$854.97 million and net income of US$171.12 million, alongside higher full year 2026 production guidance and newly signed offshore production sharing contracts in Cameroon and Mauritania, plus fresh exploration licenses in Israel.
- The combination of stronger earnings, raised production expectations and expanded offshore exposure gives Murphy Oil a wider set of levers to manage future production mix, capital deployment and potential cash flow resilience across several international basins.
- We will examine how Murphy Oil's investment narrative is affected by stronger earnings alongside new offshore Cameroon production sharing contracts.
Compare Murphy Oil's expanding offshore footprint with other producers positioning for the next leg of the cycle by scanning our hand-picked 34 high quality undervalued stocks.
Murphy Oil Investment Narrative Recap
To own Murphy Oil, you need to believe the higher capital spending program eventually converts into reserves and productive barrels without straining free cash flow or the dividend. The analyst consensus narrative on Simply Wall St leans on that conversion, and the Cameroon, Mauritania and Israel awards expand the opportunity set rather than changing the near term story.
The most important near term swing factor still sits with execution at Bubale, Vietnam and the Eagle Ford, where well costs and timing remain key variables. The main operational risk is that elevated spend and exploration activity under deliver, which could expose the weaker free cash flow coverage of the current dividend.
The new production sharing contracts in Cameroon look most relevant here. Murphy Oil will initially operate 2,600,000 acres at 100% working interest, with the state company holding a future back in right. That structure gives Murphy full control of early appraisal decisions, but it also concentrates the upfront capital burden and technical risk on its balance sheet.
For investors tracking catalysts, those Cameroonian blocks add another offshore bucket that must compete with Bubale, Vietnam and the Eagle Ford for capital. Success could broaden the future production mix and help support guidance ranges. Disappointing results or cost inflation would instead compound the existing concerns around higher 2026 capex and project returns.
Murphy Oil's narrative references analyst expectations for revenue of US$3.3b and earnings of US$679.5 million by 2029. This implies forecast yearly revenue growth of 3.6% and an earnings increase of about US$384 million from current earnings of US$295.2 million.
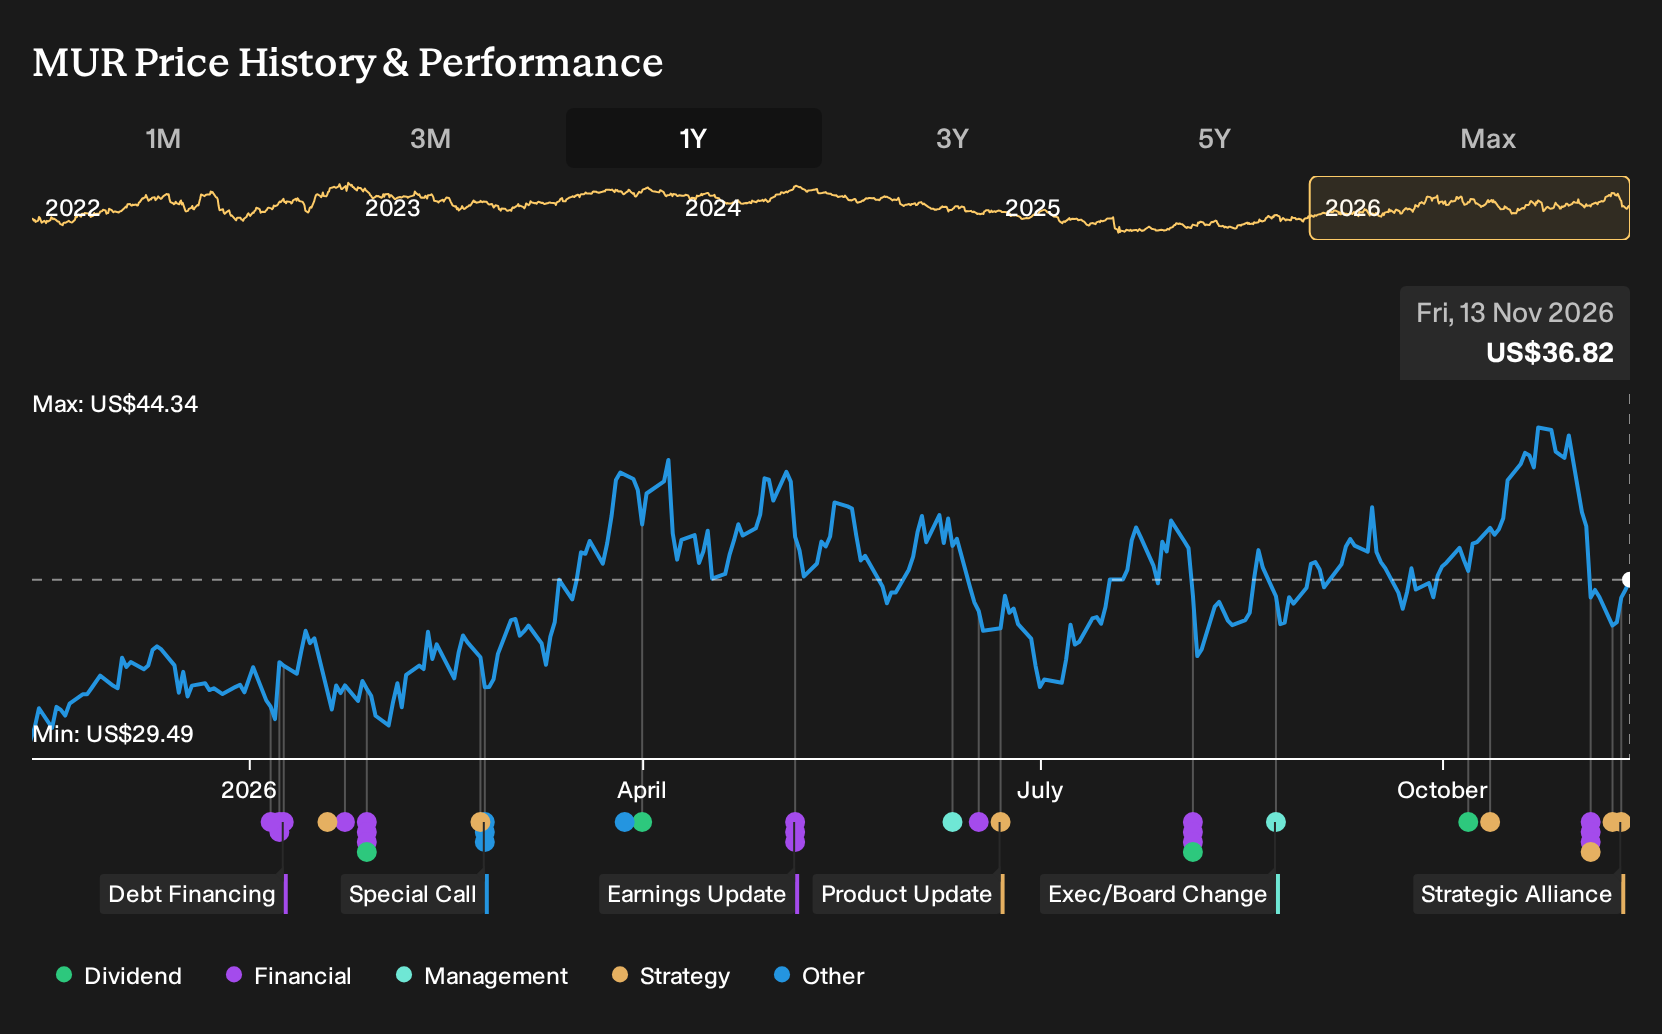
Uncover why Murphy Oil's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist you may want to test against this Cameroon and Israel news is the more optimistic revenue path. The most upbeat analysts were pencilling in about US$4.1b of revenue and US$1.2b of earnings by 2029, far above consensus. Those projections were set before these offshore deals, so viewpoints may shift in very different directions.
Explore 2 other Murphy Oil fair value estimates, including one that suggests up to 226% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Murphy Oil research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Murphy Oil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Murphy Oil's overall financial health at a glance.
Looking for more Murphy Oil style investment ideas?
If Murphy Oil has sharpened your view on what you want from an energy holding, you can use the Simply Wall St Screener to find other businesses that fit your risk, return and income preferences with the same level of transparency.
- If capital preservation is high on your list, start with a basket of resilient companies in our 29 resilient stocks with low risk scores to see which ones match your preferred downside profile.
- If balance sheet strength matters more than headline growth, filter for businesses with robust finances using the list of solid balance sheet and fundamentals (24 results) and compare their fundamentals side by side.
- If you want to cast a wider net beyond Murphy Oil, scan the 19 high quality undiscovered gems to spot lesser known opportunities with strong underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com