


EN
How Investors May Respond To Microsoft (MSFT) Global 365 Outage
- Microsoft experienced a major global outage of Microsoft 365 services, with Outlook, Teams, Copilot and related tools disrupted for more than 12 hours across over 70 countries, affecting business, government and consumer users before recovery efforts gradually improved service.
- The incident put a spotlight on how deeply organizations depend on Microsoft for day to day communication and workflow, and raised practical questions about resilience, redundancy and vendor concentration risk in critical productivity infrastructure.
- This article examines how Microsoft’s long term investment case intersects with the reliability questions raised by the extended Microsoft 365 outage.
Microsoft Investment Narrative Recap
To stay a Microsoft shareholder, you mostly need to believe that cloud, Microsoft 365, Copilot and Azure driven AI services remain central to how enterprises run critical work. According to CubanEros, an investor in the Simply Wall St Community, the key question is whether elevated AI capex near 37% of revenue earns solid returns without stressing the balance sheet, which is currently supported by net cash and high returns on equity.
Right now, the most important short term catalyst is how quickly Microsoft converts that AI infrastructure into usage across Azure, Copilot and enterprise contracts. The recent Microsoft 365 outage is a reputational issue, not a clearly material hit to demand so far. However, reliability will hang over renewal conversations and could sharpen scrutiny of capital allocation and operational execution.
The IBM partnership on Imagine Enterprise looks closest to the outage debate because it ties Microsoft’s AI stack directly into highly regulated industries where governance, security and reliability are non negotiable. This platform leans on Microsoft Foundry, Microsoft 365 infrastructure, Entra and Purview. These are the same layers customers now expect to be resilient after the disruption.
For investors watching catalysts, Imagine Enterprise gives Microsoft another route to embed AI agents into real workflows, with IBM Consulting bringing thousands of pre built agents and transformation projects. Execution risk sits in rolling these projects into production at scale without adding complexity or downtime. That consideration matters even more after a high profile resilience test like the recent outage.
CubanEros anchors a fair value of US$419.91 on Microsoft by assuming revenue expands at 10.2% a year and that the business eventually supports a future profit margin of 39.3%, which together indicate meaningful earnings power once current AI capex rolls into mature returns.
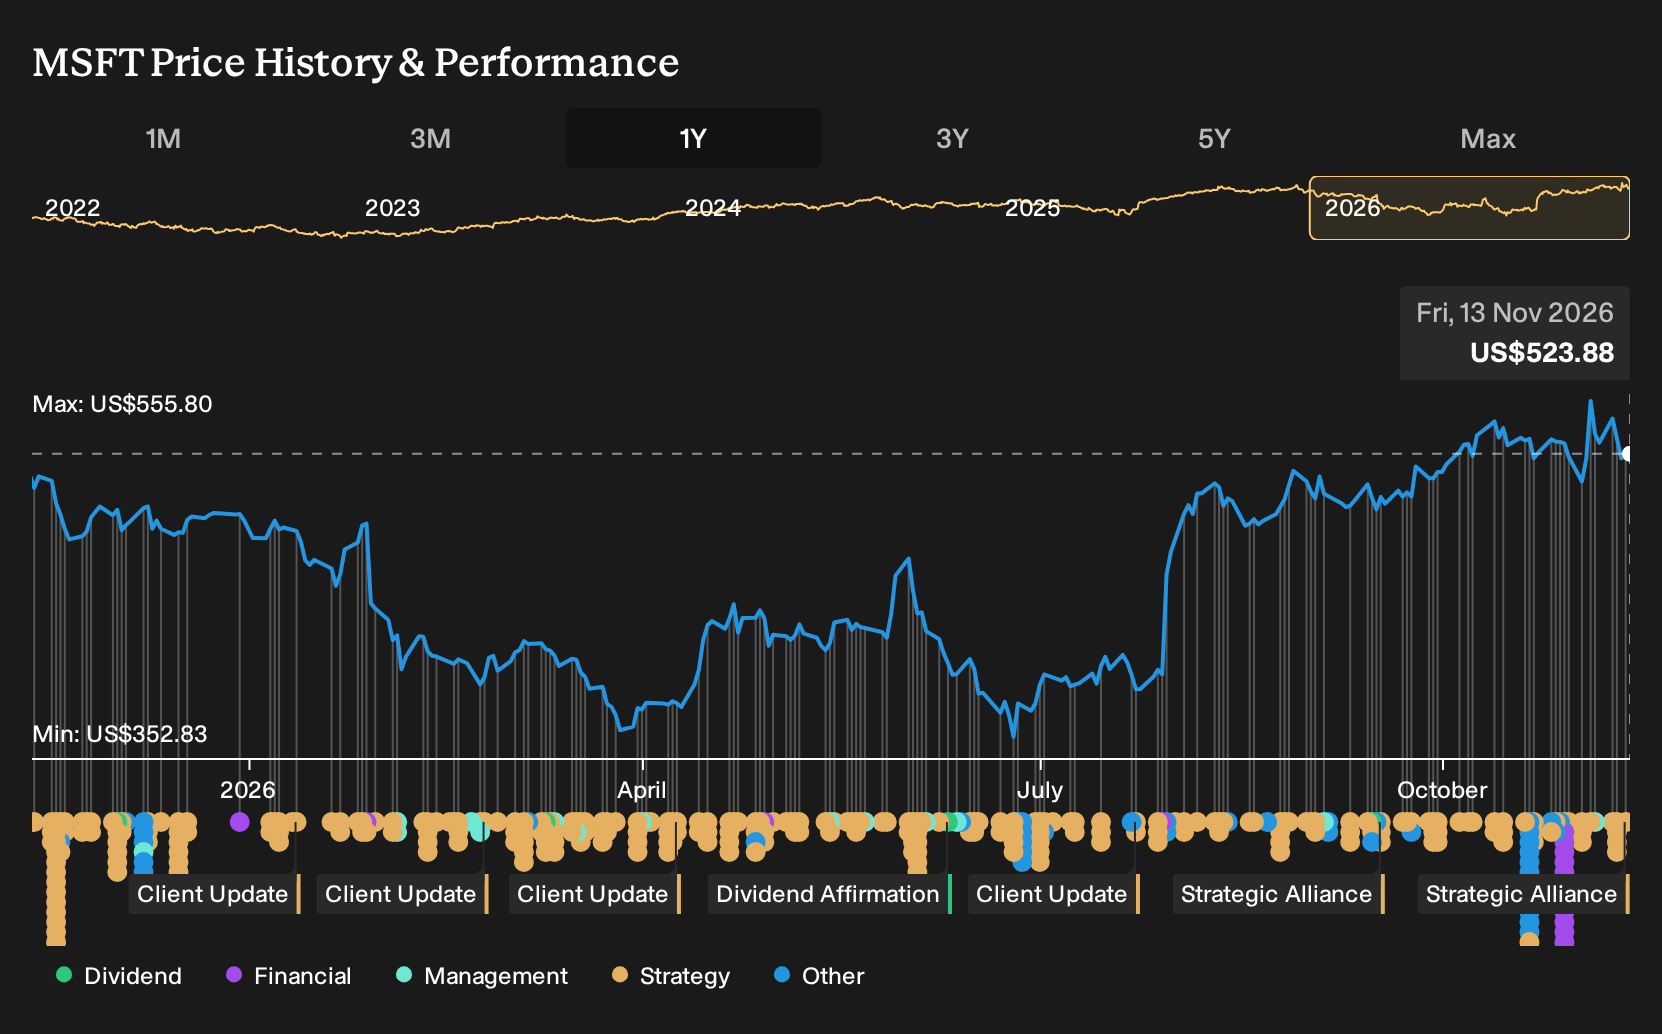
Uncover how Microsoft's fair value indicates a 20% potential downside to its current price, suggesting that the apparent premium may prove fragile.
Exploring Other Perspectives
Some of the lowest Microsoft analysts fixate on margin risk rather than outages. They already penciled in revenue of US$552.2b and earnings of US$185.7b by 2029, yet still saw room for profit compression and a P/E near 25.9x. After a reliability shock like this, that cautious story could easily get sharper.
Explore 68 other Microsoft fair value estimates, including one that suggests there could be as much as 20% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Microsoft research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Microsoft. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Microsoft's overall financial health at a glance.
Looking For More Investment Ideas Beyond Microsoft?
After weighing the outage story against the long term Microsoft thesis, it can help to widen the lens and see how other companies with different risk profiles line up. The Simply Wall St Screener gives you a quick way to filter for traits that fit your own approach instead of relying on a single tech giant.
If you want to stress test your portfolio against concentration risk and broaden your opportunity set, these focused screeners are a practical next step.
- Prefer stability over drama and want businesses that score well on resilience and financial strength? Start with a curated 29 resilient stocks with low risk scores that can help anchor a more durable portfolio.
- If value is your priority and you are hunting for quality paired with what looks like a discount, scan through a 34 high quality undervalued stocks that blends solid fundamentals with attractive pricing signals.
- Income matters for your plan and you care about cash coming back to you as an investor, consider companies in the 6 dividend fortresses that focus on higher-yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com