


EN
Sales Outlook Reset Might Change The Case For Investing In Terex (TEX)
- Terex announced refined full year 2026 net sales expectations of US$8b to US$8.2b and outlined plans to potentially separate its aerials division to concentrate capital on businesses it views as higher return.
- The focus on portfolio simplification, including a possible aerials spin, signals management attention on margin resilience and price cost balance under inflation and tariff pressures.
- The next section will assess how Terex's updated sales outlook and potential aerials separation could reshape the broader investment narrative.
Scan beyond Terex and compare how other capital intensive industrials are repositioning under inflation and tariff pressure with our hand picked list of solid balance sheet and fundamentals (24 results).
Terex Investment Narrative Recap
To own Terex, you need to be comfortable with a capital intensive manufacturer that leans heavily on construction, infrastructure and utility spending, and that is working to keep margins intact under inflation and tariff pressure. The analyst consensus Narrative on Simply Wall St is based on the idea that Terex can hold price cost balance while integrating Environmental Solutions and Specialty Vehicles.
From that perspective, the key near term catalyst is execution on the refined US$8b to US$8.2b 2026 net sales outlook and any decision on an aerials separation. The biggest immediate risk is still a pullback in equipment budgets or further margin compression, which would likely matter more than the latest headlines.
Within that backdrop, the retirement timeline for Patrick Carroll, who leads Environmental Solutions, looks more like a governance milestone than an operational shock. He plans to stay through May 2027 and the board expects to name a successor by the end of 2026, which gives Terex a long runway for continuity.
For you as a shareholder, the link back to catalysts is straightforward. Environmental Solutions is tied to utility and municipal spending, and management has already trimmed its second half 2026 outlook for that segment. Execution through this leadership change, and the quality of whoever takes over, will matter for how reliably Terex converts its backlog into earnings from that business.
Terex's narrative projects US$9.5b revenue and US$974.5m earnings by 2029. This assumes 12.5% yearly revenue growth and requires earnings to increase by about US$830m from US$145.0m today.
Uncover why Terex's fair value indicates a 40% potential upside to its current price, which could narrow quickly if Terex executes on its 2026 plan.
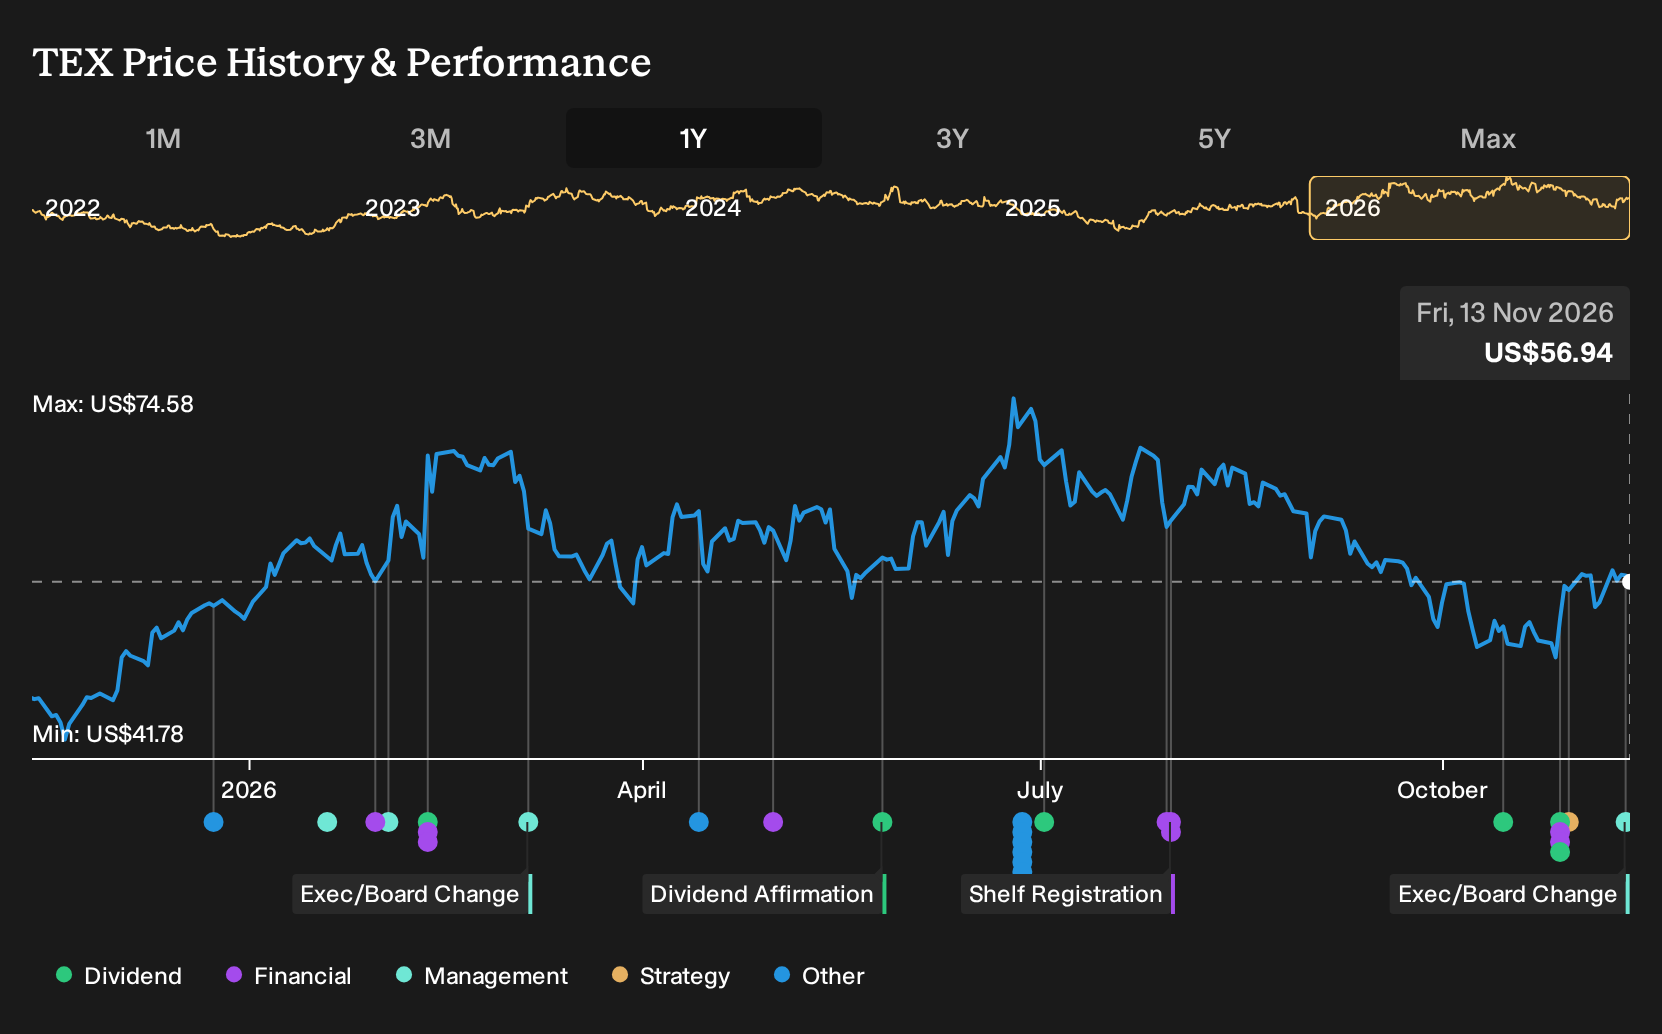
Exploring Other Perspectives
Some of the most optimistic Terex analysts focus on Environmental Solutions as the real swing factor. Before this leadership news, they were penciling in Terex revenue of about US$10.2b and earnings near US$1.0b by 2029, far above the lowest forecasts near US$779.6m. That is a very upbeat script. You should expect those views to evolve as investors reassess succession risk and execution through the retirement timeline. It is worth comparing these contrasting narratives before deciding how you feel about the stock.
Explore another Terex fair value estimate, including one that suggests as much as 73% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Terex research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Terex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Terex's overall financial health at a glance.
Looking for more Terex-style investment ideas?
If Terex fits your way of thinking but you want a broader watchlist, use the Simply Wall St screener to find other companies with traits that match your risk and return preferences.
- If you want potential mispricing with quality behind it, start with a curated group of 34 high quality undervalued stocks that combine strong fundamentals with appealing prices.
- If income matters to you, scan a focused pool of 6 dividend fortresses that aim to pair higher yields with resilient payouts.
- If capital preservation is a priority, build a shortlist from 29 resilient stocks with low risk scores where balance sheets and risk scores do more of the work.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com