


EN
How AI Growth Will Impact Yelp Stock
- Yelp reported third quarter 2026 sales of US$370.92 million and net income of US$34.55 million, with diluted EPS from continuing operations at US$0.63 and full year 2026 net revenue guidance maintained at US$1.455b to US$1.460b.
- The latest update shows advertising revenue under pressure. At the same time, Yelp’s AI driven products and data licensing, supported by new partnerships and more than 30 recent AI feature launches, are becoming a more meaningful part of the business mix.
- Next, the focus will be on how Yelp's investment narrative is shaped by leaning harder into AI and data licensing to counter softer ads.
Expand your watchlist beyond Yelp by scanning a hand picked set of AI focused peers and adjacent plays in the 42 AI small caps. These companies are also leaning hard into monetizing data and automation.
Yelp Investment Narrative Recap
To own Yelp today, you need to believe its AI products, subscriptions and data licensing can grow into a second leg of the story, while the core local ads business stays workable rather than sliding. The latest quarter keeps that debate open. Advertising revenue is under pressure, yet data and AI tied activity is picking up and helping hold the line on overall sales and EPS.
The key near term swing factor is still execution on tools like Yelp Assistant, Yelp Host and Hatch, and whether they can scale fast enough to matter at group level. The main risk is that weakness in restaurant, retail and other ad categories persists, while higher AI and marketing spend eats into margins faster than new revenue shows up.
The analyst consensus narrative on Simply Wall St leans heavily on AI features, subscription tools and content licensing as the engine that could offset softer local advertising. The third quarter update plugs directly into that idea. Yelp reported US$370.92 million of sales and US$34.55 million of net income, with diluted EPS from continuing operations at US$0.63, essentially keeping its near term thesis intact.
Management also confirmed full year 2026 net revenue guidance at US$1.455b to US$1.460b. For investors tracking catalysts, that matters because it signals no reset to the immediate revenue storyline even as ad categories feel pressure. It keeps the focus squarely on whether AI driven products and data licensing can continue to gain relevance without letting cost inflation or legal issues drag on earnings.
What Analysts Are Baking Into The Yelp Story
Analysts covering Yelp are effectively sketching out a slow build scenario rather than a dramatic reset. The forecasts assume revenue grows by 2.3% a year over the next three years, helped by a gradual lift in profit margins from 8.3% today to 10.1% over that stretch. The earnings side of the spreadsheet points to US$121.7 million today rising to US$159.6 million by 2029, which is about a US$38 million step up on the bottom line if those estimates play out. That earnings profile underpins the idea that AI driven tools, subscriptions and data licensing can do more of the heavy lifting if local advertising stays sluggish.
On those same assumptions, the analyst framework ties the story together with a 2029 snapshot that includes US$1.6b of revenue and US$159.6 million of earnings. That period is also where the model lines up a P/E of 8.2x on those projected profits, compared with 8.7x on earnings today and 9.0x for the wider US Interactive Media and Services industry. The revenue line in that 2029 view implies moderate top line expansion while the earnings jump relies on margin gains, share count reduction of about 7% a year over the next three years and continued cost discipline as Yelp invests in AI products and marketing.
Yelp's narrative projects revenue of US$1.6b and earnings of US$159.6 million by 2029. This assumes yearly revenue growth of 2.3% and an earnings increase of about US$38 million from US$121.7 million today.
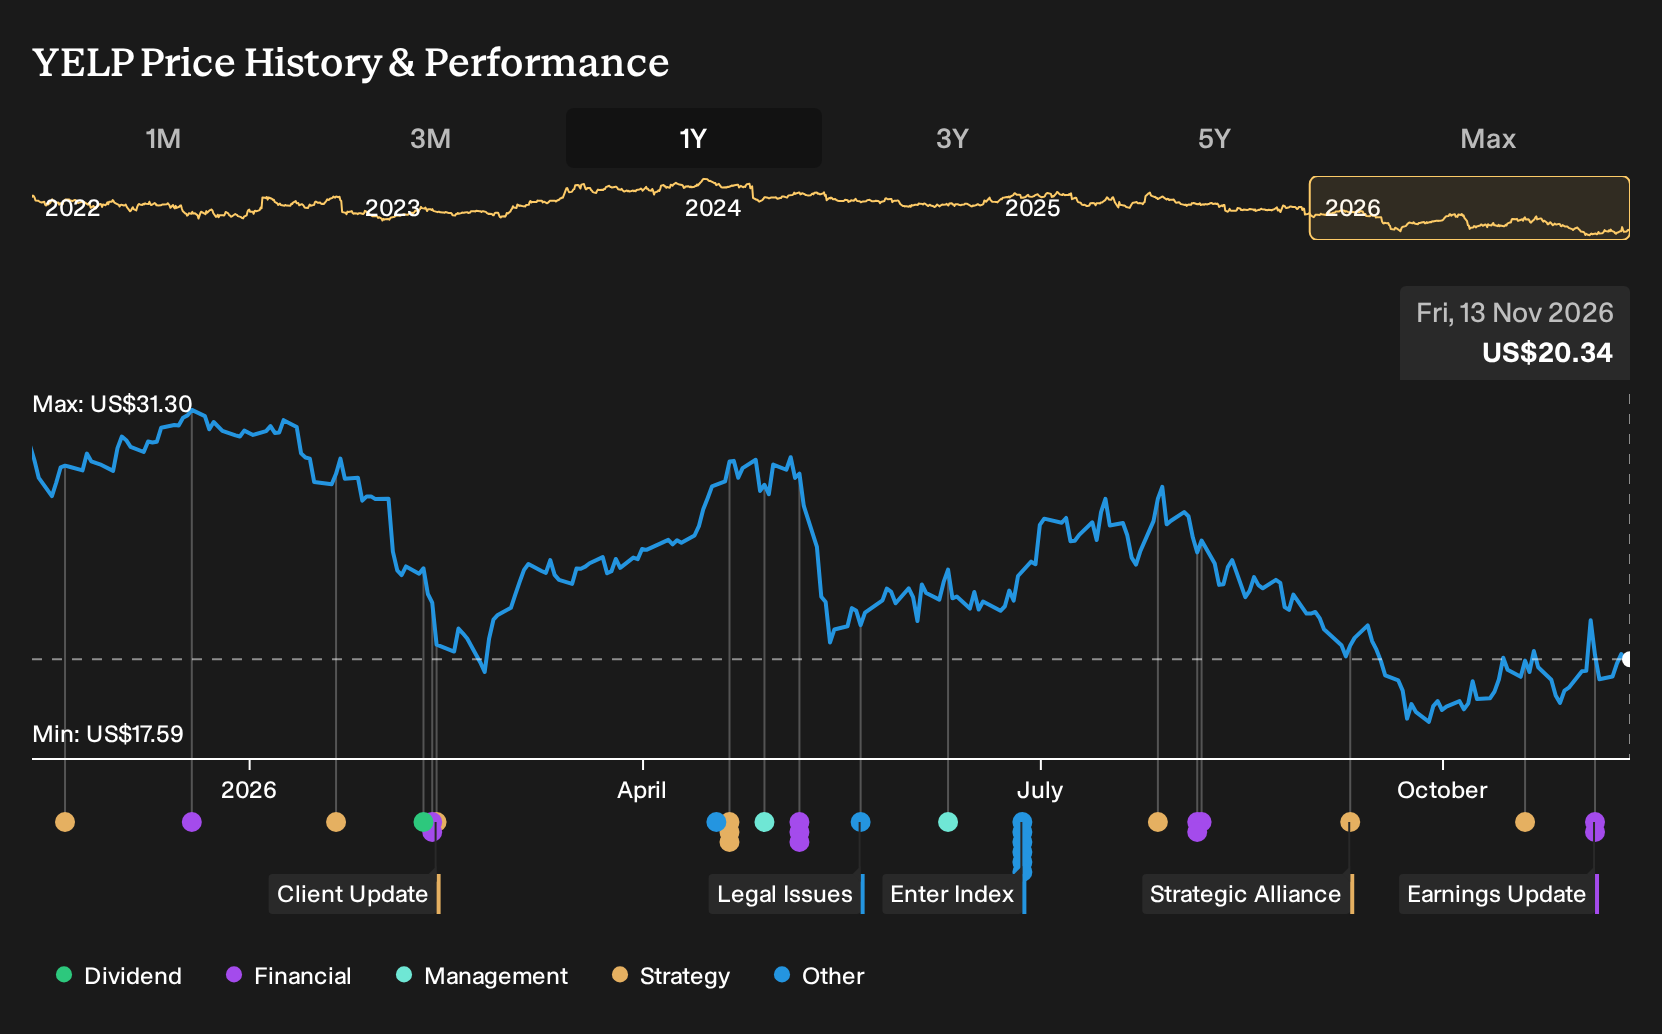
Uncover how Yelp's fair value indicates a 14% potential upside to its current price before buyers close that discount.
Exploring Other Perspectives
Some of the most optimistic analysts treat the recent AI surge at Yelp as a potential accelerant. Before this earnings release, the bullish camp was modeling revenue rising about 3.1% a year and earnings reaching roughly US$171.9 million by 2029. You can compare that more upbeat script with the softer quarter and decide whether their story still holds up.
Explore 4 other Yelp fair value estimates, including one that suggests up to 250% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Yelp research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Yelp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yelp's overall financial health at a glance.
Looking For More Ideas Beyond Yelp?
Once you have a handle on Yelp, it often helps to broaden your watchlist with companies that share similar quality traits or income profiles. The Simply Wall St Screener can surface a range of candidates that fit different goals, from resilient balance sheets to income focused opportunities.
- For investors who care most about stability and financial strength, filter for companies with robust cash buffers and modest leverage using the list of solid balance sheet and fundamentals (24 results).
- If your priority is long term income, narrow in on reliable payers offering higher yields by scanning the 6 dividend fortresses.
- For readers hunting for underappreciated opportunities with strong fundamentals, cast a wider net with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com