


EN
Advanced Drainage Systems (WMS) Lifts Outlook And Dividend, Is The Stock Still Cheap?
Advanced Drainage Systems (WMS) recently rewired its financing, investor payouts and outlook in a tight cluster of November moves, putting fresh attention on the stock’s balance sheet flexibility and acquisition plans.
Advanced Drainage Systems has seen its share price slide over the past quarter, with a 90 day share price return of 15.14% down and a year to date share price return of 16.07% down, even as the 1 year total shareholder return of 12.49% down contrasts with a positive 3 year total shareholder return of 6.58%. This suggests that longer term holders may view the recent pullback and the cluster of credit, dividend and guidance announcements as a reset in risk and growth expectations rather than a broken story.
Compare how Advanced Drainage Systems stacks up on balance sheet strength and capital discipline against a hand picked list of solid balance sheet and fundamentals (24 results).
Advanced Drainage Systems now trades at a clear discount to both analyst targets and estimated fair value after its recent financing and payout moves. Is that a pricing error, or a reasonable margin for execution risk and acquisition plans?
Most Popular Narrative: 29.6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Advanced Drainage Systems carries a fair value estimate of $178.36 against a last close of $125.58. This frames the recent refinancing and payout moves as happening against a discounted share price based on an 8.88% discount rate and detailed revenue and earnings forecasts.
Active use of a strong balance sheet and free cash flow, including the largely cash funded NDS acquisition that is tracking ahead of the US$25 million synergy target and continued dividends and share repurchases, gives Advanced Drainage Systems room to pursue further system level water management offerings and potential scale benefits that can support revenue and earnings growth.
See why 10 investors see Advanced Drainage Systems as 30% undervalued.
Result: Fair Value of $178.36 (UNDERVALUED)
Still, the Advanced Drainage Systems story can be knocked off course if construction demand stays sluggish and resin and freight costs keep pressuring profitability.
Find out about the key risks to this Advanced Drainage Systems narrative.
Another View: What The P/E Ratio Says About Advanced Drainage Systems
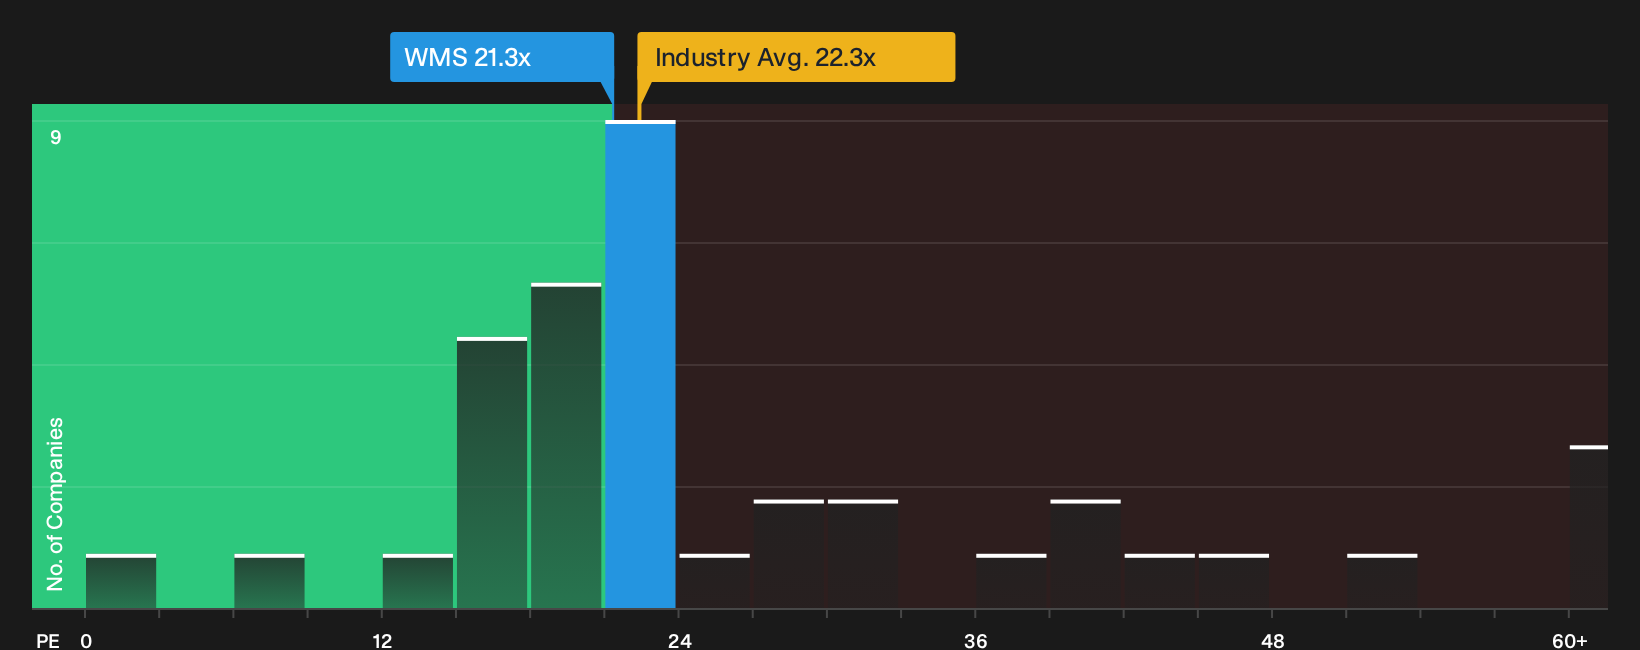
The DCF work suggests Advanced Drainage Systems looks undervalued, yet the market is not giving it away on simple earnings multiples. The stock trades on a P/E of 21.3x, slightly below the US Building industry at 22.3x but below a fair ratio of 25.3x that the SWS model suggests the market could drift toward over time.
That mix of a modest discount to peers and a wider gap to the fair ratio points to a balance of potential opportunity and rerating risk that each investor has to weigh against their own expectations for execution, demand and margins.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on whether the recent moves at Advanced Drainage Systems signal a reset or a real problem. Act quickly, review the data yourself to decide where you land, then weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Advanced Drainage Systems?
If Advanced Drainage Systems has your attention, do not stop there. Broaden your watchlist with fresh setups that match how you like to balance risk and reward.
- Target resilient quality by scanning a curated 29 resilient stocks with low risk scores that aims to limit downside while still giving you meaningful upside potential to assess.
- Hunt for mispriced potential and review a focused 19 high quality undiscovered gems that highlights strong businesses the wider market may not be watching yet.
- Build your own shortlist of sturdier balance sheets and steady execution by working through a hand picked list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com