


EN
Nisshin OilliO GroupLtd (TSE:2602) Released Half Year Earnings, Is The Valuation Already Full?
Nisshin OilliO GroupLtd (TSE:2602) has just paired its half year earnings release with a board meeting focused on potential changes to the shareholder benefit program, a combination that directly targets both fundamentals and investor perks.
The recent half year release and board meeting follow a period of clear price momentum in Nisshin OilliO GroupLtd, with the share price up 23.17% year to date and a 1 year total shareholder return of 31.15%, indicating strengthening sentiment.
Scan how Nisshin OilliO GroupLtd compares to other consumer staples gaining attention this year by reviewing the curated 19 resilient stocks with low risk scores.
After a strong run and with Nisshin OilliO GroupLtd now trading above the average analyst target, the gap between the share price and fair value estimates has widened. The key question is where within that range a reasonable valuation case is likely to fall next.
Preferred P/E of 16.2x: Is it justified for Nisshin OilliO GroupLtd?
Nisshin OilliO GroupLtd trades on a P/E of 16.2x, which screens as expensive against both its peer group and the sector average even after the recent share price strength.
The P/E ratio compares the current share price to earnings per share and effectively tells you how many years of current profits the market is willing to pay for. For a mature food and ingredients business, that multiple often reflects how confident investors are that profit growth can continue without major volatility.
Here, the market is assigning Nisshin OilliO GroupLtd a P/E of 16.2x, while the peer average sits at 11.6x, which is a much lower bar. That premium suggests investors are paying up for its earnings profile. At the same time, the estimated fair P/E of 18.1x points to some headroom if sentiment and profit delivery remain aligned with those expectations.
Relative to the broader JP Food industry, which also trades on 16.2x P/E, Nisshin OilliO GroupLtd is priced in line with sector norms, yet still below the 18.1x level that the SWS fair ratio suggests the valuation could move towards if market expectations converge on that benchmark.
Explore the SWS fair ratio for Nisshin OilliO GroupLtd.
Result: Price-to-Earnings of 16.2x (ABOUT RIGHT)
Still, higher expectations around Nisshin OilliO Group Ltd leave little margin for disappointment if earnings growth cools or if input cost pressures compress profitability.
Find out about the key risks to this Nisshin OilliO GroupLtd narrative.
Another view on Nisshin OilliO GroupLtd’s value
The SWS DCF model tells a different story for Nisshin OilliO GroupLtd. With the share price at ¥2,176 and the future cash flow value estimated at ¥1,503.94, the stock screens as overvalued. That gap raises a simple question for you: Which signal carries more weight, earnings multiples or long term cash flows?
Look into how the SWS DCF model arrives at its fair value.
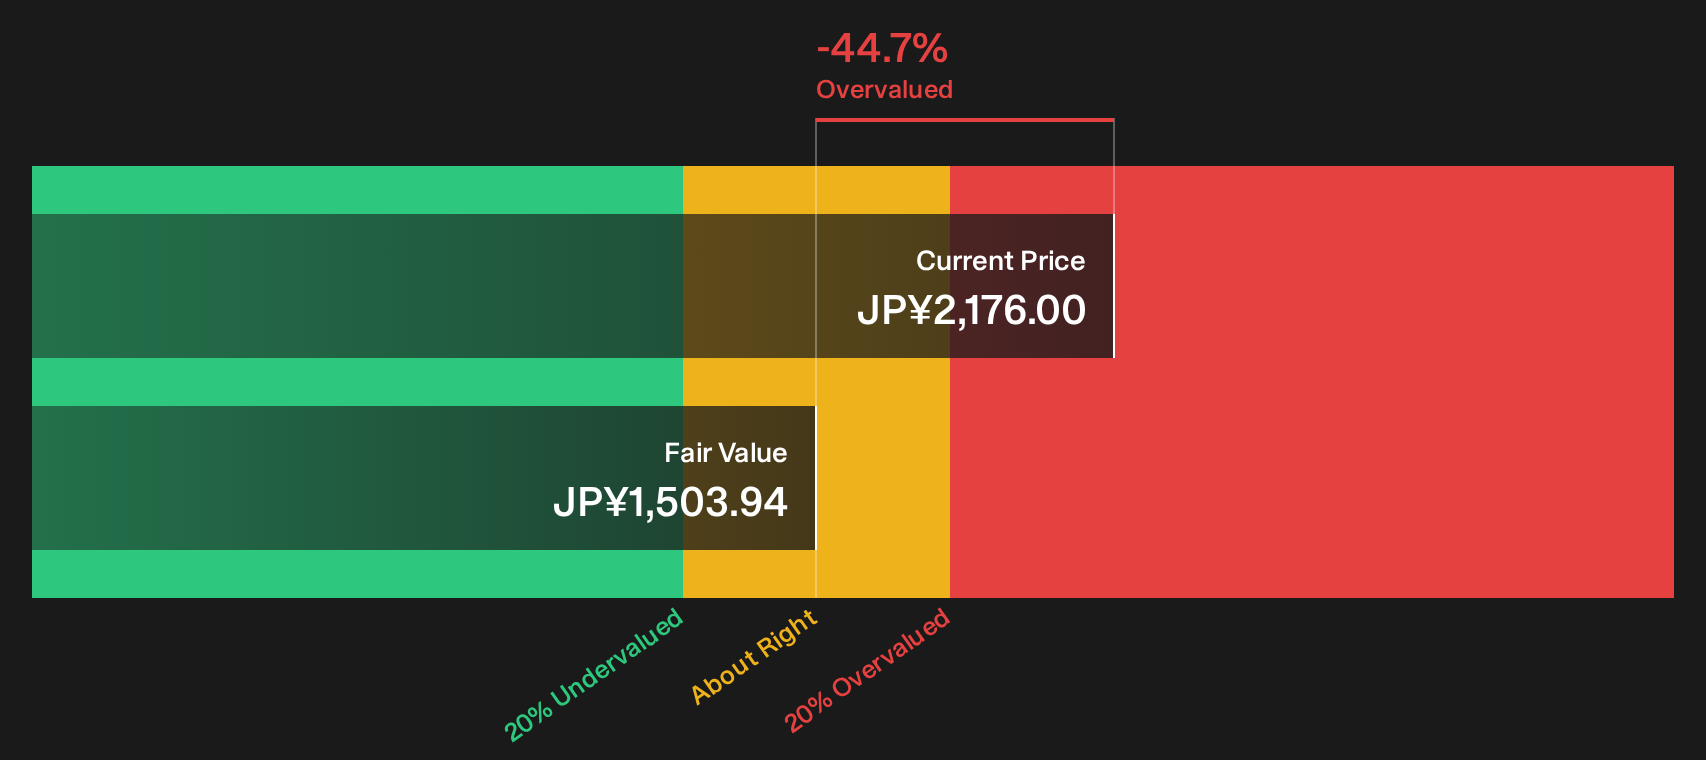
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nisshin OilliO GroupLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Nisshin OilliO GroupLtd so far. If you want to move quickly and firm up your own stance, start by weighing the 1 key reward and 3 important warning signs.
Looking for more Nisshin OilliO GroupLtd style investment ideas?
If Nisshin OilliO GroupLtd has sharpened your focus on pricing power and risk, now is the moment to widen your watchlist with fresh opportunities.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing entry points through the 18 high quality undervalued stocks.
- Strengthen your income stream by reviewing the 29 dividend fortresses that screen for companies offering higher yields with defensive characteristics.
- Prioritise resilience by filtering for financially robust businesses in the list of solid balance sheet and fundamentals (24 results) so you are not late to the next opportunity set.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com