


EN
What Packaging Corp. Doubters Overlooked
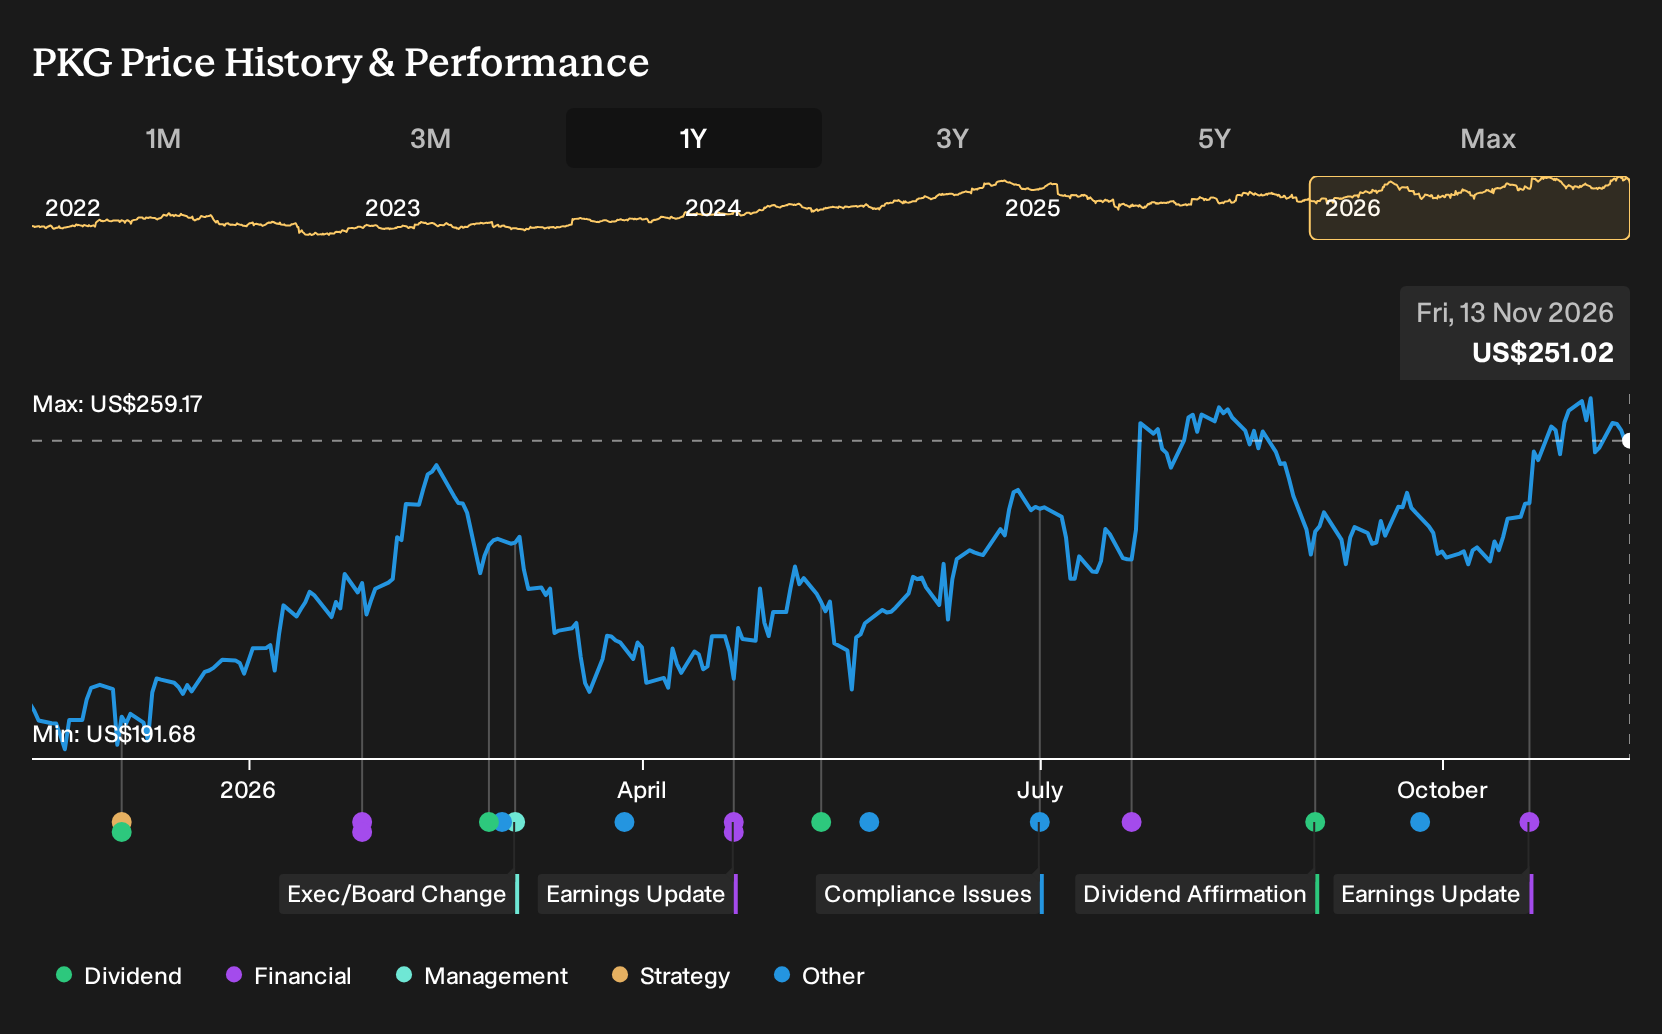
If you had bought Packaging Corporation of America back in mid November 2025, the call you faced looked anything but one sided. Investors who held Packaging Corporation of America over the past year are up 30.5%, including dividends. At the time, upbeat views on price increases and the Greif acquisition collided with worries about aging assets, digital substitutes for boxes, and slower end markets. If you were weighing that choice then, which of those trade offs would have carried more weight for you?
Packaging Corporation of America has already moved. See which of 34 high quality undervalued stocks still trade below our estimates.
The Two Stories Packaging Corporation of America Investors Were Choosing Between
The shares cost US$199 at the start of the period. Anyone looking at Packaging Corporation of America then had to decide whether recent pricing moves and the Greif deal would matter more than aging mills and new packaging formats.
The bullish story pointed to a Fair Value of US$216, an implied upside figure based on assumptions like 4.9% annual revenue growth and a 12.0% profit margin over about three years.
The cautious camp leaned on a Fair Value of US$152, built around concerns that digitalization and reusable containers could steadily reduce corrugated demand over time.
What The Results Changed For Packaging Corporation of America
The key test for Packaging Corporation of America was whether higher prices and the Greif integration would show up in the accounts. Q3 2026 revenue of US$2.60b compared with US$2.31b a year earlier, and net income also rose. Net margin edged up from 9.7% to 10.0%, which leaned toward the bullish case on profitability.
The lesson to carry across is simple. When a company leans on pricing power and acquisitions, track whether margin and absolute profit move together in reported results rather than relying on the story alone.
What Today's Packaging Corporation of America Price Already Assumes
Packaging Corporation of America now trades at US$251 after a 30.5% gain over the past year. The bearish analyst Narrative on Simply Wall St sets its Fair Value below that level, based on concern that input costs and heavy capital spending could eat into the benefit of firm pricing.
A buyer today is effectively betting that mill upgrades, capex and the Greif integration translate into durable efficiency gains. The key question is how the cost and utilization pressures highlighted in the Narrative affect that assumption.
"Although Packaging Corporation of America has been able to lift net sales, the Q2 2026 margin compression, with operating margin at 11.7% versus 15.4% a year earlier, signals that higher freight and recycled fiber costs could keep outpacing pricing actions and volume. This would keep pressure on net margins and earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Beyond Packaging Corporation of America
After looking at Packaging Corporation of America, you might stop at boxes and mills. You do not have to.
The same customers chasing packaging efficiency are also working with denser chips and more complex electronics. That jump in complexity needs far more rigorous automated testing.
Another business builds the test systems and robotics that help customers check those advanced devices and keep factories running.
As chip and hardware designs grow tougher to validate, that testing specialist could see its role quietly expand in the background.
The case is written up, with the assumptions it depends on. → Discover the robotics company one Narrative values 67% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com