


EN
New Engine Launch Might Change The Case For Investing In AGCO Stock (AGCO)
- AGCO Power’s CORE engine family, including the CORE75 platform, was showcased in past EIMA International 2026 exhibits inside new Massey Ferguson MF 7S MARK 2 and sixth generation Valtra T Series tractors. This underlined a clean sheet engine program aimed at demanding off highway uses and multiple power needs.
- The display of award winning CORE75 and CORE80 engines highlighted AGCO’s commitment to off highway combustion engine development at a time when fewer manufacturers are committing fresh capital to this area. This focus speaks directly to long term product differentiation and potential cost efficiency in high duty cycle equipment.
- We will now look at how AGCO’s new CORE75 engine platform appearing in Massey Ferguson and Valtra tractors could influence the investment narrative.
AGCO Investment Narrative Recap
To own AGCO, you need to believe that a mix of precision ag software, higher value equipment and internal cost work can gradually lift margins despite choppy machinery demand. The analyst consensus narrative on Simply Wall St leans on that idea, with PTx, Fendt and cost programs doing the heavy lifting over time.
Near term, CORE engines in Massey Ferguson and Valtra tractors help the operating story but probably do not change the biggest swing factors. The key catalyst remains execution on PTx and cost efficiencies. The main risk is that already soft demand in North America and Latin America lingers and net tariff costs keep pressuring margins.
The CORE75 platform getting broader use in tractors matters most right now. It shows AGCO investing in its own powertrain at a time when some peers are less active in off highway engines. That can influence long term differentiation, parts pull through and how effectively AGCO controls performance and servicing economics.
For catalysts, this engine program sits alongside the push to scale PTx precision ag, retrofit solutions and the FarmerCore service model. Together, these efforts aim to build a higher margin, more recurring mix while the firm deals with weaker volumes, under absorption and roughly US$93m to US$95m of expected 2026 tariff headwinds.
AGCO's narrative projects US$12.2b revenue and US$871.8m earnings by 2029, based on analyst consensus. This implies 5.5% yearly revenue growth and an earnings increase of about US$338.4m from current earnings of US$533.4m.
Uncover how AGCO's fair value indicates an 11% potential upside to its current price that could narrow quickly.
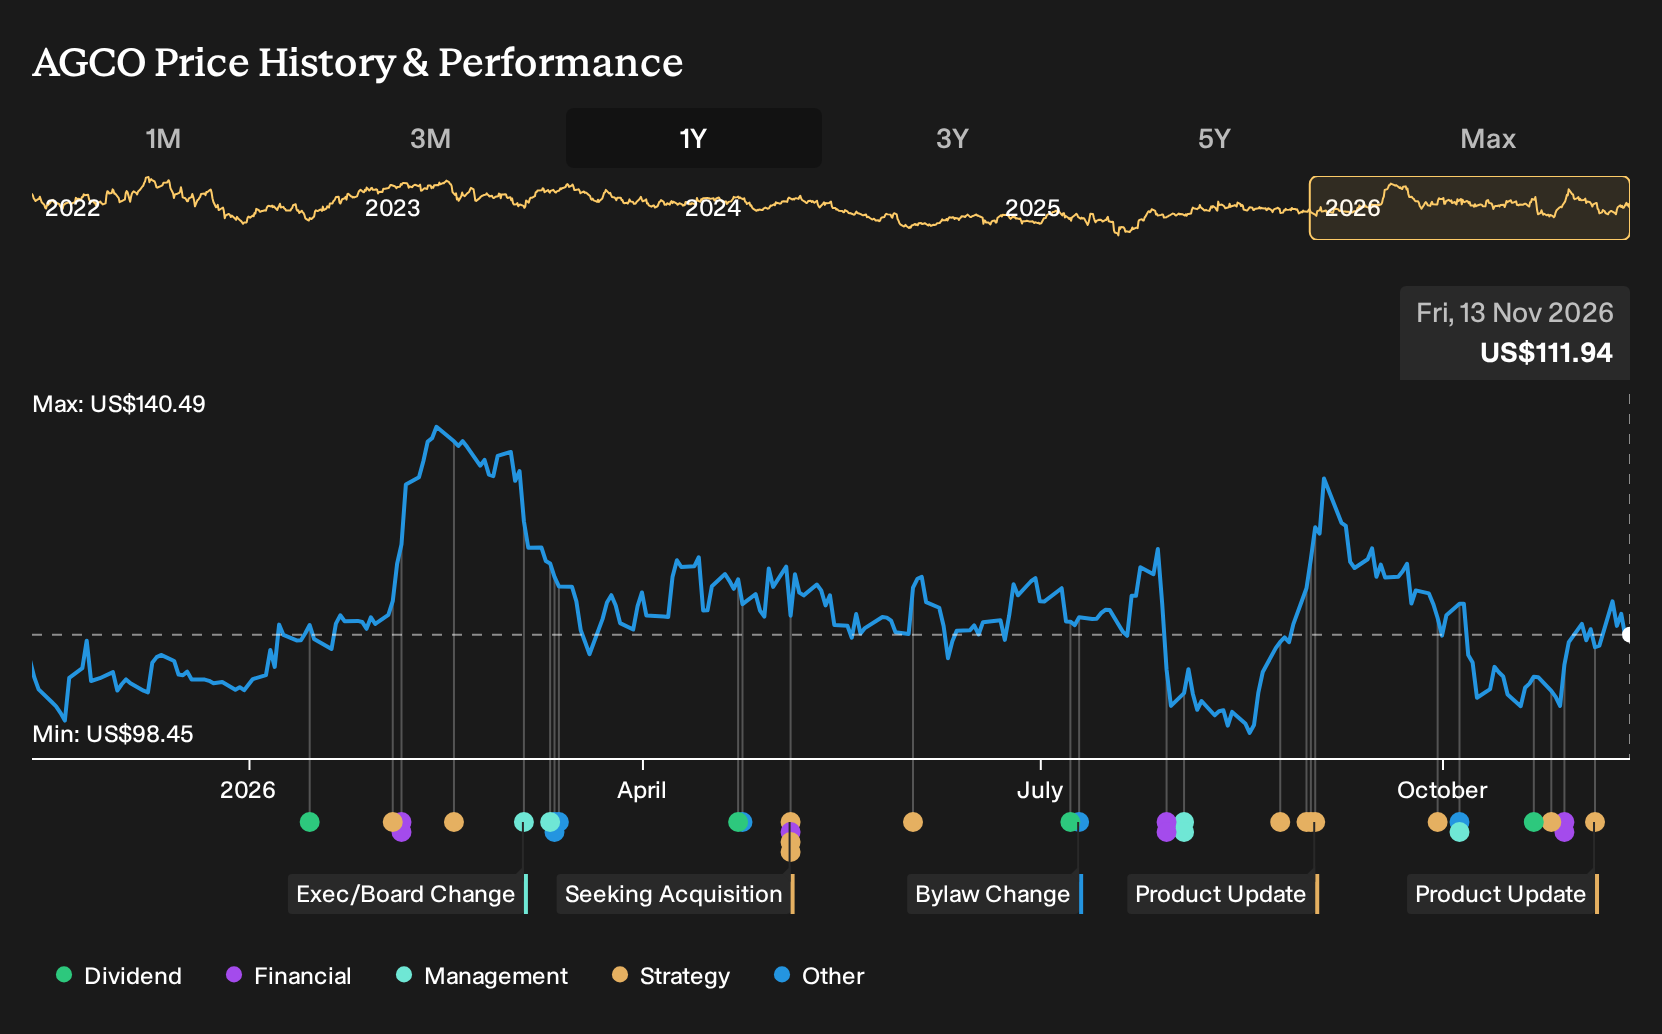
Exploring Other Perspectives
One bullish twist on AGCO focuses on a potential production rebound rather than just CORE75 and tariffs. The most optimistic analysts were pencilling in US$12.5b of revenue and US$1.1b of earnings by 2029 before this engine news. That is far above the cautious end of forecasts, so treat it as one of several viewpoints to stress test.
Explore 3 other AGCO fair value estimates, including one that suggests up to 41% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AGCO research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AGCO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AGCO's overall financial health at a glance.
Looking for more investment ideas beyond AGCO?
If AGCO has sharpened your interest in equipment and capital goods, you can broaden your watchlist by scanning other businesses that match your risk, income and quality preferences using the Simply Wall St Screener.
- For investors who want potential mispricings backed by fundamentals, start with 34 high quality undervalued stocks and see which companies currently screen as both strong and potentially cheap.
- If capital preservation and steadier profiles matter most to you, narrow your search using 29 resilient stocks with low risk scores, which focuses on resilient balance sheets and lower risk scores.
- When you want to look for under the radar opportunities with solid underlying numbers, filter the market through 19 high quality undiscovered gems and see which smaller companies pass the quality checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com