


EN
Porch Group (PRCH) Is Back In Focus, What Is Catching Attention Now?
Porch Group (PRCH) is back in focus after reporting quarterly revenue growth of 13% and a very large jump in earnings per share, which is putting fresh attention on how the business is priced today.
Porch Group’s recent earnings have arrived alongside strong price momentum, with the share price up 20.3% over the past 30 days and 25.6% over 90 days, contributing to a 128.3% year to date share price return and a very large 3 year total shareholder return. However, shorter term softness in the latest 1 day move hints at investors reassessing how much of that earnings jump is already reflected in today’s US$21.05 share price.
Scan how Porch Group compares to other fast moving financial and insurance plays with the hand picked list of 19 high quality undiscovered gems in this corner of the market.
The question now hangs over Porch Group. Do you pay up after a sharp run, or wait for the valuation to cool before considering a fresh entry point?
Most Popular Narrative: 17.2% Undervalued
Porch Group’s analyst consensus Narrative on Simply Wall St points to a fair value of $25.43 per share, above the latest $21.05 close. This frames the recent rally against a valuation story that still leans to the optimistic side.
The main thing that has to go right is that Porch Group continues to convert Reciprocal written premium and the Allied Trust integration into sustained high margin adjusted EBITDA, while managing underwriting quality and reinsurance so surplus keeps supporting premium growth.
The current narrative that Porch Group is undervalued implies the share price does not fully reflect reported Insurance Services growth, improved company wide adjusted EBITDA, and the capital position that includes rising cash, lower net leverage, and growing Reciprocal surplus.
See why 8 investors see Porch Group as 17% undervalued.
Result: Fair Value of $25.43 (UNDERVALUED)
Still, the Porch Group story can be knocked off course if housing related Software & Data softness persists, or if data driven underwriting missteps push loss ratios higher.
Find out about the key risks to this Porch Group narrative.
Another View: Porch Group On Sales-Based Valuation
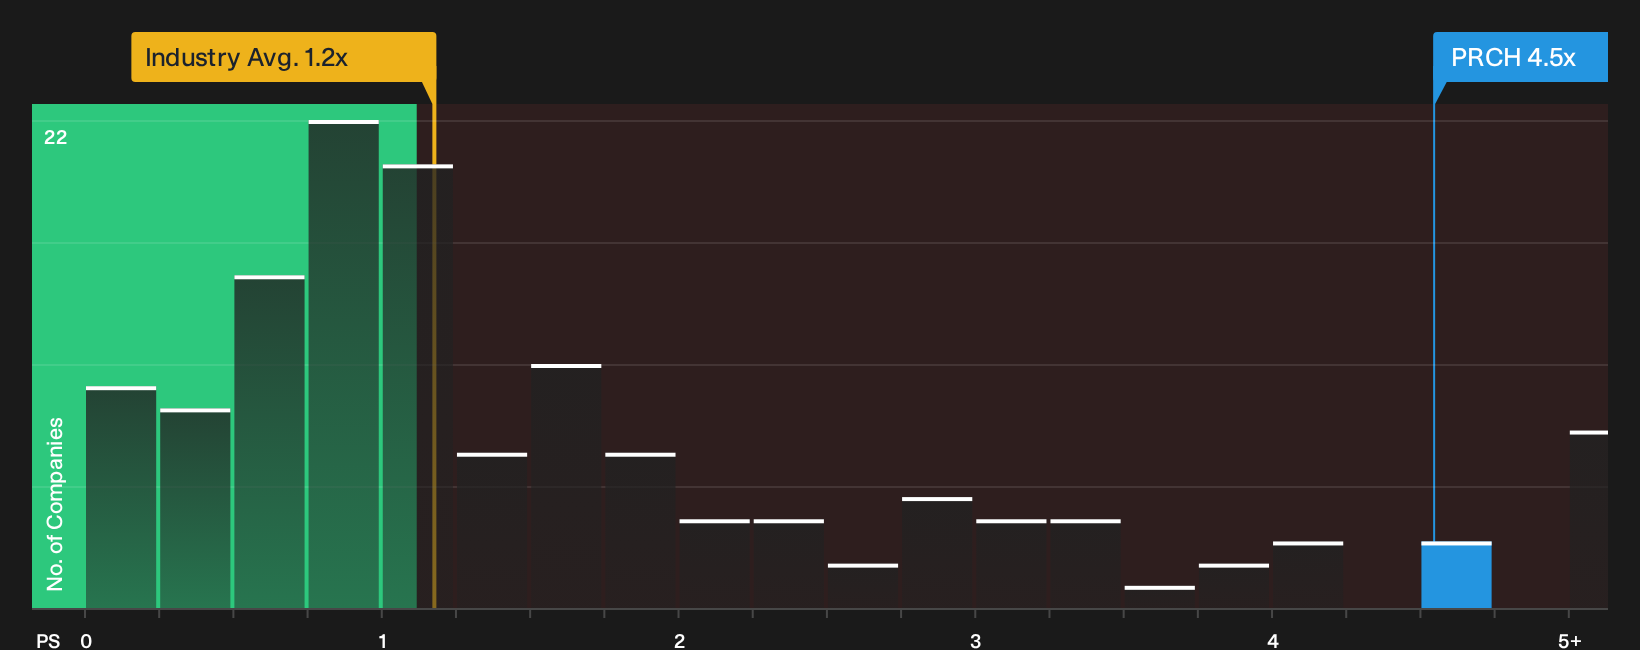
Porch Group screens as expensive on a simple P/S lens. The stock trades at 4.5x sales compared with 1.2x for the wider US Insurance group and 1.3x for peers, while the fair ratio is 2.2x. That gap points to richer expectations baked into the price. The key consideration is whether you think the market eventually leans toward that fair ratio.
For a closer look at how these multiples line up with the underlying fundamentals and where valuation pressure could show up next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The Porch Group story presents a mixed picture, with both risks and rewards on the table. Act while the details are fresh in mind and weigh the upside against the concerns by checking the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Porch Group?
Do not stop your research with Porch Group. Broaden your watchlist with a few focused screens that spotlight different types of opportunities and help you pressure test your next move.
- Target higher potential upside by scanning for companies that screen as 19 high quality undiscovered gems before wider attention catches up.
- Prioritise resilience and capital strength by checking companies in the list of solid balance sheet and fundamentals (24 results) that can better handle tougher conditions.
- Dial down risk while still hunting for returns with a curated 29 resilient stocks with low risk scores that filters for more stable profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com