


EN
enCore Energy Corp.'s (CVE:EU) Shift From Loss To Profit
We feel now is a pretty good time to analyse enCore Energy Corp.'s (CVE:EU) business as it appears the company may be on the cusp of a considerable accomplishment. enCore Energy Corp., together with its subsidiaries, engages in the acquisition, exploration, development, and extraction of uranium resource properties in the United States. The CA$153m market-cap company posted a loss in its most recent financial year of US$57m and a latest trailing-twelve-month loss of US$92m leading to an even wider gap between loss and breakeven. Many investors are wondering about the rate at which enCore Energy will turn a profit, with the big question being “when will the company breakeven?” We've put together a brief outline of industry analyst expectations for the company, its year of breakeven and its implied growth rate.
According to the 6 industry analysts covering enCore Energy, the consensus is that breakeven is near. They anticipate the company to incur a final loss in 2027, before generating positive profits of US$2.8m in 2028. So, the company is predicted to breakeven approximately 2 years from today. What rate will the company have to grow year-on-year in order to breakeven on this date? Using a line of best fit, we calculated an average annual growth rate of 75%, which is extremely buoyant. If this rate turns out to be too aggressive, the company may become profitable much later than analysts predict.
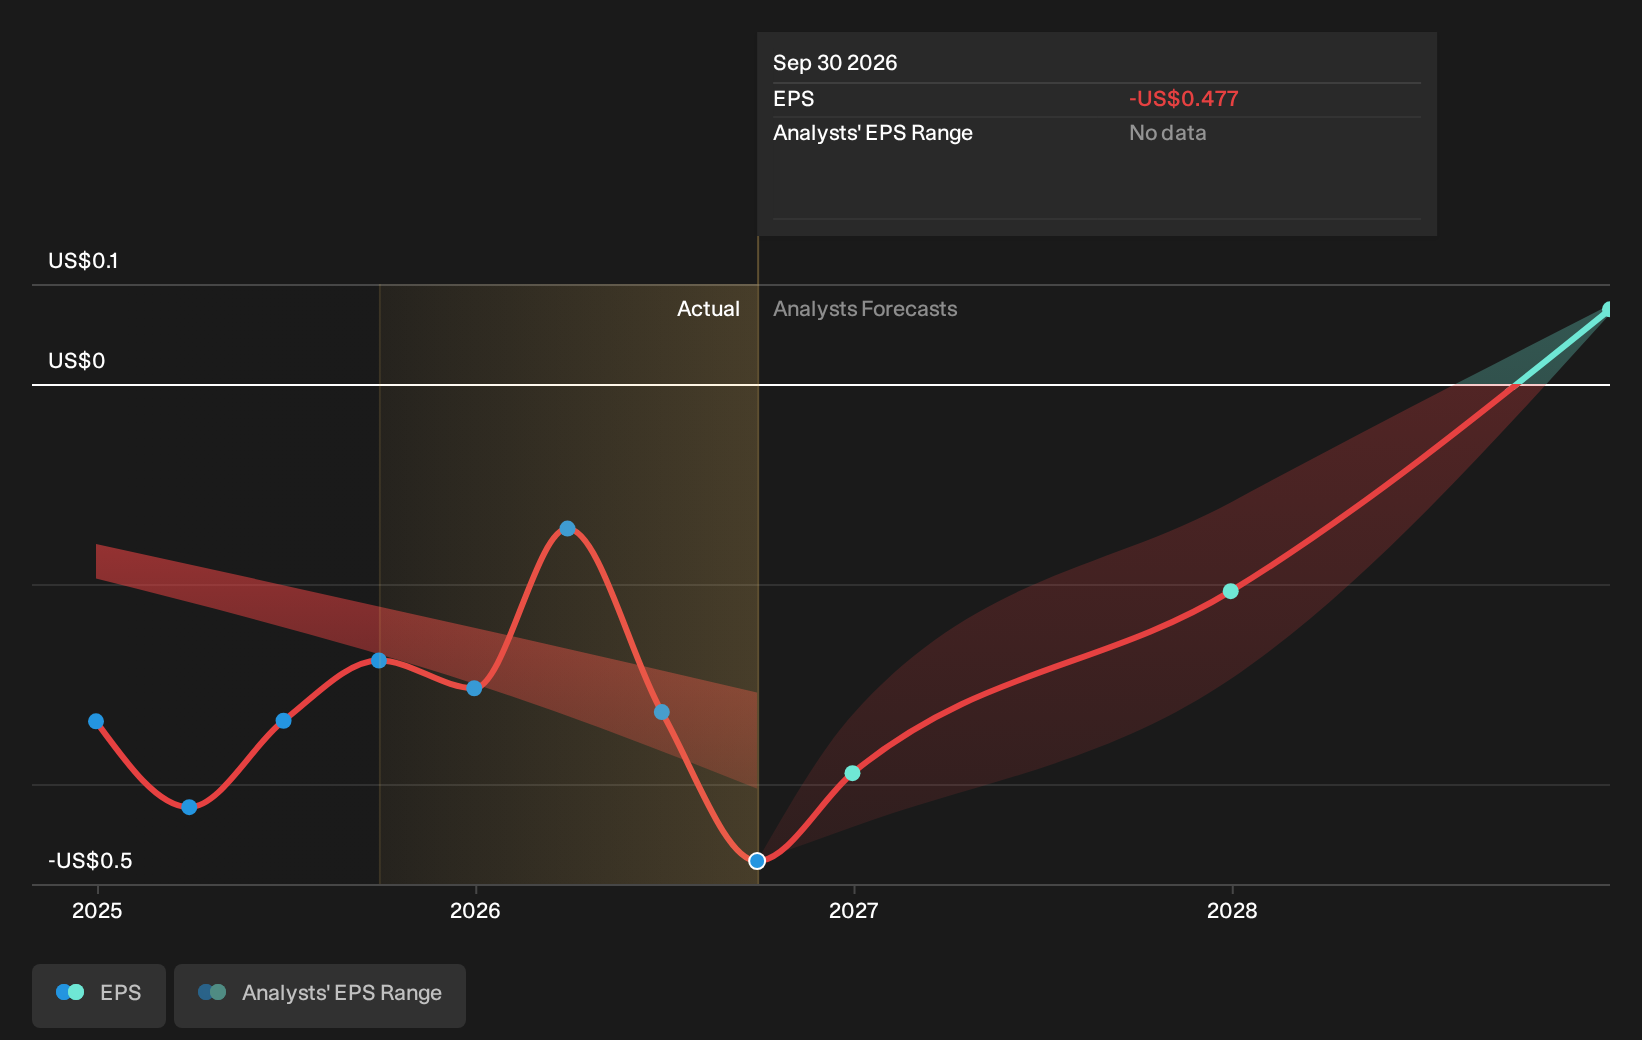
We're not going to go through company-specific developments for enCore Energy given that this is a high-level summary, but, take into account that generally an energy business has lumpy cash flows which are contingent on the natural resource and stage at which the company is operating. So, a high growth rate is not out of the ordinary, particularly when a company is in a period of investment.
Check out our latest analysis for enCore Energy
One thing we would like to bring into light with enCore Energy is its relatively high level of debt. Generally, the rule of thumb is debt shouldn’t exceed 40% of your equity, which in enCore Energy's case is 53%. Note that a higher debt obligation increases the risk around investing in the loss-making company.
Next Steps:
This article is not intended to be a comprehensive analysis on enCore Energy, so if you are interested in understanding the company at a deeper level, take a look at enCore Energy's company page on Simply Wall St. We've also compiled a list of essential aspects you should further research:
- Valuation: What is enCore Energy worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether enCore Energy is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on enCore Energy’s board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.