


EN
What Amprius Technologies Holders Got Wrong Before The Slide
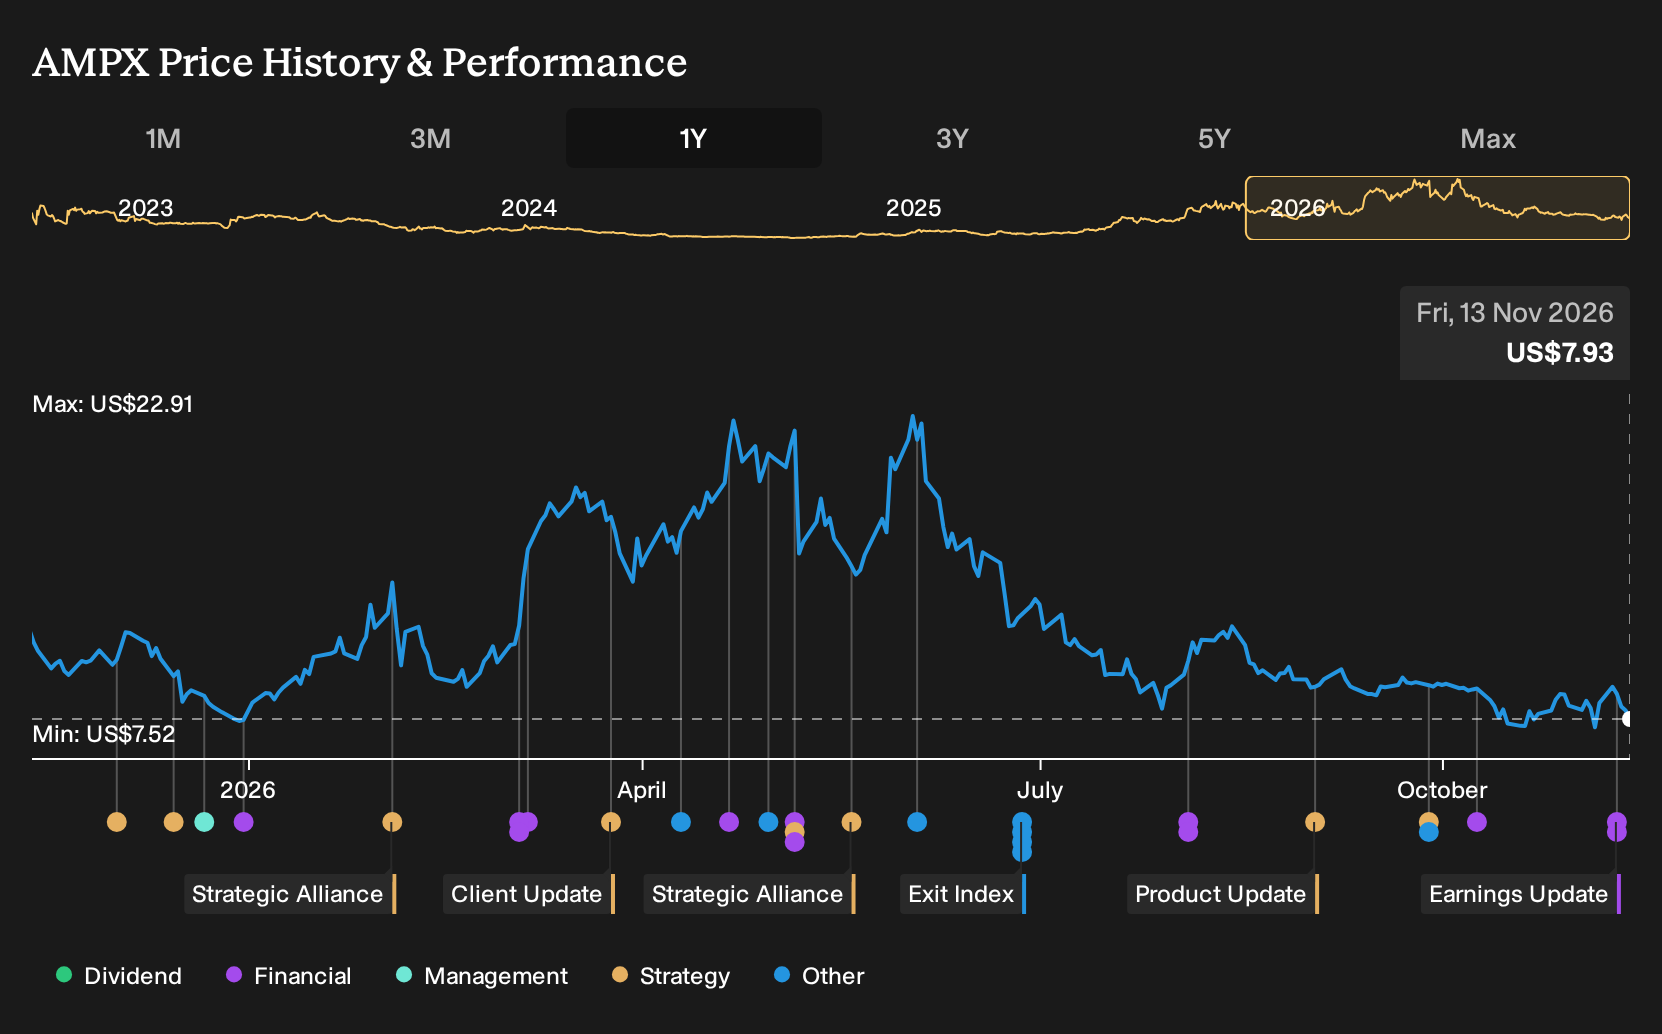
Amprius Technologies has been all over headlines this year, from record quarterly revenue and raised guidance to a sharp selloff after a short seller questioned its disclosures and supply chain ties. For Amprius Technologies shareholders, the loss over the past year was 29.8%, including dividends. If you had put capital to work just after analysts lifted targets in November 2025, how much of that slide reflects fresh risk versus expectations that were already on the table?
Amprius Technologies is not the only name tied to this theme. Zero in on 88 robotics and automation stocks and compare how each one is priced.
The Two Futures Investors Debated For Amprius Technologies
The shares cost US$11.72 at the start of the period, so anyone buying Amprius Technologies then had to decide which storyline felt more realistic.
On the bullish side, analysts were mapping out a Fair Value of US$13. This was a notional destination price based on assumptions like 89.8% annual revenue growth over three years and a future P/E of 190.6x.
The cautious view pointed to a Fair Value of US$10, anchored in expectations of 77.6% yearly revenue growth, a 10.2% profit margin, and ongoing exposure to aviation and drone concentration risk.
What The Amprius Technologies Results Put To The Test
The key development for Amprius Technologies was Q3 2026 revenue of US$39.1 million, compared with US$21.4 million a year earlier, alongside a net loss that narrowed from US$3.9 million to US$3.5 million and a net margin that moved from an 18.2% loss to an 8.9% loss. That mix of higher sales and still negative profitability cut both ways for the optimistic and cautious cases.
The lesson to carry elsewhere is simple. When a story leans heavily on future margin expansion, track the reported net margin line every quarter and compare it directly with the profitability step-up that was originally forecast.
What Amprius Technologies’ Lower Price Asks You To Believe
Amprius Technologies now trades at US$7.93, with the bullish analyst narrative on Simply Wall St suggesting a fair value above that level based on its own assumptions rather than a proven outcome.
The core question is whether a buyer today believes Amprius Technologies converts its defense focused pipeline into durable orders that support the current manufacturing ramp and cash generation profile.
"The main thing that has to go right is that Amprius Technologies converts its pipeline of defense, drone, and mobility programs, including large multi year contracts and U.S. government backed NDAA capacity, into sustained orders that support the current manufacturing ramp and margin profile."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
One Step Beyond Amprius Technologies
Thinking about Amprius Technologies highlights batteries, advanced materials and defense projects. Shifting perspective a little raises another angle.
If drones require lighter power sources, they also demand something less glamorous. Those airborne platforms still depend on a steady pipeline of expendable hardware.
Another business focuses on exactly that challenge today. It operates an ammunition line while developing its own drone platforms for defense and security buyers.
The compelling angle is how those consumable products repeat over time. Each deployment can open the door to another order and another production run.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 183% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com