


EN
Did ARB's Fall Catch You Out? What Bears Saw
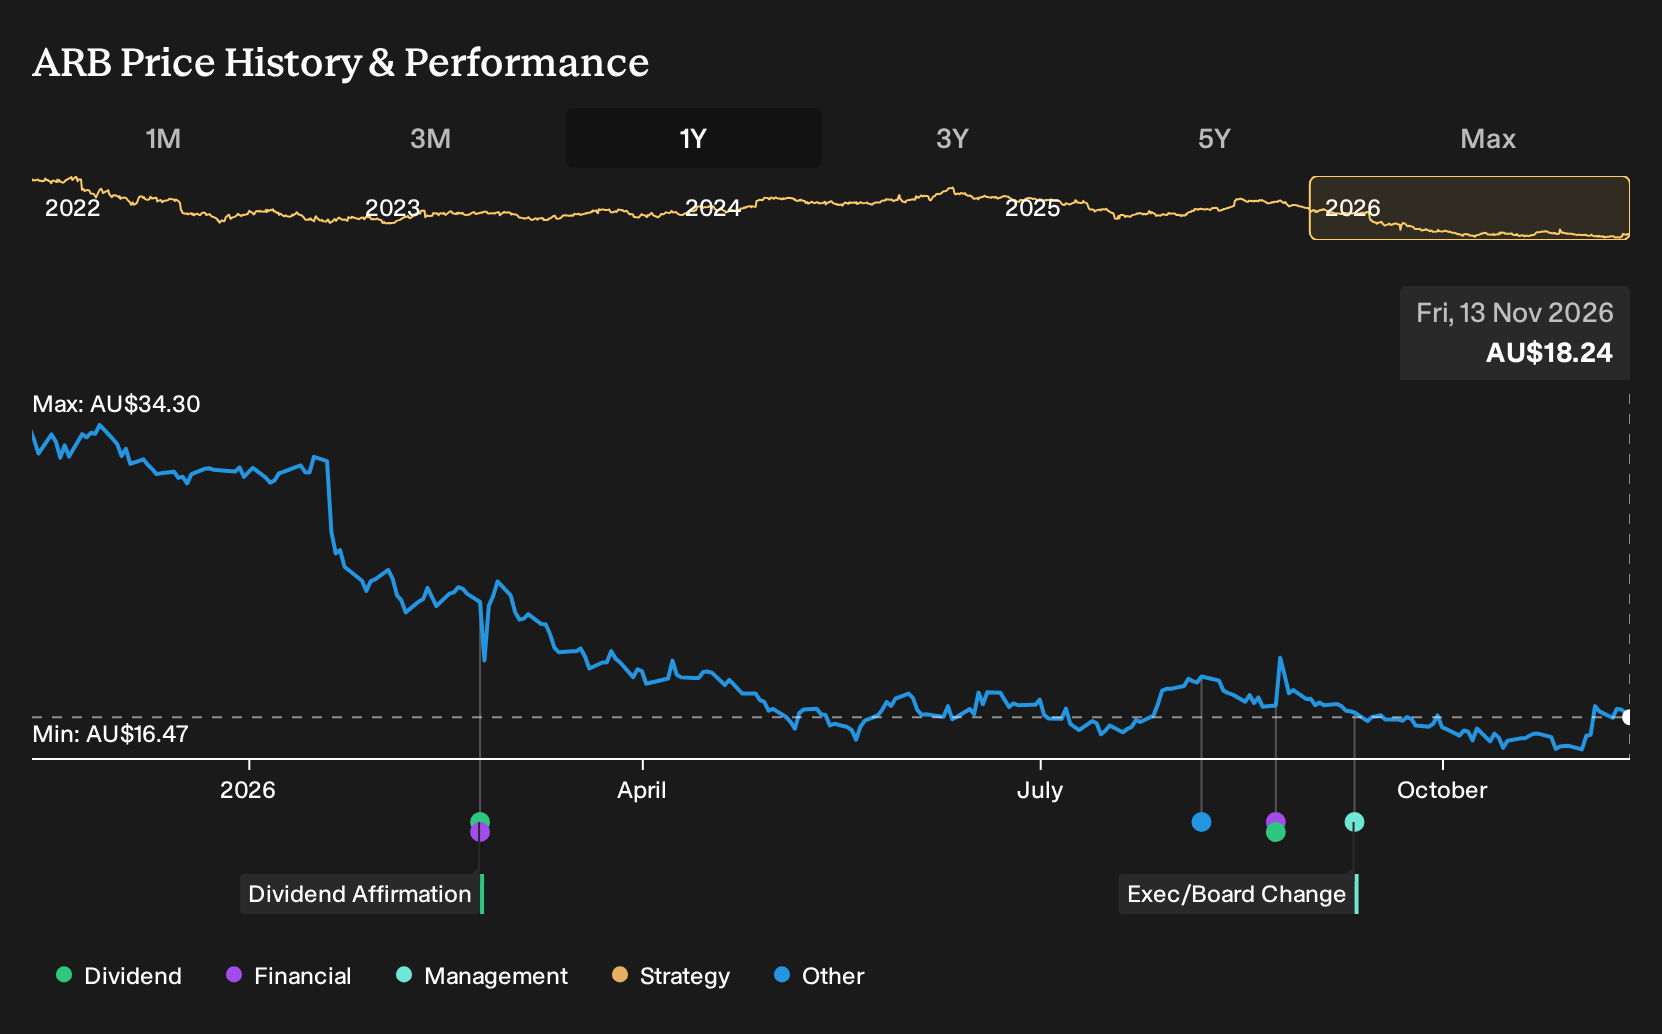
ARB’s headline numbers did not collapse during the period. Revenue softened while profit and net margin actually improved on the latest half-year figures, which makes the share price story far more jarring. For ARB shareholders, the loss over the past year was 42.2%, including dividends. If you had been weighing up a purchase in November 2025, what clues were already in view that this business result would pair with such a steep capital hit?
If the move has made ARB harder to judge, start where the gap is still open and scan 2 high quality undervalued stocks.
The Two Stories ARB Investors Were Weighing
The shares cost A$33.5 at the start of the period, and anyone looking at ARB then had two very different stories to consider.
On the upbeat side, one thesis saw global expansion and e-commerce as the key, with a Fair Value of A$40.5 that reflected a price implied by assumptions such as 8.0% annual revenue growth.
The more cautious view put Fair Value at A$27, built around concern that shrinking demand for traditional 4WD accessories and rising compliance costs would pressure margins.
What The ARB Evidence Actually Showed
ARB’s half-year figures told a split story. Revenue moved from A$367.374m in H2 2025 to A$344.405m in H2 2026, which leaned toward the cautious thesis on softer demand. Net income rose from A$46.575m to A$50.24m and net margin lifted from 12.7% to 14.6%, so profitability supported parts of the optimistic case. Overall, the evidence cut both ways.
The lesson for you is simple. When a growth story leans on margin strength, track the reported net margin and absolute profit, not just sales trends, to see whether that key assumption is actually holding up.
What ARB’s Lower Price Now Asks You To Believe
ARB trades at A$18.24 today, and the analyst consensus Narrative on Simply Wall St sees Fair Value as higher than that current price based on its own assumptions. That view leans on export growth, OEM programs and manufacturing changes to support margins.
For that Narrative’s higher figure to play out, a buyer today would need confidence that export expansion and OEM program volumes can offset softer Australian demand and keep profit margins resilient.
"The main requirement for success is that ARB continues to turn its higher engineering spend and deeper vertical integration into products that sell through its mixed store, partner and ecommerce network, while keeping margins resilient to FX movements and vehicle program timing."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 15% below our estimate - sells cloud, security and AI solutions as bundled managed services for customers.
- Company 2 - 27% below our estimate - supplies independent truck and bus parts as operators seek non-OEM distribution and support.
- Company 3 - 31% below our estimate - runs multi-brand electronics and appliance chains shifting sales toward higher-service installations.
That is three of the list. See the full list of 12 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com